
Cointime

Download App
iOS & Android

AI Hash Power “Digital Oil” Era Arrives: SuperStrike Launches Fourfold Ecosystem Sectors, STRIKE’s Secondary Market Logic and Value Reassessment

Validated Individual Expert

In the volatile cycles of the crypto market, projects that rely solely on conceptual expectations often struggle to maintain sustained price performance. Assets that truly break out with independent trends on the secondary market typically possess two characteristics: first, the circulating chip structure has undergone thorough turnover and sedimentation; second, there is genuine business revenue backed by rigid token burn mechanisms.

As the four major ecosystem sectors—SuperPay, SuperLine, the decentralized on-chain platform, and the prediction market—are about to land within the SuperStrike system, this article will deeply analyze STRIKE’s value reassessment logic from the perspectives of industry trends, the commercial closed loops of the four sectors, capital camps, and secondary market chip games.

I. Era Trends: The “Hash Power Consumption Tsunami” Brought by the Explosion of AI Agents

To evaluate the long-term value of a crypto asset, one must first examine the fundamental changes occurring in the industry it belongs to.

Artificial intelligence applications are evolving from mere Q&A chatbots into fully autonomous AI Agents (autonomous intelligent agents) with independent execution capabilities. Future network interactions will no longer involve humans frequently manually clicking software; instead, countless AI Agents will run 24/7 in the background on behalf of humans.

This brings a critical underlying logic shift for the secondary market:

  • Model Training: A one-time, phased hash power expenditure;
  • Agent Operation (Inference): High-frequency, long-term, ubiquitous real-time hash power consumption.

When tens of thousands of AI Agents worldwide begin automatically scraping data, allocating funds, and executing contracts, every instance of their thinking and interface calling represents rigid consumption of underlying hash power.

The expensive and rigid time-based billing models of centralized cloud providers simply cannot meet such high-frequency, micro-amount settlement needs. The market urgently requires infrastructure capable of flexibly matching global idle GPUs and settling on-demand micro-amounts with tokens. This is precisely the hundred-billion-level hash power settlement track that SuperStrike is entering.

II. Synergy of the Four Sectors: From Peripheral Commercial Cash Flow to Token Value Capture

Addressing the landing needs of hash power scheduling, SuperStrike has built four business sectors covering social, payment, trading, and hedging. Many investors are concerned about how these four sectors ultimately convert peripheral cash flow into value capture for the token.
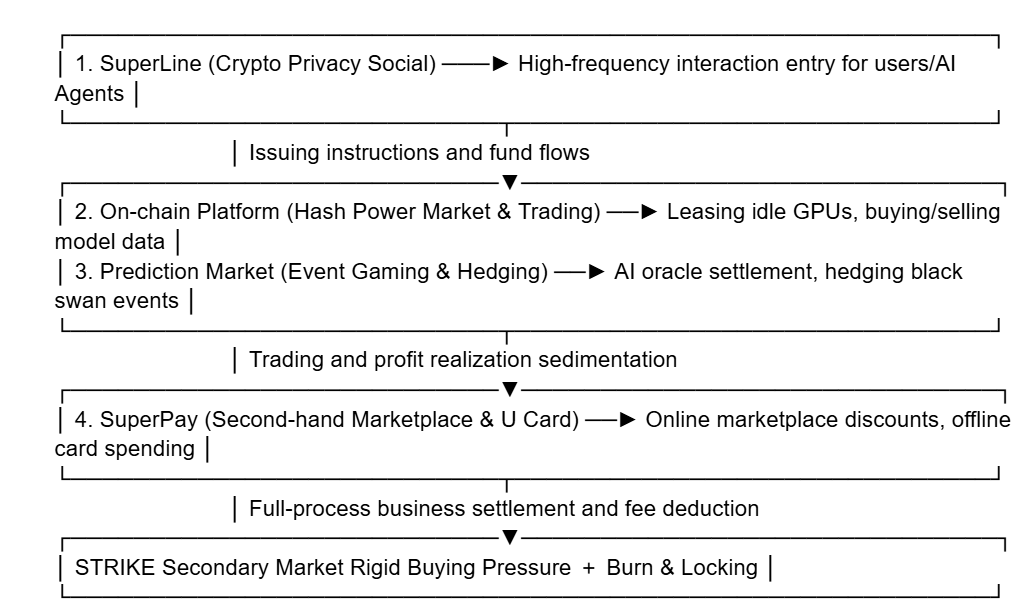
The four sectors achieve a highly closed loop in the transmission path of funds and demand:

  1. SuperLine (Social Traffic Entry): Protects privacy through zero-knowledge proofs and embeds AI intelligent assistants. Users can directly instruct AI to allocate assets and issue trading commands within the chat interface. Every agent invocation directly deducts STRIKE.
  2. Decentralized On-chain Trading Platform (Hash Power Trading Hall): Aggregates global idle GPUs for listing and rental. Developers rent hash power and purchase datasets on demand; the entire hash power market’s leasing and trading are settled entirely in STRIKE.
  3. Decentralized Prediction Market (Hedging and Gaming Center): Introduces AI Agents as unbiased referees for second-level settlement, attracting long-term capital to participate in event hedging. Oracle settlement services and the gaming process continuously extract STRIKE as service fees.
  4. SuperPay (Real-world Consumption and Monetization Pipeline): Combines a second-hand luxury goods marketplace with global VISA/U Card payment channels. Profits earned by users on-chain can seamlessly transfer to U Cards for offline spending; merchant onboarding staking and channel settlements require locking STRIKE.
Within this system, the four sectors generate real Stablecoin and fiat cash flows, all of which require conversion into or deduction of STRIKE during underlying settlement.

Users and merchants do not even need to understand complex token economics—as long as they use the products of these four sectors, they will invisibly generate rigid buying pressure and burn demand for STRIKE on the secondary market through the underlying protocol. This design of converting real commercial cash flow into token buying pressure is the key for the project to break free from merely relying on air inflation to sustain the ecosystem.

III. Chip Structure and Game Perspective: Washout Completed and Valuation Repair

From the perspective of secondary market trading and chip structure, STRIKE is currently in a very typical bottom-chip sedimentation phase:

1. Earlier Impulse and Chip Sedimentation

Looking back at the previous price action, STRIKE steadily rose from the earlier low of 0.06 USDT, breaking through resistance to 0.13 USDT, fully demonstrating the strength of main force capital accumulation and market consensus. It then followed the broader market’s volatile pullback, relatively cleanly clearing out earlier short-term profit-taking floating chips.

This pullback completed turnover on the technical level, supplemented trading depth on the board, and formed a relatively healthy chip structure for the subsequent launch of the four sectors and the next wave of market movement.

2. Deflationary and Staking Effects on Circulating Supply

As the four businesses come online successively, the token will face dual locking and deflationary pressures:

  • Node and Business Staking: Merchant onboarding for SuperPay, hash power node listings, and the system’s withdrawal protection net (T+1 verification buffer period) will lock up large amounts of circulating chips;
  • Rigid Burn (Sburn): SuperLine agent invocation fees, prediction market oracle fees, and hash power consumption are directly proportionally sent to the black hole for burning.

The continuous contraction of circulating supply means that any subsequent new capital inflow can generate relatively strong upward price elasticity.

IV. Institutional Camp and Trading Platform Layout

Assessing a project’s risk resistance cannot be separated from its underlying capital and resource network:

  1. Backed by the technical origin of StrikeBit AI: SuperStrike inherits StrikeBit AI’s technical legacy in decentralized AI assembly, enabling low-cost invocation of global computing nodes and ensuring the stable operation of the four businesses at the technical level.
  2. Strategic bets from top-tier institutions: The project and its ecosystem have received investments from well-known institutions in the crypto and hardware infrastructure tracks, including FBG Capital, Waterdrip Capital, DePIN X, and IoTeX. These institutions not only bring capital but also overseas community resources and hardware node expansion.
  3. Expectations for mainstream trading platforms (CEX): With the advancement of the four businesses’ launches, the project’s liquidity matrix is also accelerating expansion. Leveraging the industry resources of top investment institutions, the team is actively advancing docking with major global mainstream leading trading platforms, providing clear expectations for future liquidity release.

V. Summary and Token Expectations

In the current crypto market, capital is increasingly focused on a project’s fundamentals and self-sustaining capabilities.

SuperStrike’s core logic is pure: supported by StrikeBit AI technology, it uses the four high-frequency application sectors—SuperPay, SuperLine, the on-chain trading platform (DEX), and the on-chain prediction market—to import real business cash flows, ultimately consolidating all revenue and consumption onto STRIKE as the “hash power Gas fee.”

When the token possesses genuine burn, staking, and buying demand, combined with the previously completed chip turnover on the board and the endorsement of the institutional camp, STRIKE has a clear foundation for value reassessment during the upcoming business landing verification period. The project’s subsequent business data and market performance deserve continuous attention.

Comments

All Comments

Recommended for you

  • Iran and Gulf States to Hold Meeting Next Week to Advance Strait of Hormuz Agreement

    On September 11, the Financial Times reported that foreign ministers from Gulf states plan to meet with the Iranian foreign minister in response to initiatives from Oman and Iran, seeking support for an agreement on the temporary management of shipping in the Strait of Hormuz. Meanwhile, countries in the region are looking for ways to ease the hostile situation surrounding this waterway. This meeting, proposed by Oman, will be the first between senior diplomats from the Gulf Cooperation Council, consisting of six member states, and Iranian officials since the outbreak of the U.S.-Iran conflict at the end of February. According to sources, the meeting is scheduled to take place next Monday in Salalah, a coastal city in Oman. Details have not been finalized, but several countries have confirmed that the meeting is expected to proceed as planned. If the meeting takes place, it will highlight the region's urgency to attempt to reopen the strait and ease U.S.-Iran tensions.

  • Iran and Gulf States to Hold Meeting Next Week to Advance Hormuz Strait Agreement

    On September 11, the Financial Times reported that foreign ministers from Gulf states plan to meet with the Iranian foreign minister in response to initiatives from Oman and Iran, seeking support for an agreement on the temporary management of shipping in the Hormuz Strait. Meanwhile, countries in the region are looking for ways to ease the hostile situation surrounding this waterway. This meeting, proposed by Oman, will be the first encounter between senior diplomats from the Gulf Cooperation Council, comprising six member states, and high-ranking Iranian officials since the outbreak of U.S.-Iran conflicts in late February. According to sources, the meeting is scheduled to take place next Monday in Salalah, a coastal city in Oman. Details have yet to be finalized, but several countries have confirmed their participation, and the meeting is expected to proceed as planned. If the meeting takes place, it will underscore the region's urgency in attempting to reopen the strait and de-escalate U.S.-Iran hostilities.

  • US Spot Bitcoin ETF Sees $282.7 Million Net Outflow

    According to monitoring data from Farside Investors, the US spot Bitcoin ETF experienced a net outflow of $282.7 million yesterday, September 11.

  • US Spot Bitcoin ETF Sees $282.7 Million Net Outflow

    According to monitoring data from Farside Investors, the US spot Bitcoin ETF experienced a net outflow of $282.7 million on September 11.

  • US Spot Ethereum ETF Sees Net Outflow of $29.9 Million Yesterday

    On September 11, according to monitoring data from Farside Investors, the US spot Ethereum ETF experienced a net outflow of $29.9 million yesterday.

  • US Spot Ethereum ETF Sees Net Outflow of $29.9 Million Yesterday

    On September 11, according to monitoring data from Farside Investors, the US spot Ethereum ETF experienced a net outflow of $29.9 million yesterday.

  • Sources: Bank of Japan Expected to Raise Rates by 25bps Next Week with No Predefined View on Terminal Rate

    On September 11, sources revealed that the Bank of Japan is expected to raise interest rates next week, most likely by 25 basis points, and may indicate a faster tightening pace if inflationary pressures increase. Raising rates to 1.25% would mark the highest policy rate for the Bank of Japan in 31 years. The move comes just three months after the last rate hike in June, signaling an acceleration in tightening measures. Many within the central bank believe that as the economy enters a moderate recovery and price pressures build, the conditions for another rate hike are becoming favorable. The central bank also anticipates that even if rates rise to 1.25%, financial conditions will remain accommodative. The market is closely watching Governor Ueda's comments after the meeting for any clues regarding the future pace of rate hikes and the potential peak rate in this tightening cycle. Sources indicated that the Bank of Japan may have no predefined view on the terminal rate, which will depend on how past rate hikes affect the economy and the extent to which businesses pass on rising costs to households. There is also no consensus within the Bank of Japan on the speed of rate hikes. Ueda is expected to avoid committing to a specific timeline for future rate increases but may reiterate the July statement that if financial conditions are deemed too loose, the Bank of Japan may accelerate rate hikes.

  • Sources: BOJ Expected to Raise Rates by 25bps Next Week Without Predefined Terminal Rate View

    On September 11, sources revealed that the Bank of Japan (BOJ) is expected to raise interest rates next week, most likely by 25 basis points, and may hint at a faster tightening pace if inflationary pressures increase. Raising the rate to 1.25% would mark a 31-year high for the BOJ's policy rate. This move comes just three months after the last hike in June, indicating a quicker tightening pace. Many within the central bank believe that conditions for another rate increase are forming as the economy enters a moderate recovery and price pressures build. The BOJ also anticipates that even with rates rising to 1.25%, financial conditions will remain accommodative. The market is closely watching Governor Kazuo Ueda for any clues regarding the future pace of rate hikes and the potential peak rate in this tightening cycle. Sources indicate that the BOJ may not have a predefined view on the terminal rate, as it depends on how past rate hikes affect the economy and the extent to which businesses pass on rising costs to households. There is also no consensus within the BOJ on the speed of rate hikes. Ueda is expected to avoid committing to a specific timeline for future rate increases but may reiterate his July statement that the BOJ could accelerate rate hikes if it believes financial conditions are too loose.

  • SEC Proposes Amendments to Transfer Agent Rules, Allowing Blockchain Ledgers as Official Records of Securities Ownership

    On September 11, the U.S. Securities and Exchange Commission (SEC) proposed a new rule that aims to comprehensively amend the transfer agent rules that have been in place for decades. For the first time, the proposal explicitly allows electronic databases, including blockchain ledgers, to serve as official records of securities ownership. If approved, blockchain could become the 'primary securities document,' replacing the off-chain parallel ownership records that tokenized securities currently rely on. Currently, many tokenized securities operate on two sets of records: an on-chain token ledger and an official shareholder register. Once the proposal is passed, issuers and transfer agents may no longer need to maintain duplicate records and reconcile them after each transfer, thereby reducing operational friction and the risk of inconsistencies between on-chain records and legally recognized records. Eli Cohen, Chief Legal Officer of the tokenized fund platform Centrifuge, stated that this proposal could transform the current 'two-step' process into a 'one-step' process, allowing the blockchain itself to act as the primary securities document. However, the proposal does not imply that tokenized securities will be completely 'permissionless.' Joris Delanoue, CEO of the SEC-registered on-chain transfer agent Fairmint, pointed out that while the blockchain can remain open, assets must still comply with ownership and transfer rules, and regulatory controls such as identity verification and transfer restrictions will still be embedded in the tokens. Transfer agents will still need to handle administrative matters such as shareholder death, inheritance, and legal notifications, with processing times potentially reduced from 3-5 days to 1 day. The 60-day public comment period for the proposal will end in early November.

  • SEC Proposes Amendments to Transfer Agent Rules, Allowing Blockchain Ledgers as Official Securities Ownership Records

    On September 11, the U.S. Securities and Exchange Commission (SEC) proposed a new rule last week aimed at comprehensively revising the transfer agent rules that have been in place for decades. For the first time, it explicitly allows electronic databases, including blockchain ledgers, to serve as official records of securities ownership. If approved, blockchain is expected to become the 'primary securities document,' replacing the off-chain parallel ownership records that tokenized securities currently rely on. Currently, many tokenized securities operate on two sets of records: an on-chain token ledger and an official shareholder register. Once the proposal is passed, issuers and transfer agents may no longer need to maintain duplicate records and reconcile them after each transfer, thereby reducing operational friction and the risk of inconsistencies between on-chain records and legally recognized records. Eli Cohen, Chief Legal Officer of the tokenized fund platform Centrifuge, stated that the proposal could transform the current 'two-step' process into a 'one-step' process, allowing the blockchain itself to serve as the primary securities document. However, the proposal does not mean that tokenized securities will be completely 'permissionless.' Joris Delanoue, CEO of Fairmint, a registered on-chain transfer agent, pointed out that while the blockchain can remain open, assets must still comply with ownership and transfer rules, and regulatory controls such as identity verification and transfer restrictions will still be embedded in the tokens. Transfer agents will still need to handle administrative matters such as shareholder death, inheritance, and legal notifications, with processing times potentially reduced from 3-5 days to 1 day. The 60-day public comment period for the proposal will end in early November.