

Summary of September 2023
September experienced a broad-based market correction as the U.S. Dollar Index surged to its 2023 yearly high. The S&P500 depreciated by 5.3%, while the Nasdaq declined by 6.4%. Gold retraced 4.7%. However, Bitcoin stood out performing well, recording a 4% increase in September. The de-correlation between the performance of Bitcoin and these major financial instruments warrants continuous monitoring. Generally speaking, the strengthening of the U.S. Dollar results in a risk-off market environment, which often leads to underperformance of equities and risky assets, including cryptocurrencies.
The market correction was accompanied by rising long-dated treasury yields, with 10-year, 20-year, and 30-year bonds reaching their highest levels since 2008. The Federal Reserve maintained interest rates at 5.25% to 5.5% in September FOMC, while the market has started pricing in potential rate cuts as early as the second half of 2024. The increase in the consumer price index (CPI) to 3.7% in August, coupled with rising energy prices, provoked concern regarding the efficacy of efforts to combat inflation.
In this macroeconomic context, commercial traders on CME maintained aggressive net short positions with Bitcoin. The collective cryptocurrency markets experienced reduced trading volume and activity. The Aggregate Open Interest with Bitcoin Perpetual Futures did not recover since the last sell-off. Additionally, there was a shift in trading volume from BTCTUSD to BTCFDUSD on Binance, following the launch of FDUSD on their exchange, which could present new trading opportunities for market participants.
In terms of regulatory developments, the U.S. Securities and Exchange Commission (SEC) has recently postponed its decision on Spot Bitcoin ETF applications, which includes prominent applicants such as BlackRock and Fidelity. Concurrently, the SEC warned that additional crypto exchanges, dealers, and brokers could face charges regarding inadequate disclosures or failure to register with the agency.
Market Commentary
- Macro Economic Outlook
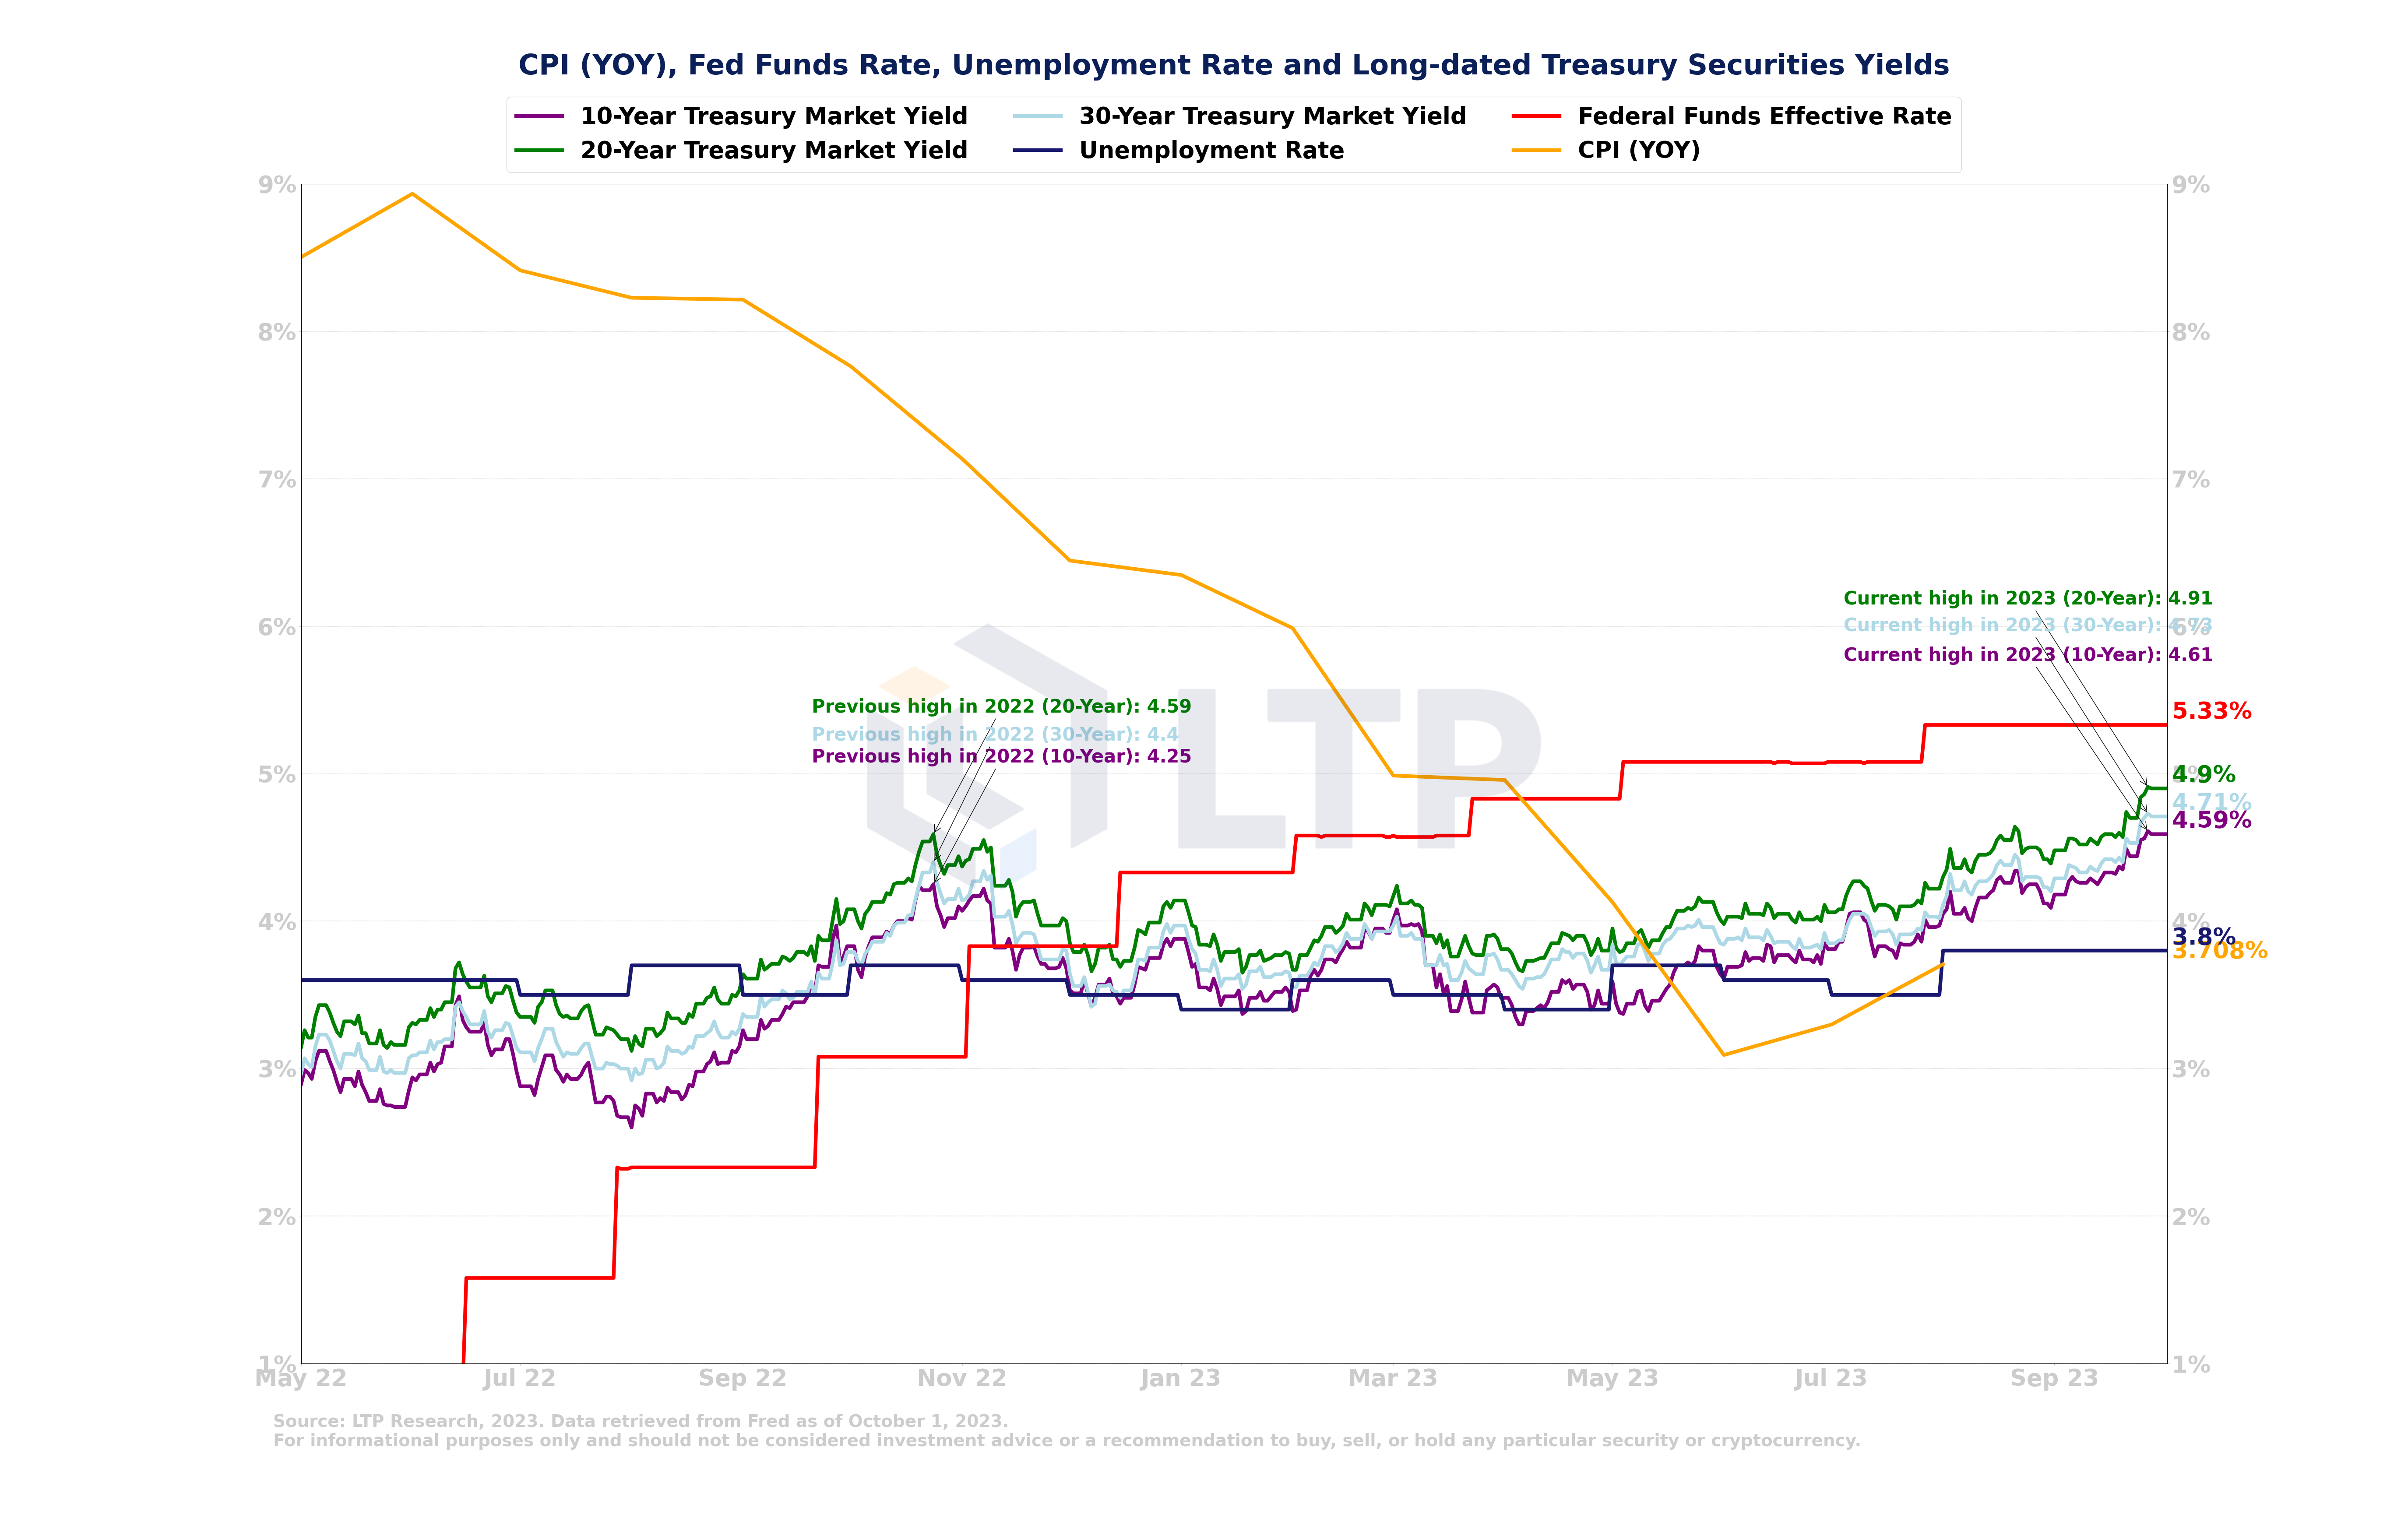
The August Consumer Price Index (CPI) year-over-year (YOY) inflation rate surprised to the upside, climbing to 3.7%, exceeding expectations and fueling concerns about the potential for sustained inflationary pressures. This development was reinforced by the continued ascent of long-dated Treasury securities yields, including the 10-year, 20-year, and 30-year, which broke all-time highs since 2008. The surge in Treasury yields suggests that investors are increasingly uneasy about the prospect of higher interest rates and inflation in the medium to long term. Meanwhile, the Federal Reserve maintained the interest rates at 5.25%-5.5% in September.
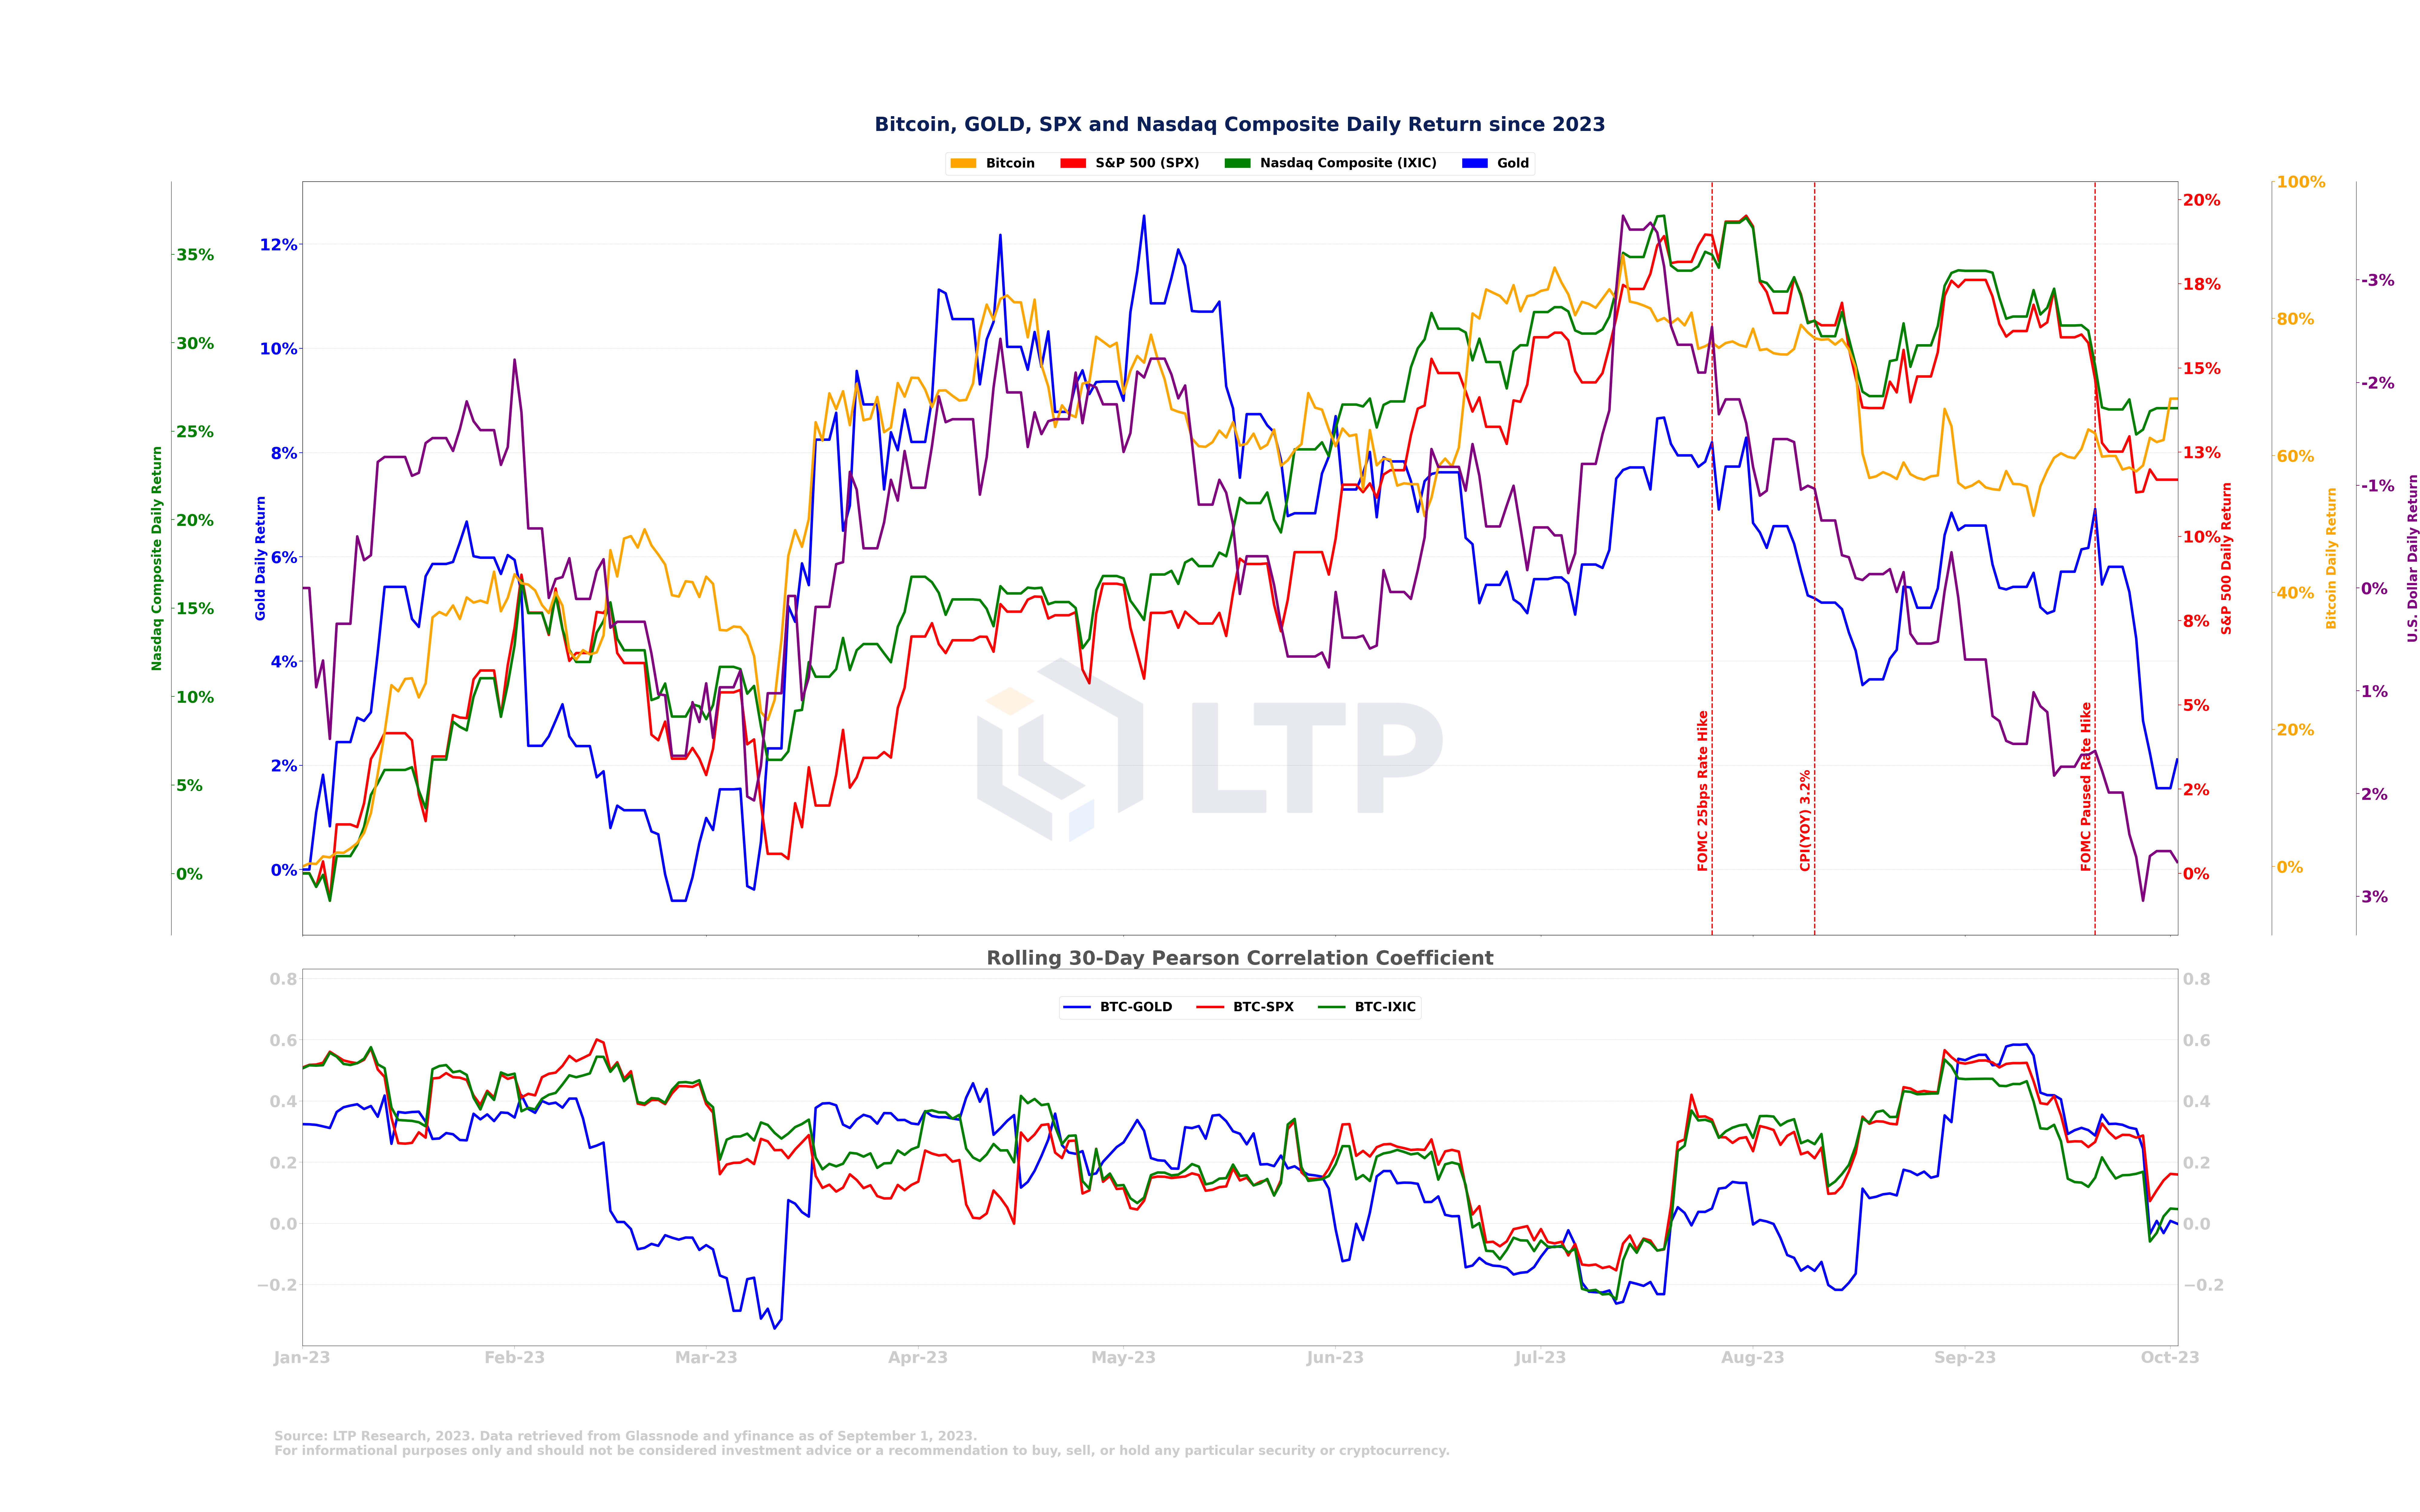
In September, a widespread market correction occurred as a result of the US Dollar's strong performance, leading to a significant pullback across major asset classes. The S&P 500 Index, Nasdaq Composite, and gold all experienced declines, which coincided with the resurgence of the US Dollar Index. The S&P 500 depreciated by 5.3% during the month, while the Nasdaq declined by 6.4%. Gold also faced challenges, resulting in a loss of 4.7%. However, Bitcoin stood out performing well, recording a 4% increase in September. The correlation between Bitcoin and the S&P 500, Nasdaq, and Gold decreased, indicating that Bitcoin moved independently. This raises the question of whether Bitcoin's appreciation in September will be sustained in October.
2. Cryptocurrency Market Commentary
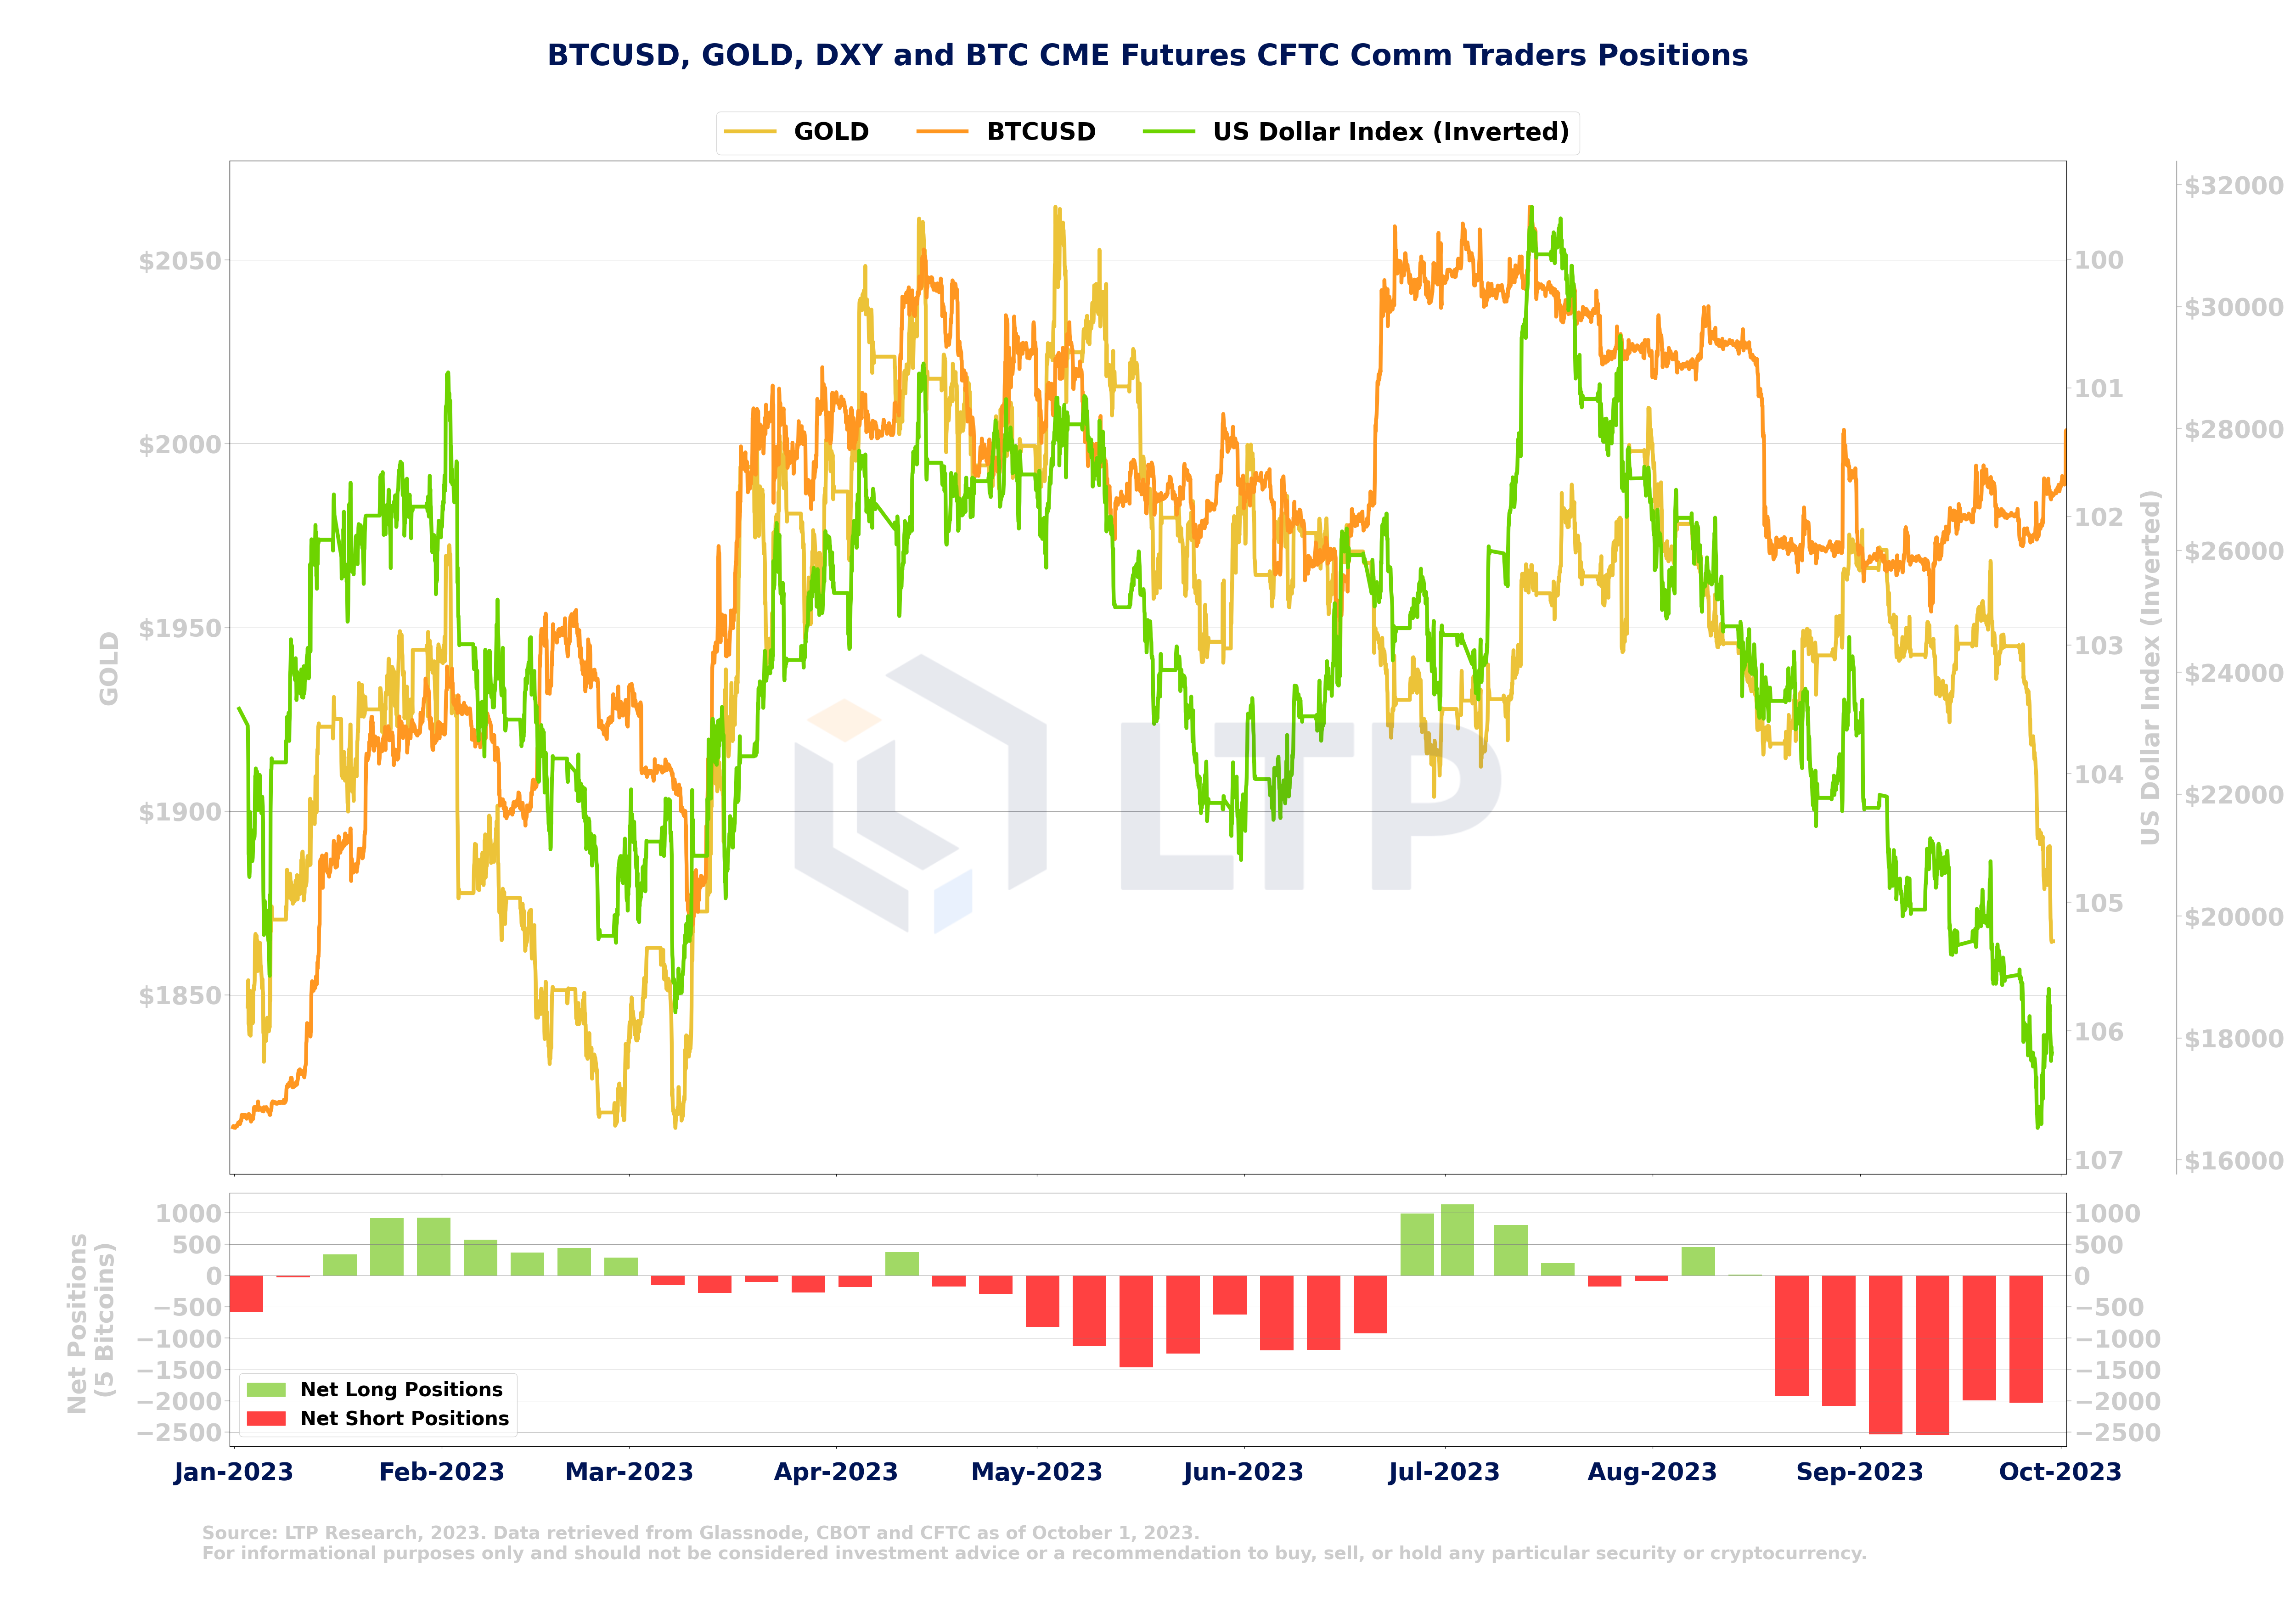
Against the backdrop of a strengthening Dollar, weakening risk appetite for equities and risky assets in the macro environment, commercial traders on the Chicago Mercantile Exchange (CME) maintained an aggressive record net short position in September, according to the latest Commitment of Traders (COT) reports.
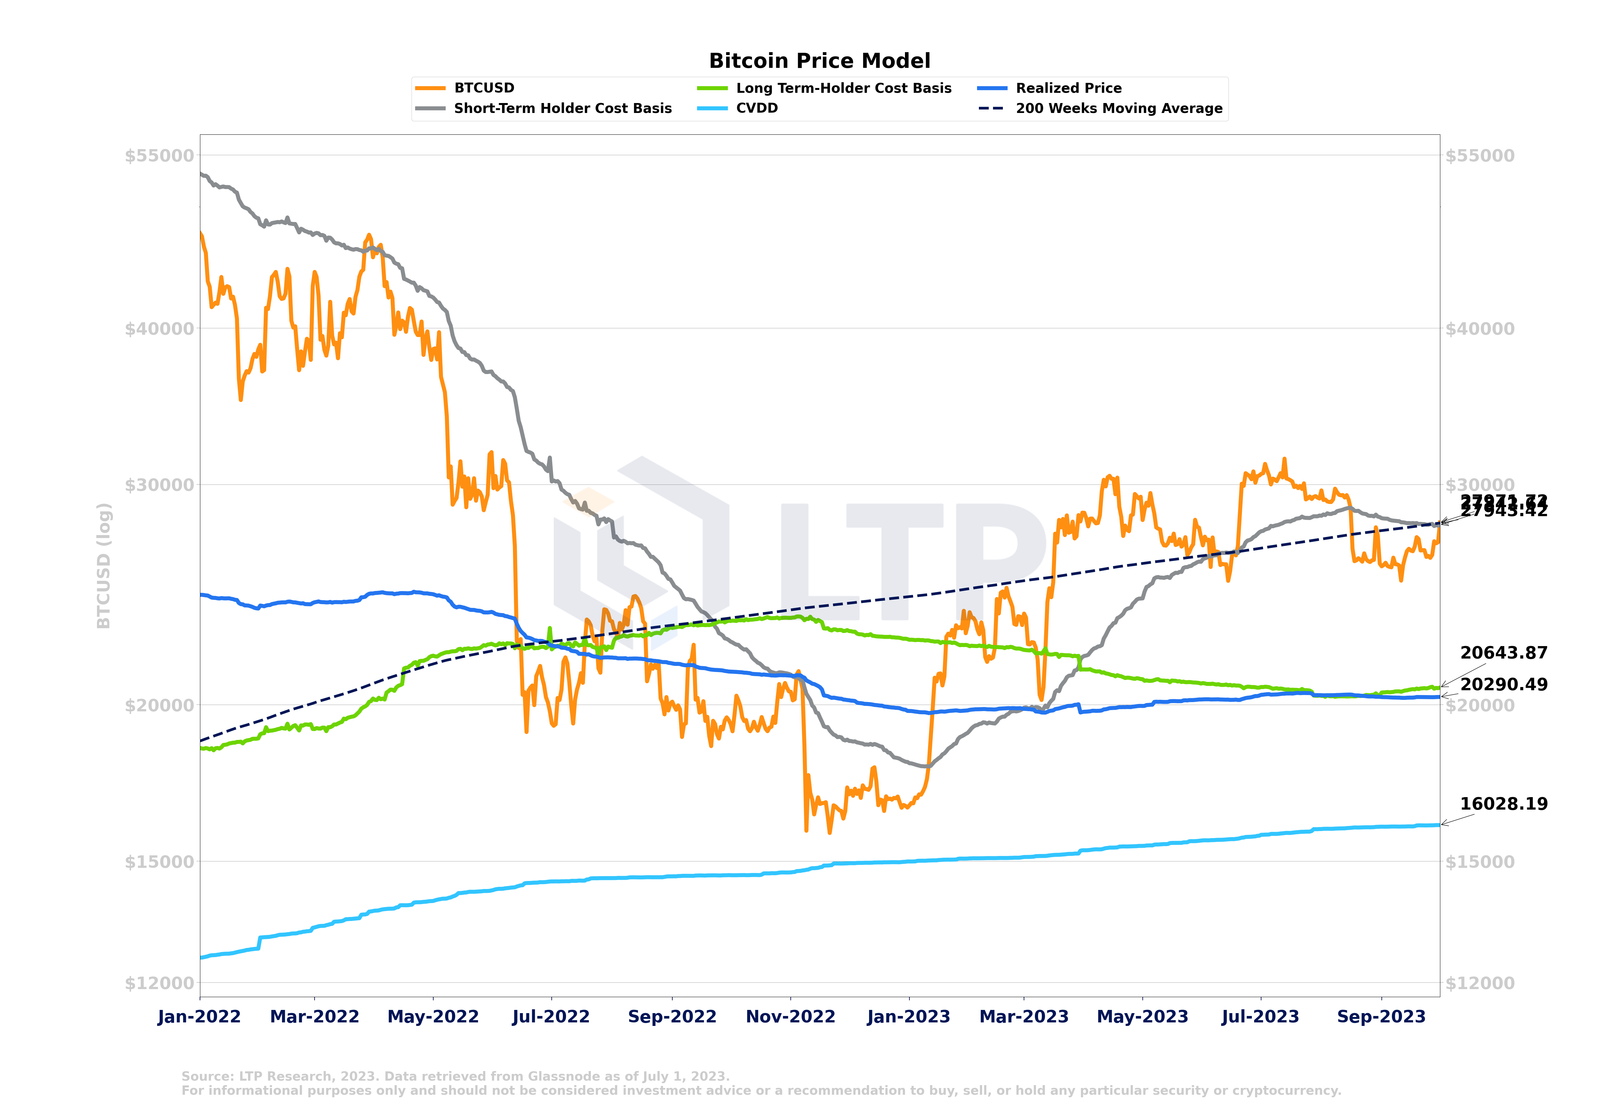
In September, the price of Bitcoin exhibited consolidation below both the 200-Week Moving Average and the short-term holder cost basis. The 200-Week Moving Average, a commonly utilized trend indicator, is considered significant, as a price below it may indicate a potential transition into a downtrend. Currently, the price is undergoing a retest of this level. Furthermore, there was convergence between the realized price and the long-term holder cost basis at $20,600.
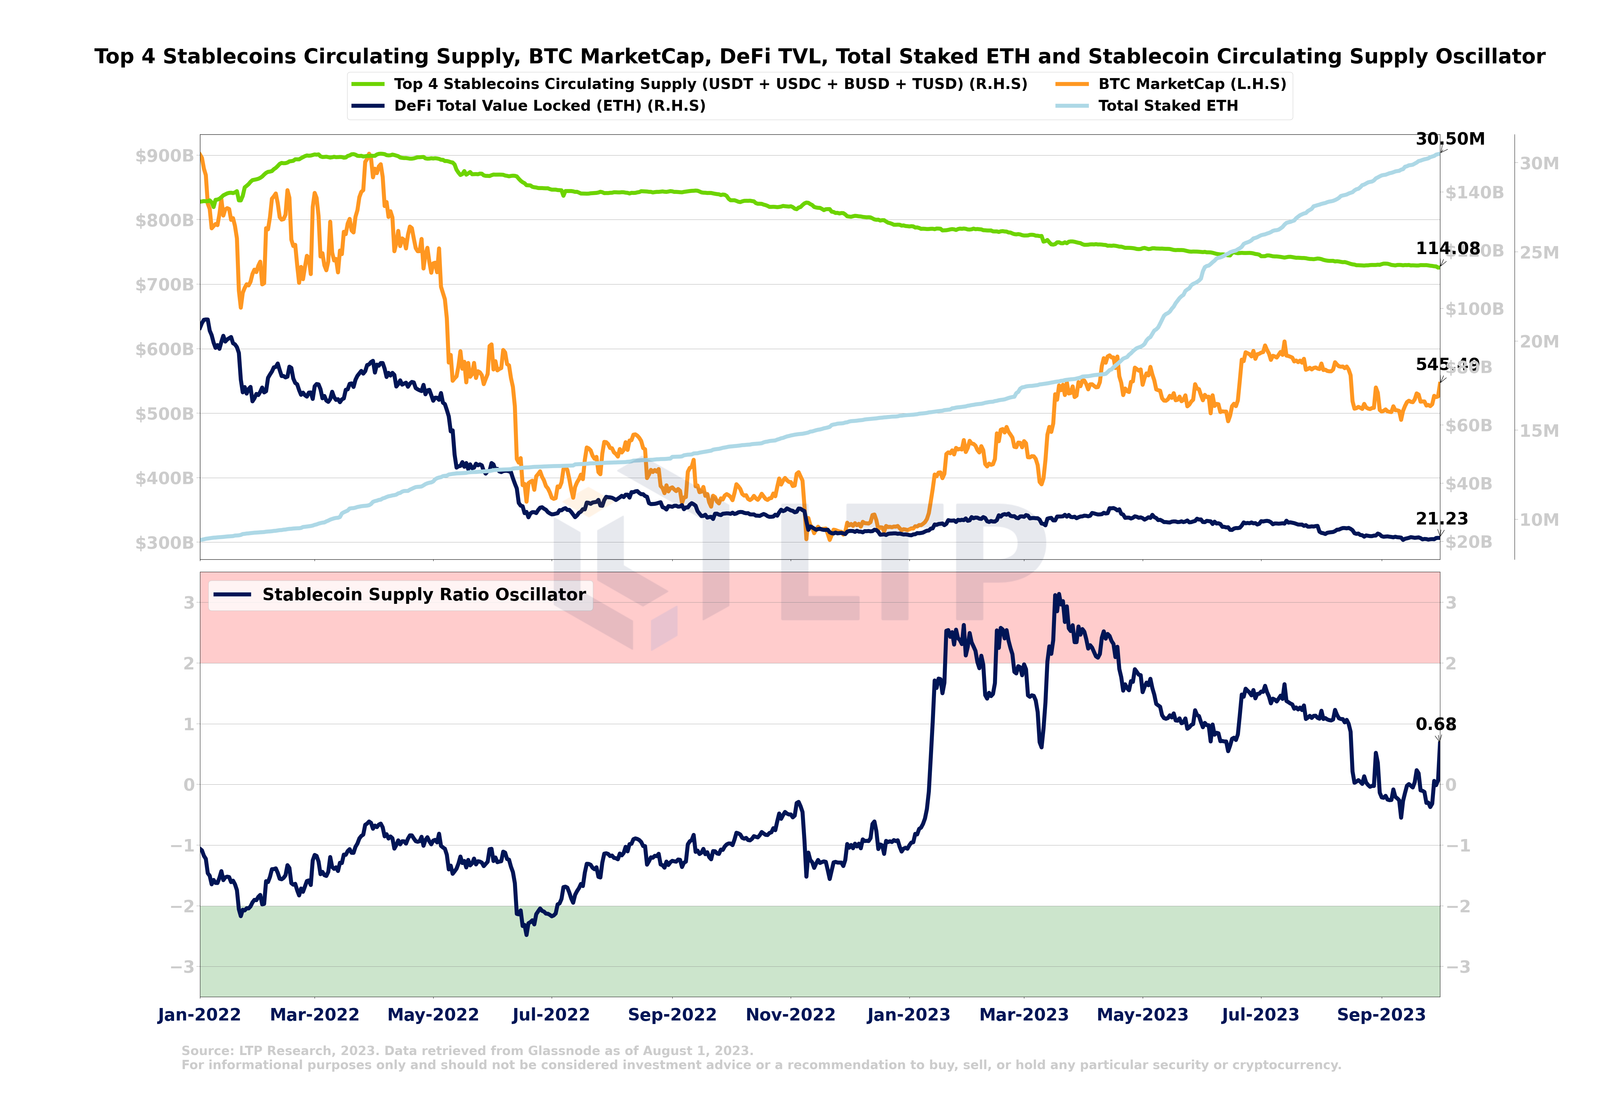
Bitcoin's market capitalization remained stable in September, as the price remained stagnant throughout the month. Meanwhile, the number of staked Ethereum continued to increase, reaching 30.5M, with more Ethereum holders staking their holdings to earn staking rewards. According to StakingRewards, the current staking yield stands at 3.5%. Additionally, the total value locked (TVL) in DeFi remained subdued, ending the month at $21.2 billion. The circulating supply of the top 4 stablecoins continued to decline, reaching $114 billion.
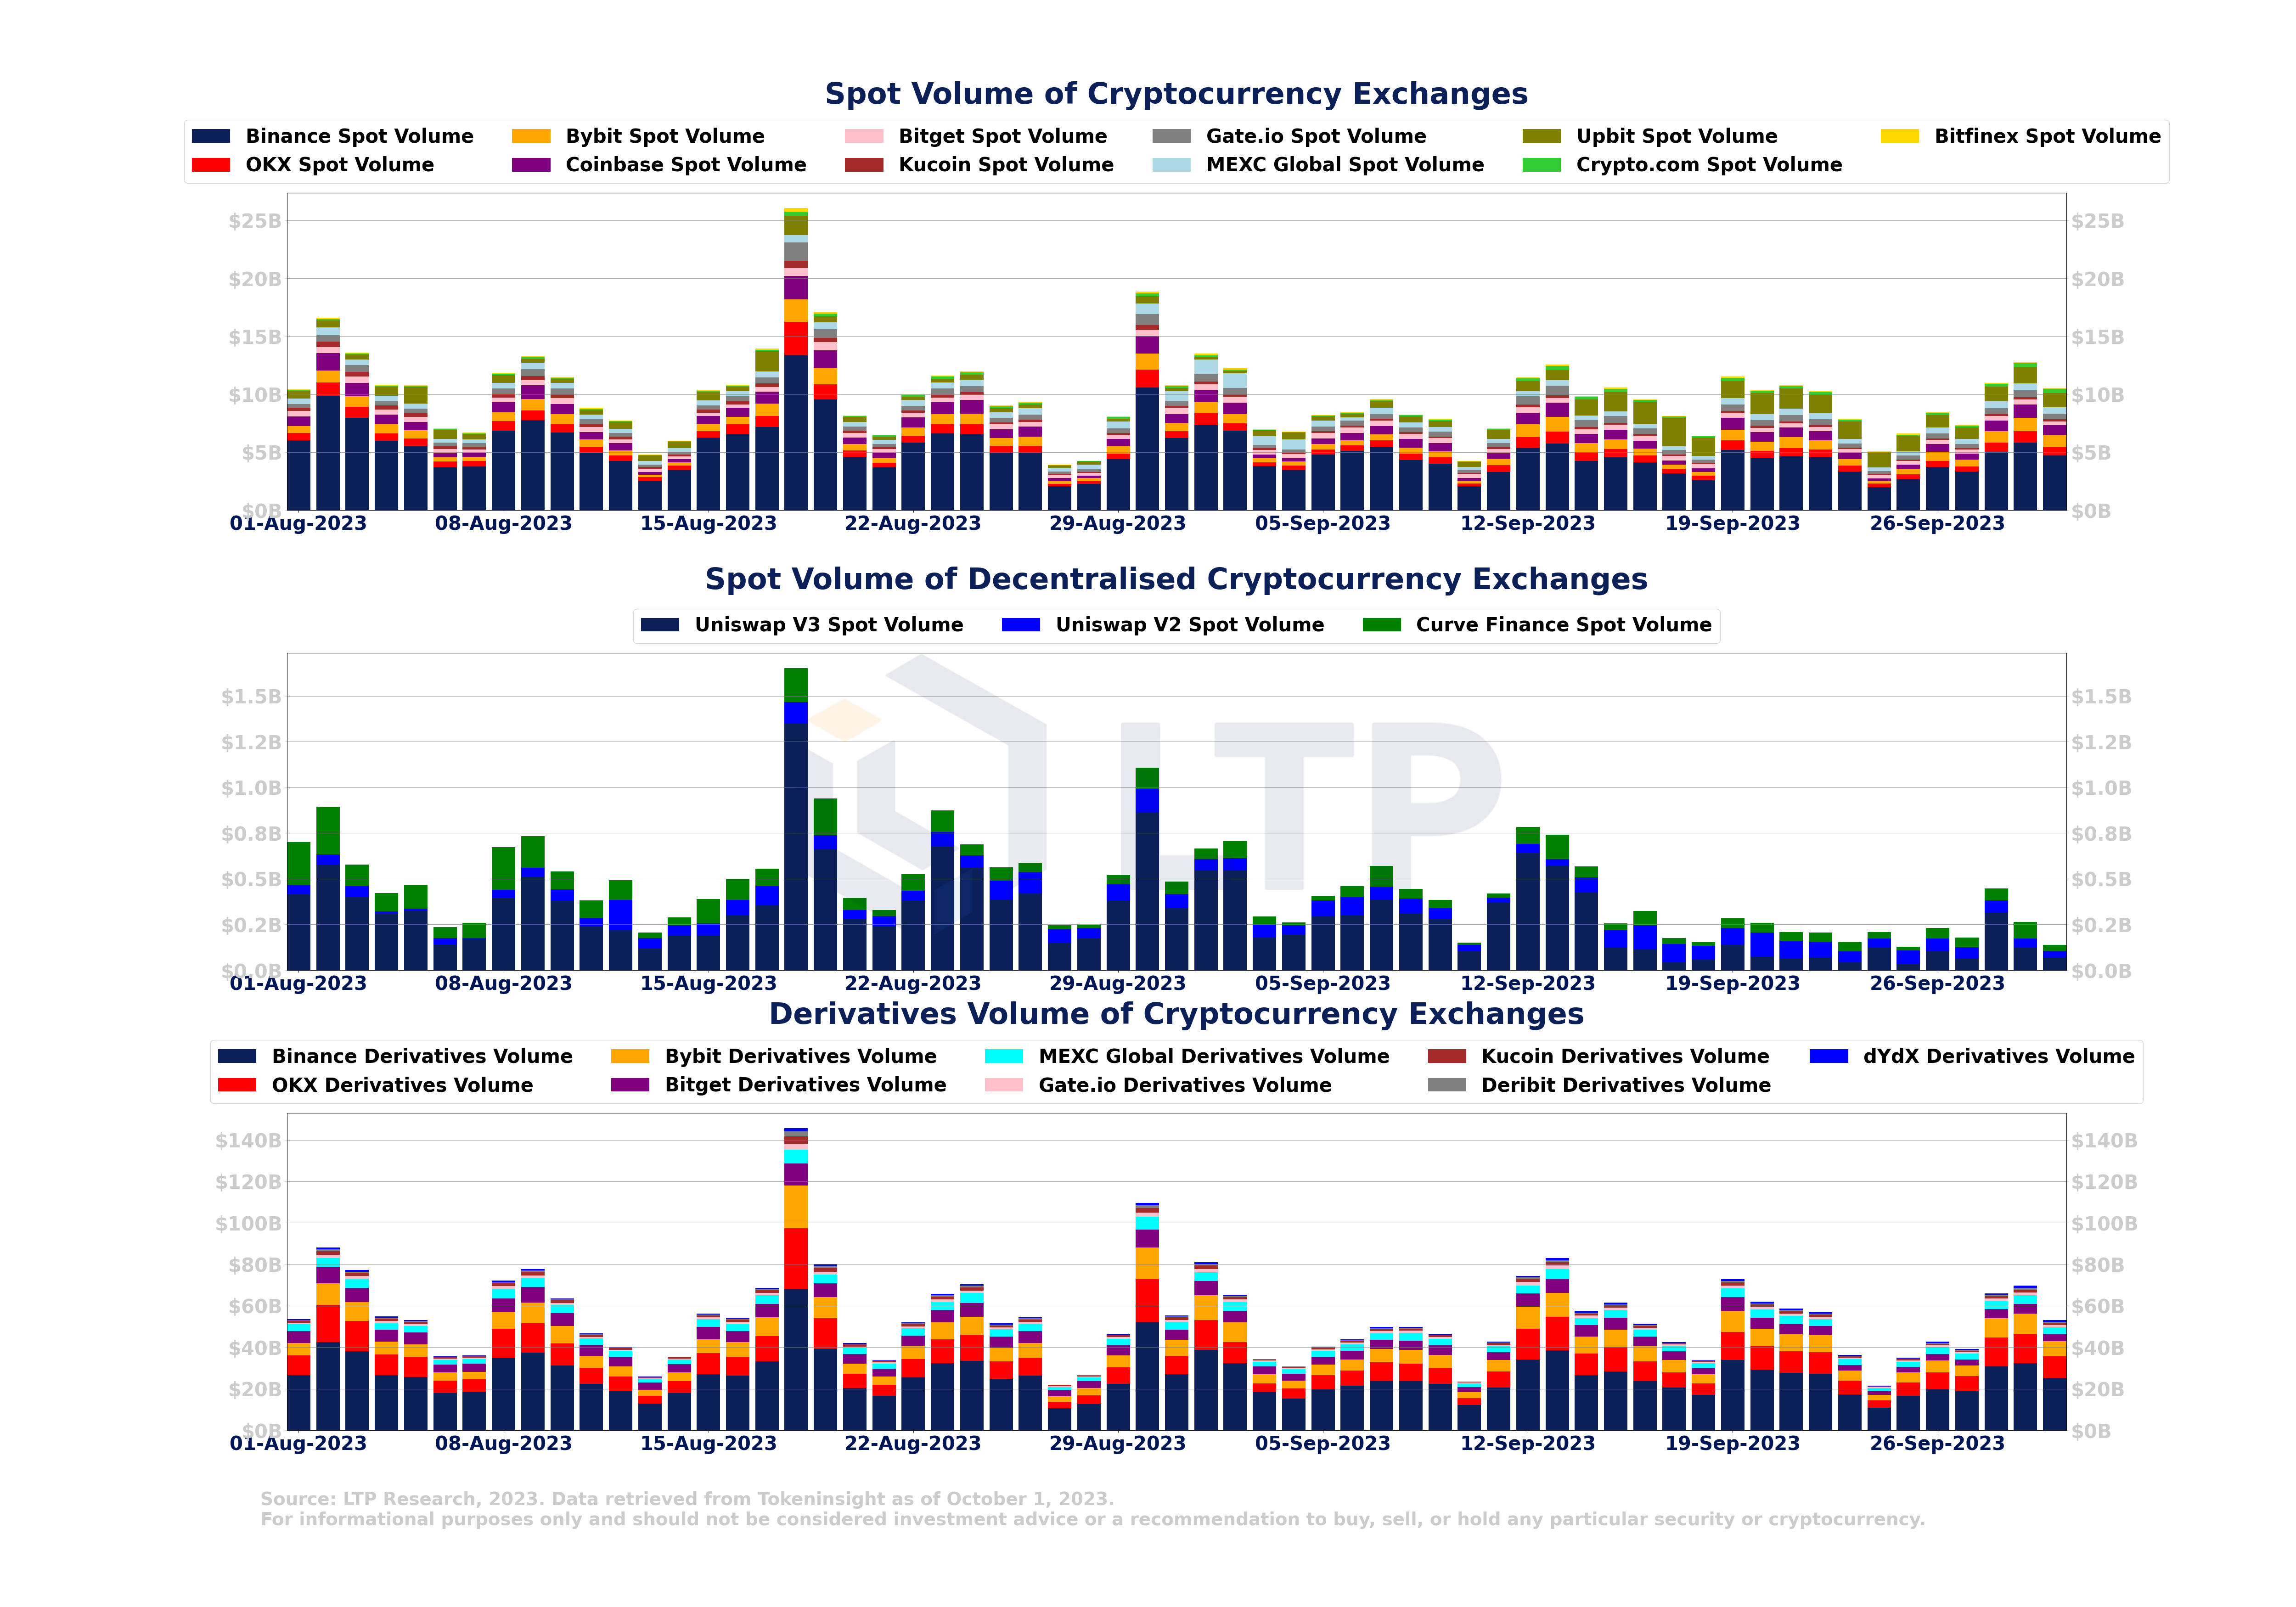
In September, the spot trading volume of Centralized Exchanges remained relatively stable comapred to August. However, Upbit recorded a significant rise in trading volume. On the other hand, spot volume of Decentralized Exchanges experienced a decrease in September. With derivatives, the trading volume on major Centralized Exchanges remained relatively unchanged compared to August.
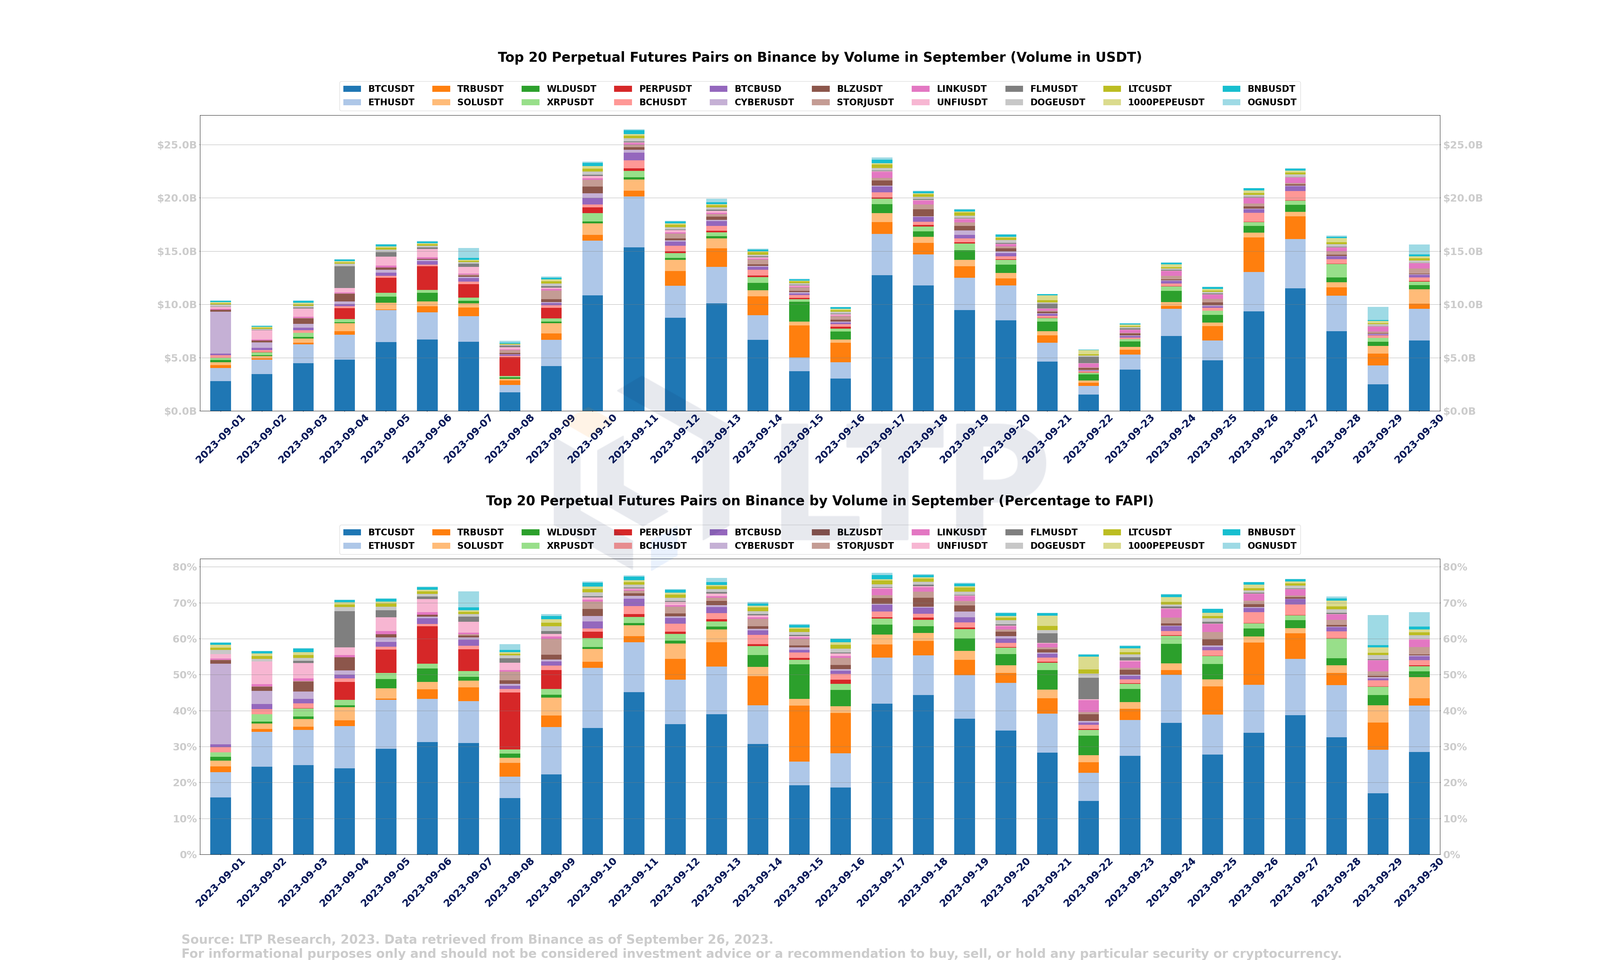
In early September, there was a notable increase in trading volume for CYBER and PERP. Similarly, in mid-September, TRB experienced a significant rise in trading volume.It is observed that weekend trading volume for Bitcoin and Ethereum was generally subdued. However, certain altcoins such as PERP, TRB, and WLD saw active trading on weekends.
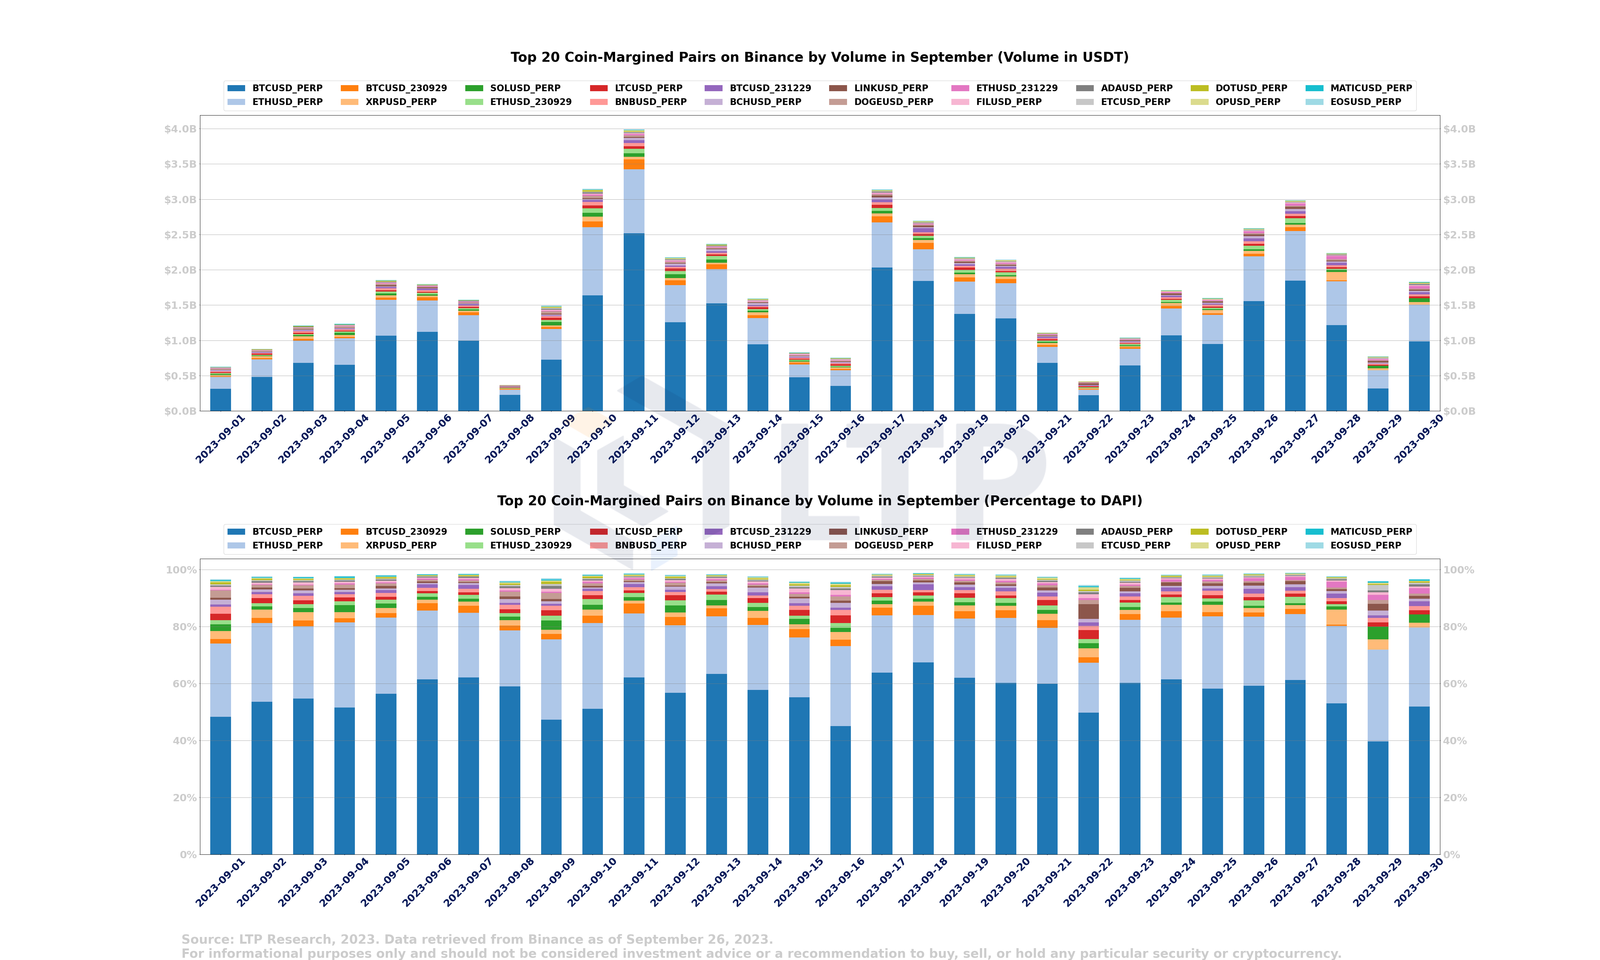
BTCUSD_PERP and ETHUSD_PERP accounted for nearly 80% of the total Coin-Margined trading volume. Weekend trading volume tended to be relatively low in comparison. Apart from Bitcoin and Ethereum, the most actively traded Coin-Margined pairs included SOL, LTC, LINK, and BNB.
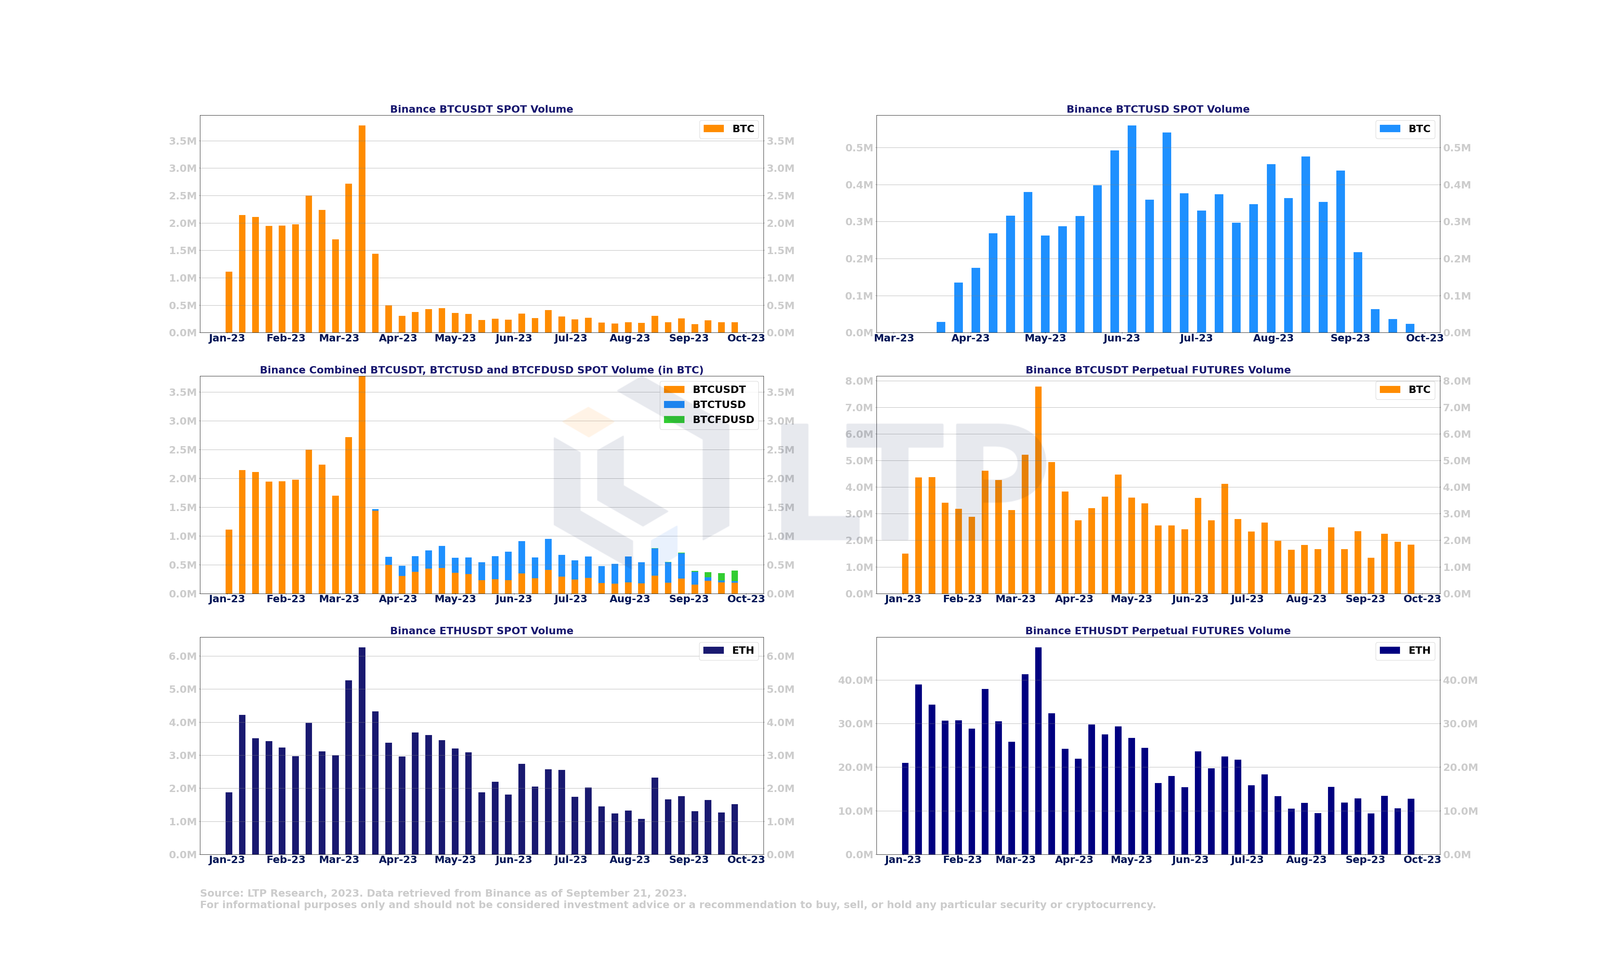
In September, Bitcoin SPOT trading volume on Binance reached a yearly low, falling short of the previous month's levels. Notably, there was a shift in trading activity from BTCTUSD to BTCFDUSD, as depicted in the chart, with BTCTUSD experiencing a significant decline in volume while BTCFDUSD saw a corresponding increase. Meanwhile, the volume of Bitcoin and Ethereum Perpetual Futures remained relatively stable, albeit with a slight downward trend.
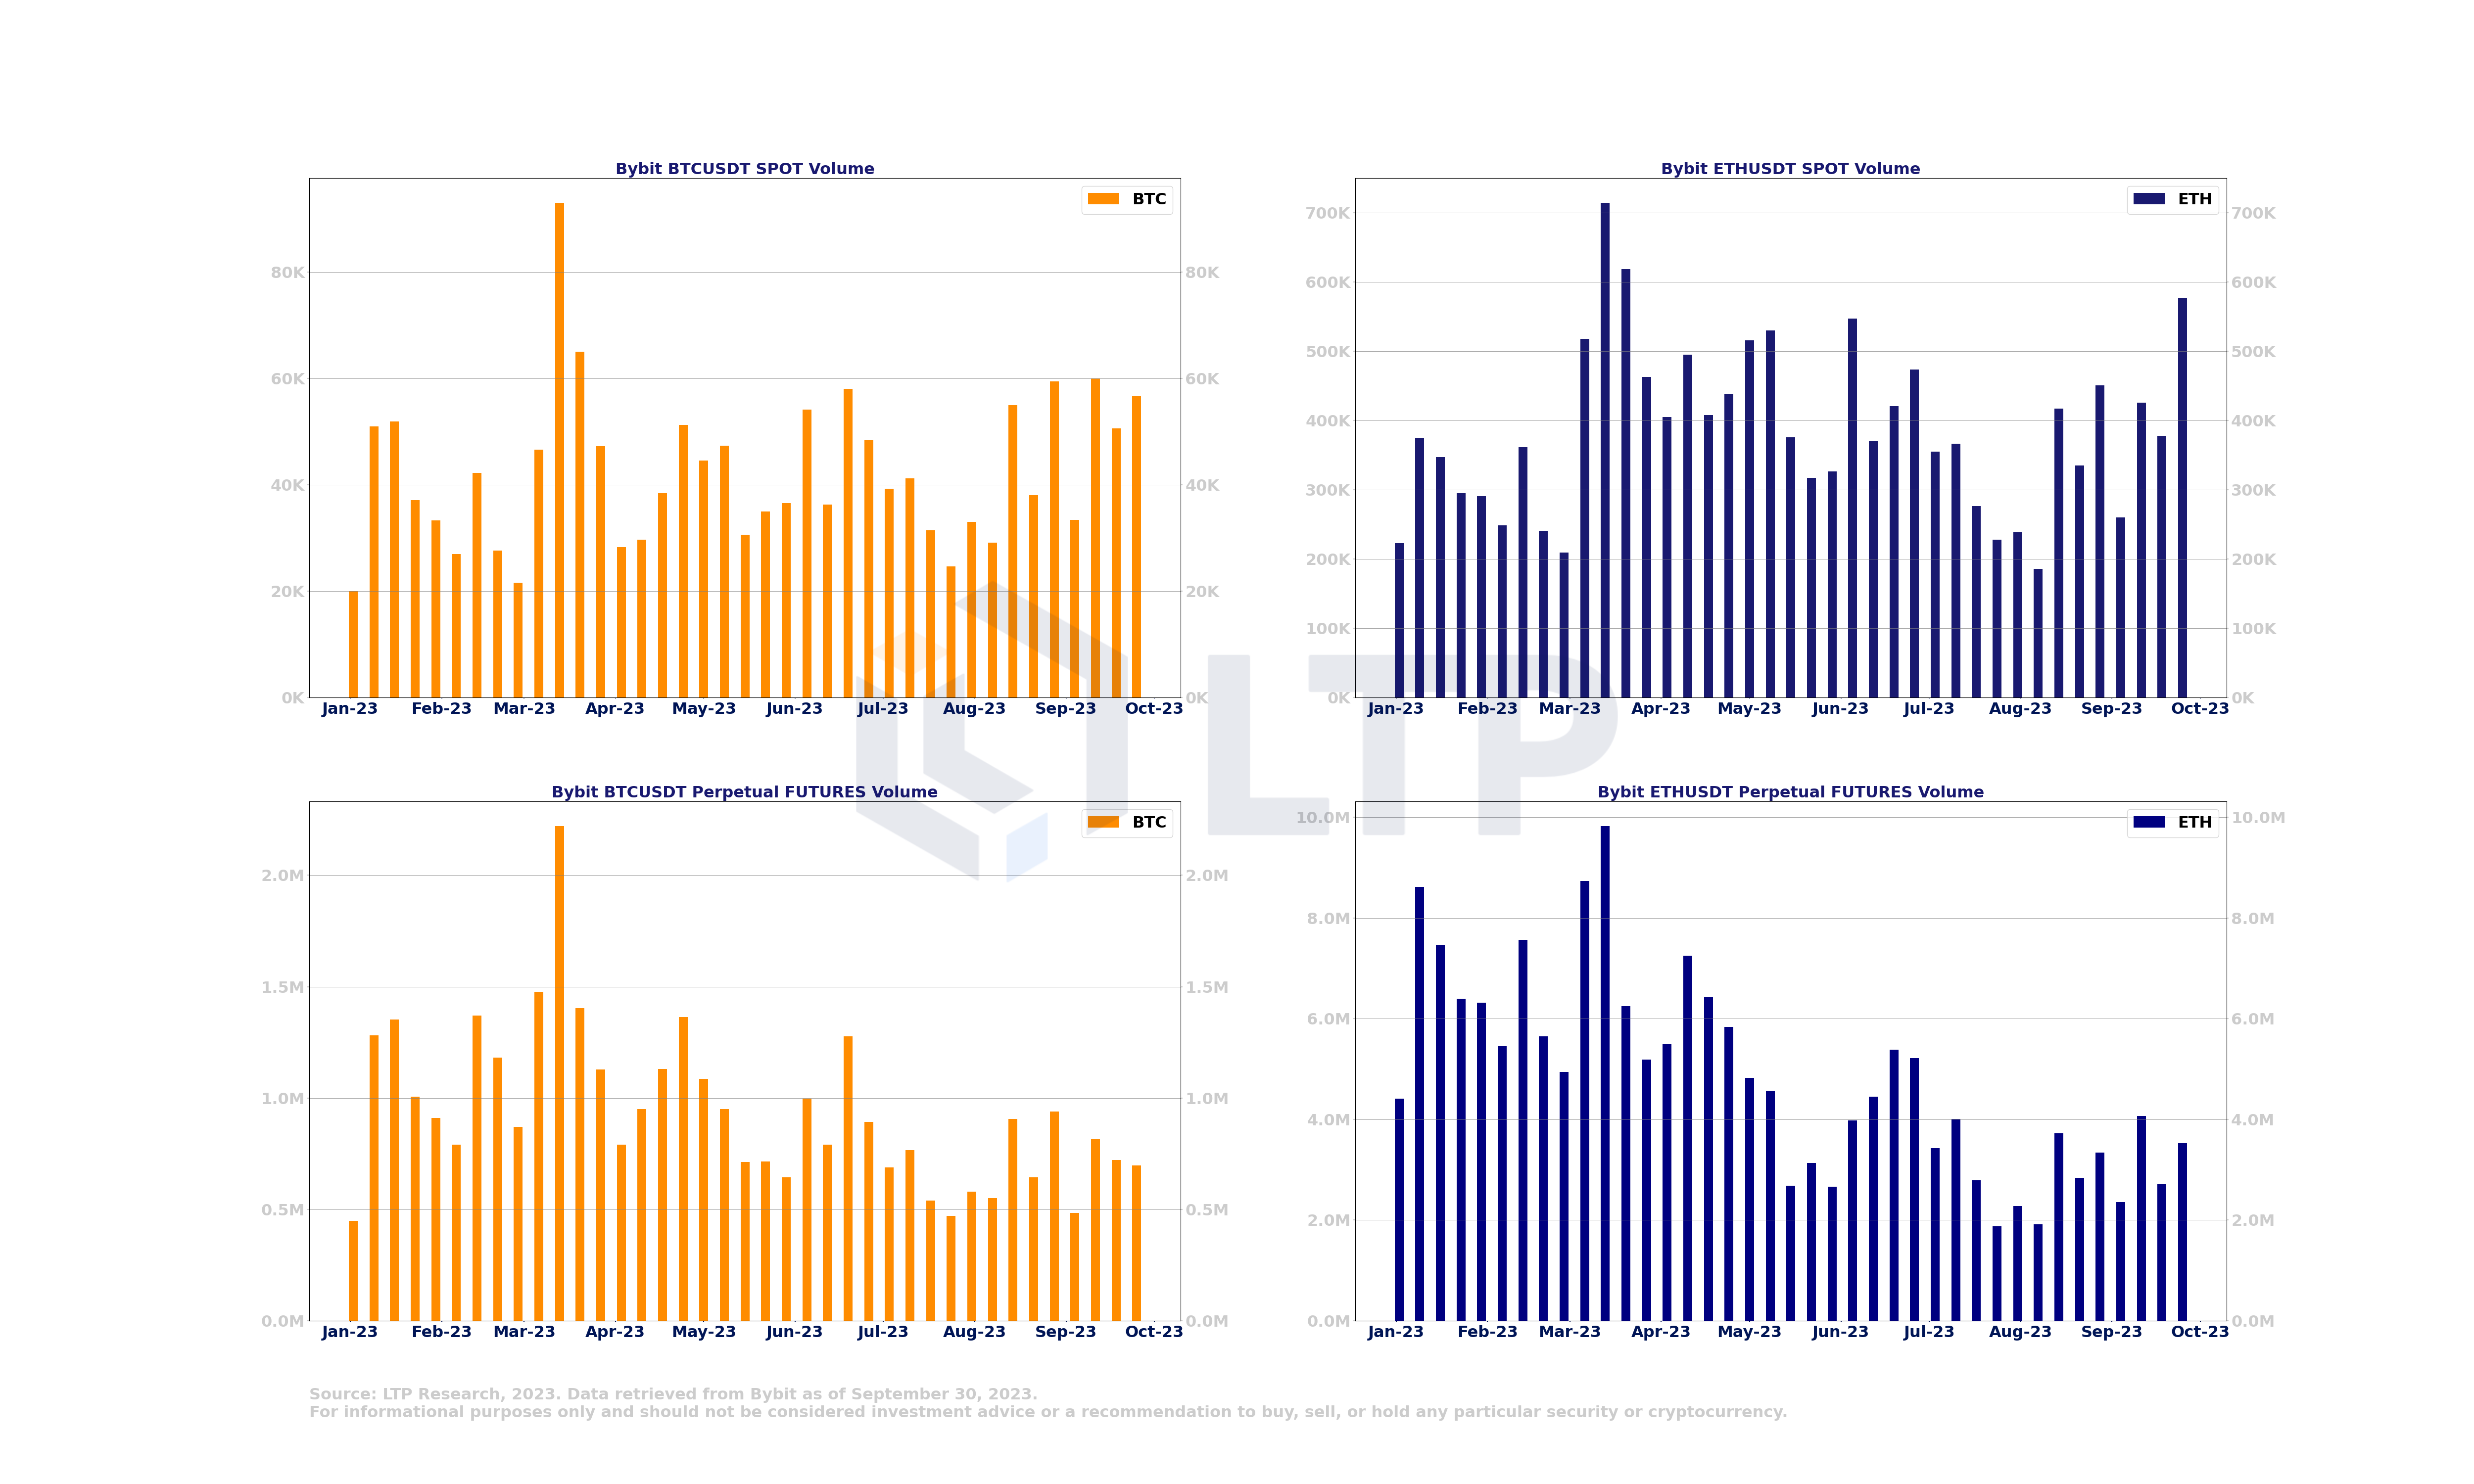
In September, Bybit observed an uptick in trading volume for the Bitcoin and Ethereum spot markets. However, the trading volume for Bitcoin and Ethereum perpetual futures remained relatively stable compared to August.
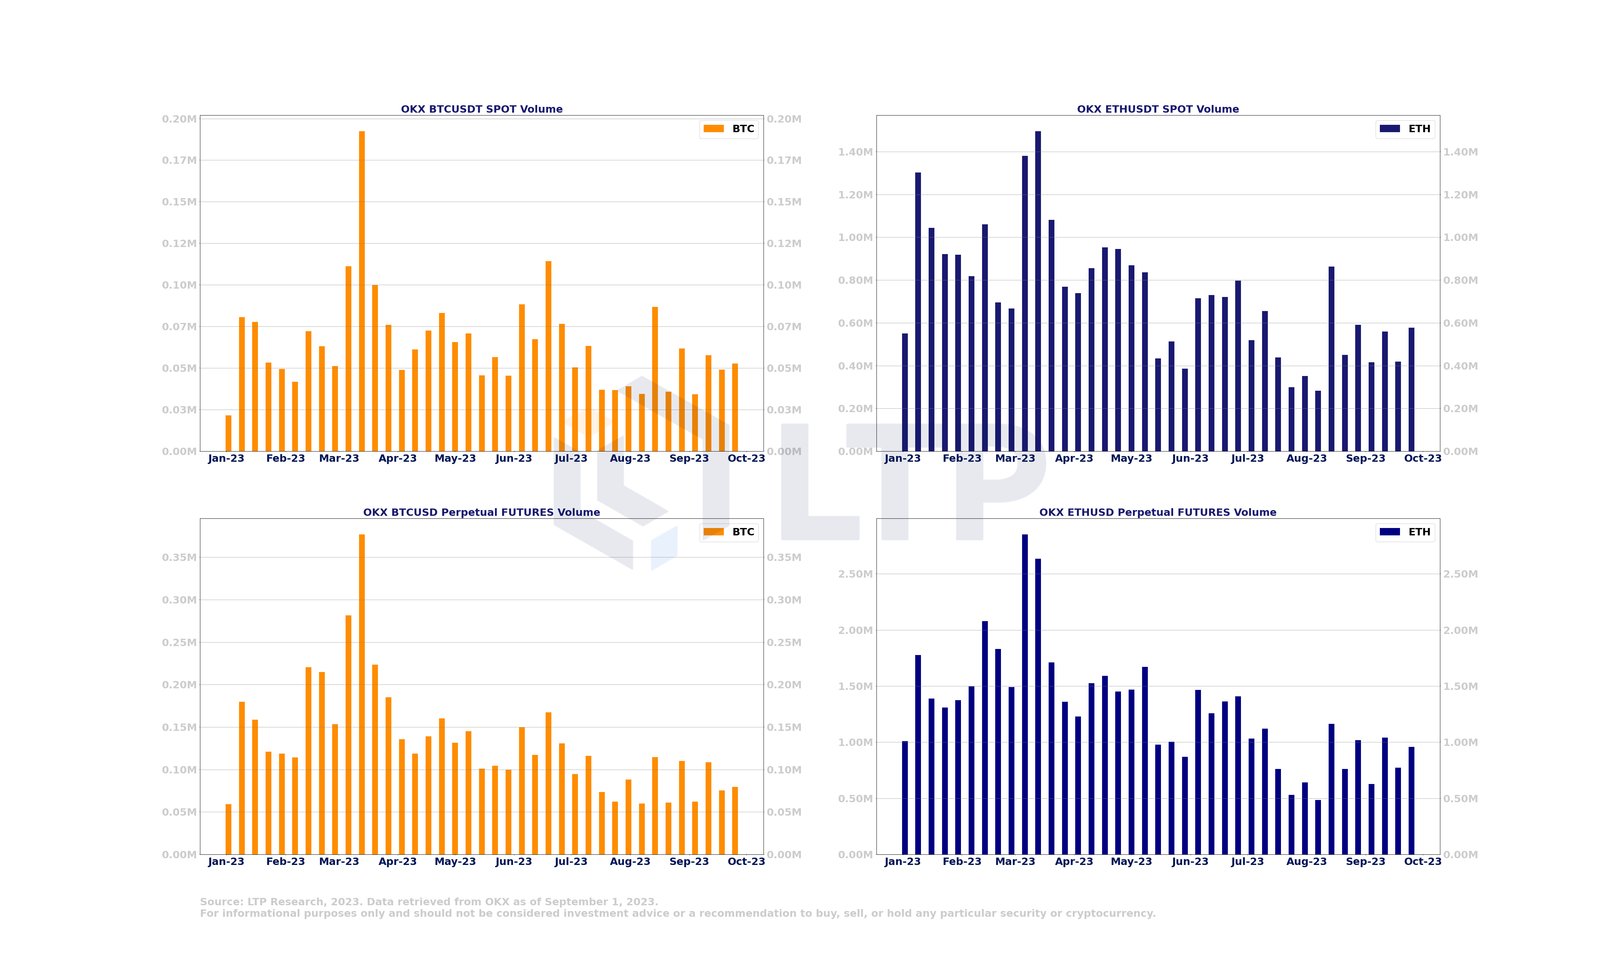
In September, OKX experienced increased trading volume in the Bitcoin and Ethereum spot markets. Additionally, the trading volume for Bitcoin and Ethereum perpetual futures markets recorded a slight increase compared to August.
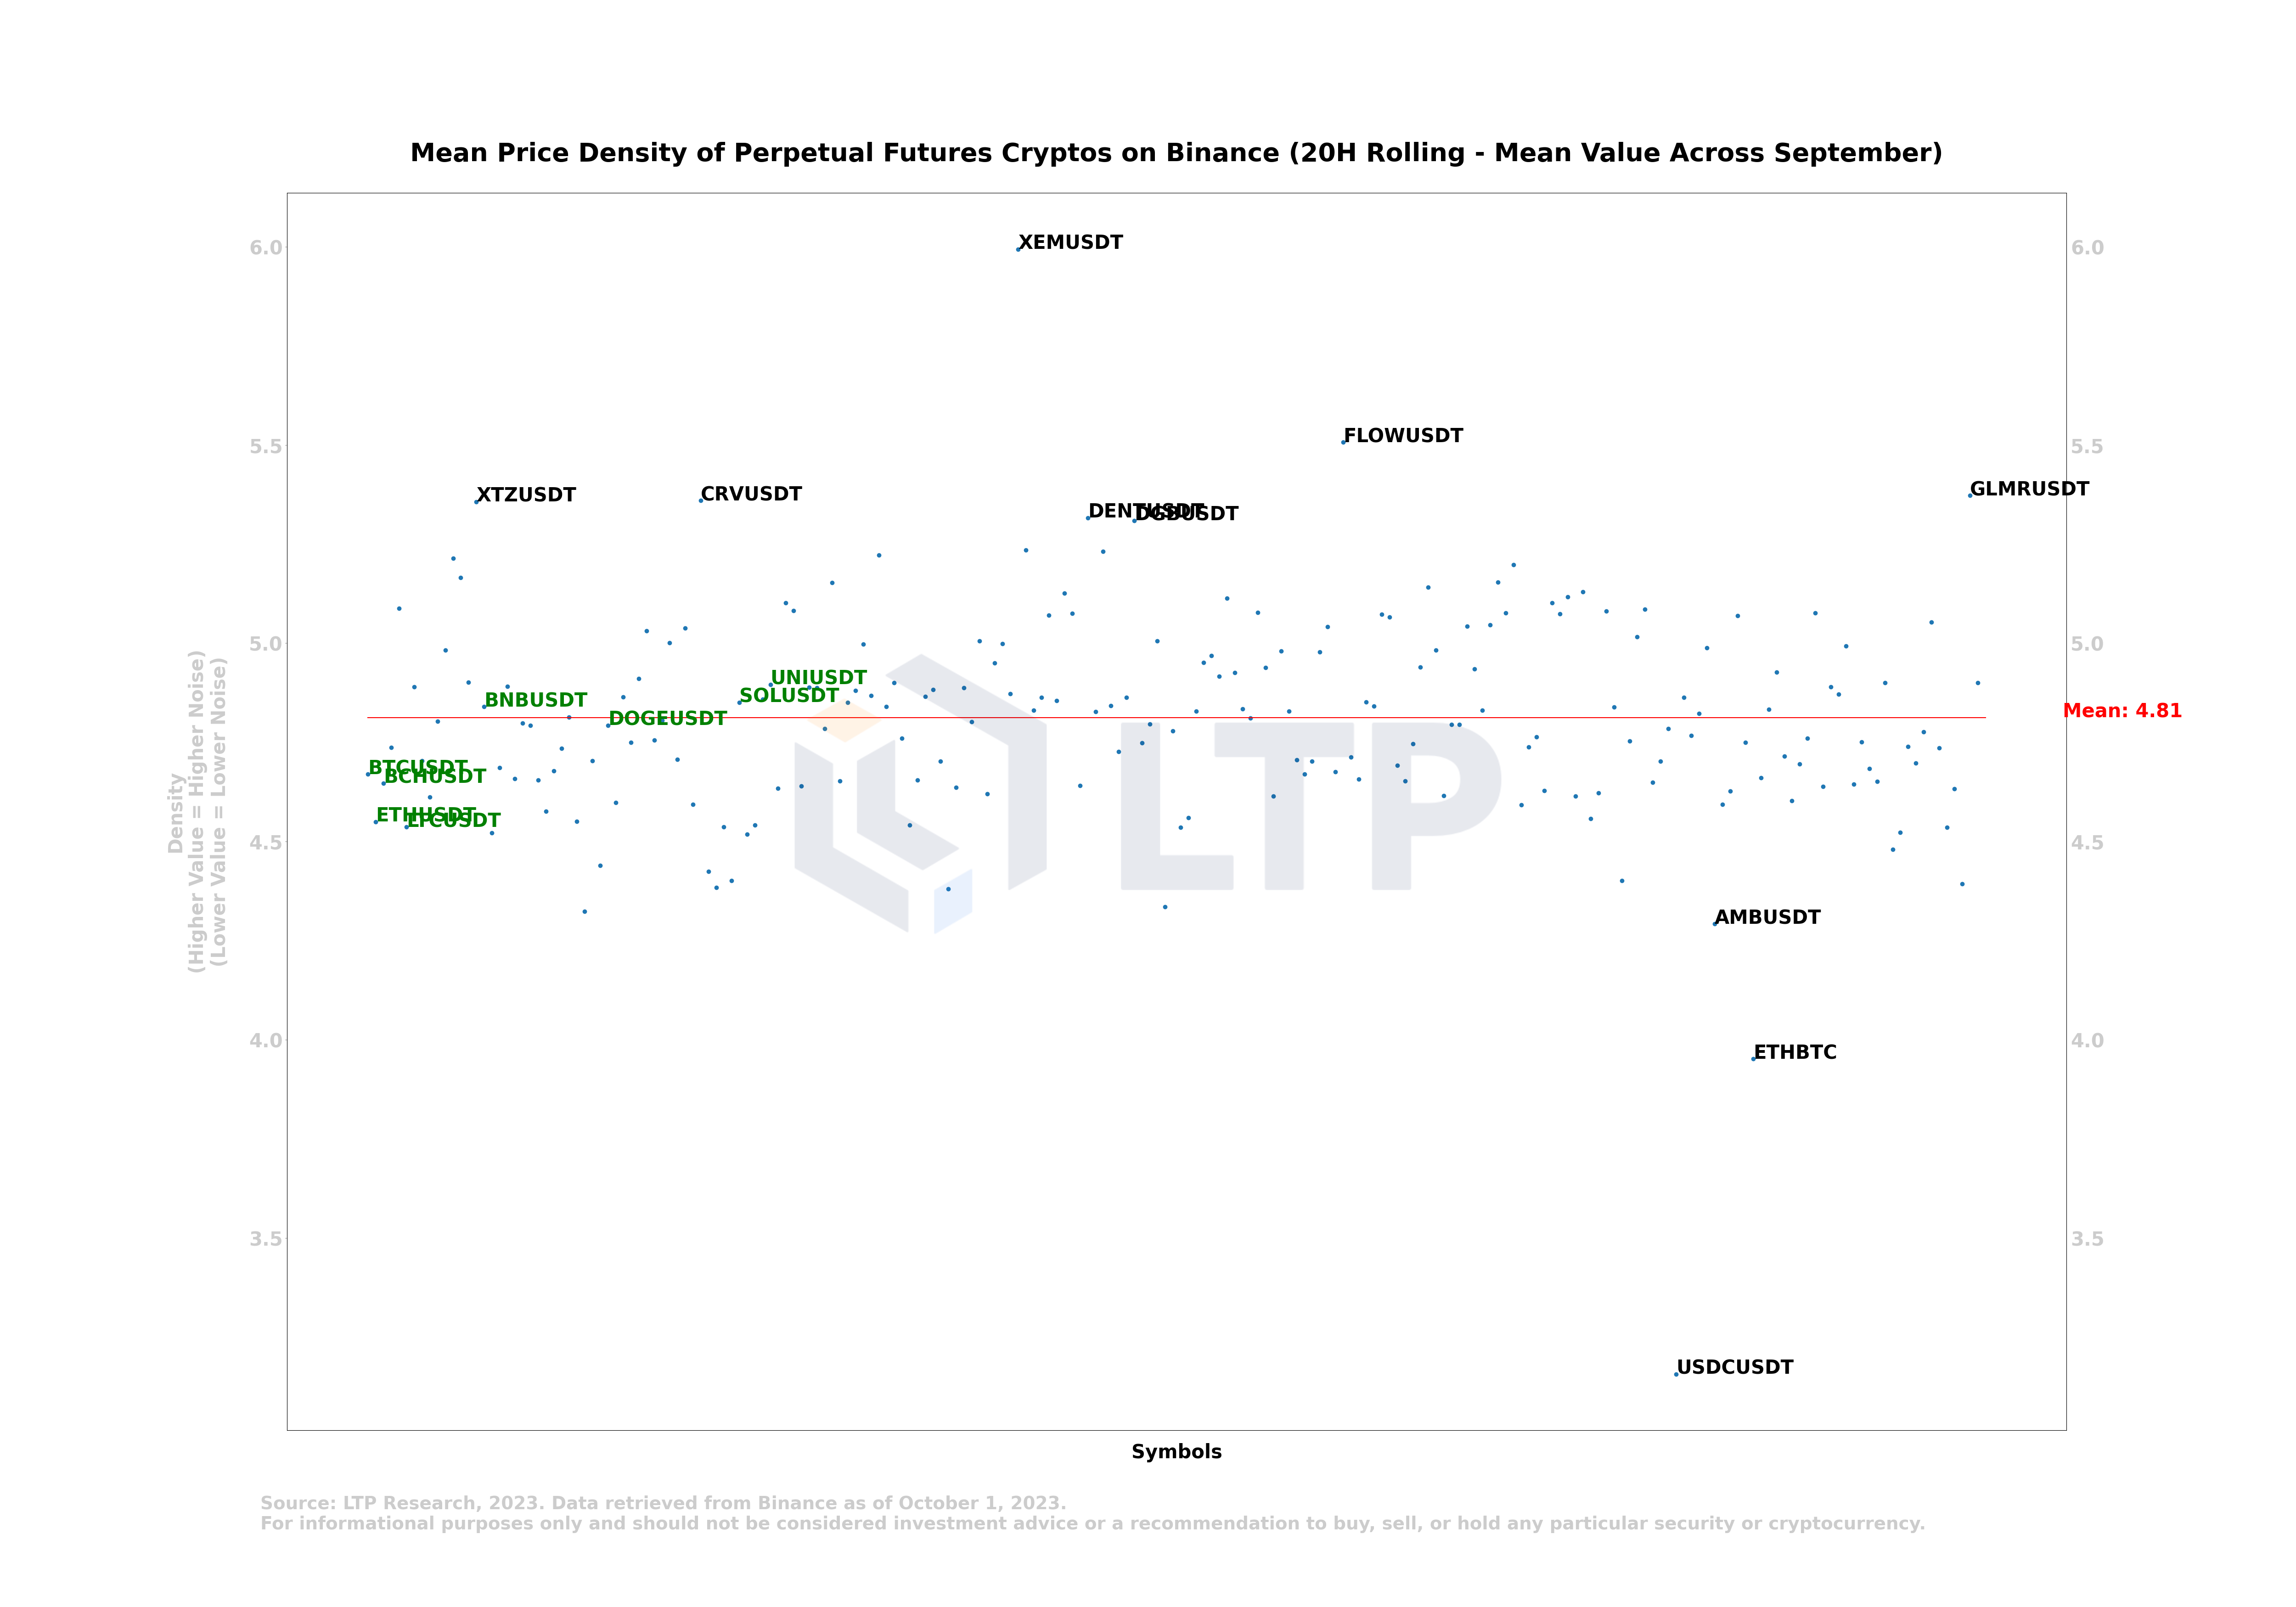
In September, XEMUSDT had the highest Price Density value, approaching nearly 6. On the other hand, AMBUSDT and ETHBTC had the lowest Price Density values, measuring at 4.3 and 4, respectively. These measurements indicate that XEMUSDT displayed more turbulent and erratic price behavior, while AMBUSDT and ETHBTC exhibited smoother trend characteristics.It is important to note that the measurements mentioned were conducted using a 20-hour rolling method. Different timeframes can indeed yield different results when analyzing Price Density. The choice of timeframe can influence the perceived choppiness or trend characteristics of a particular asset.
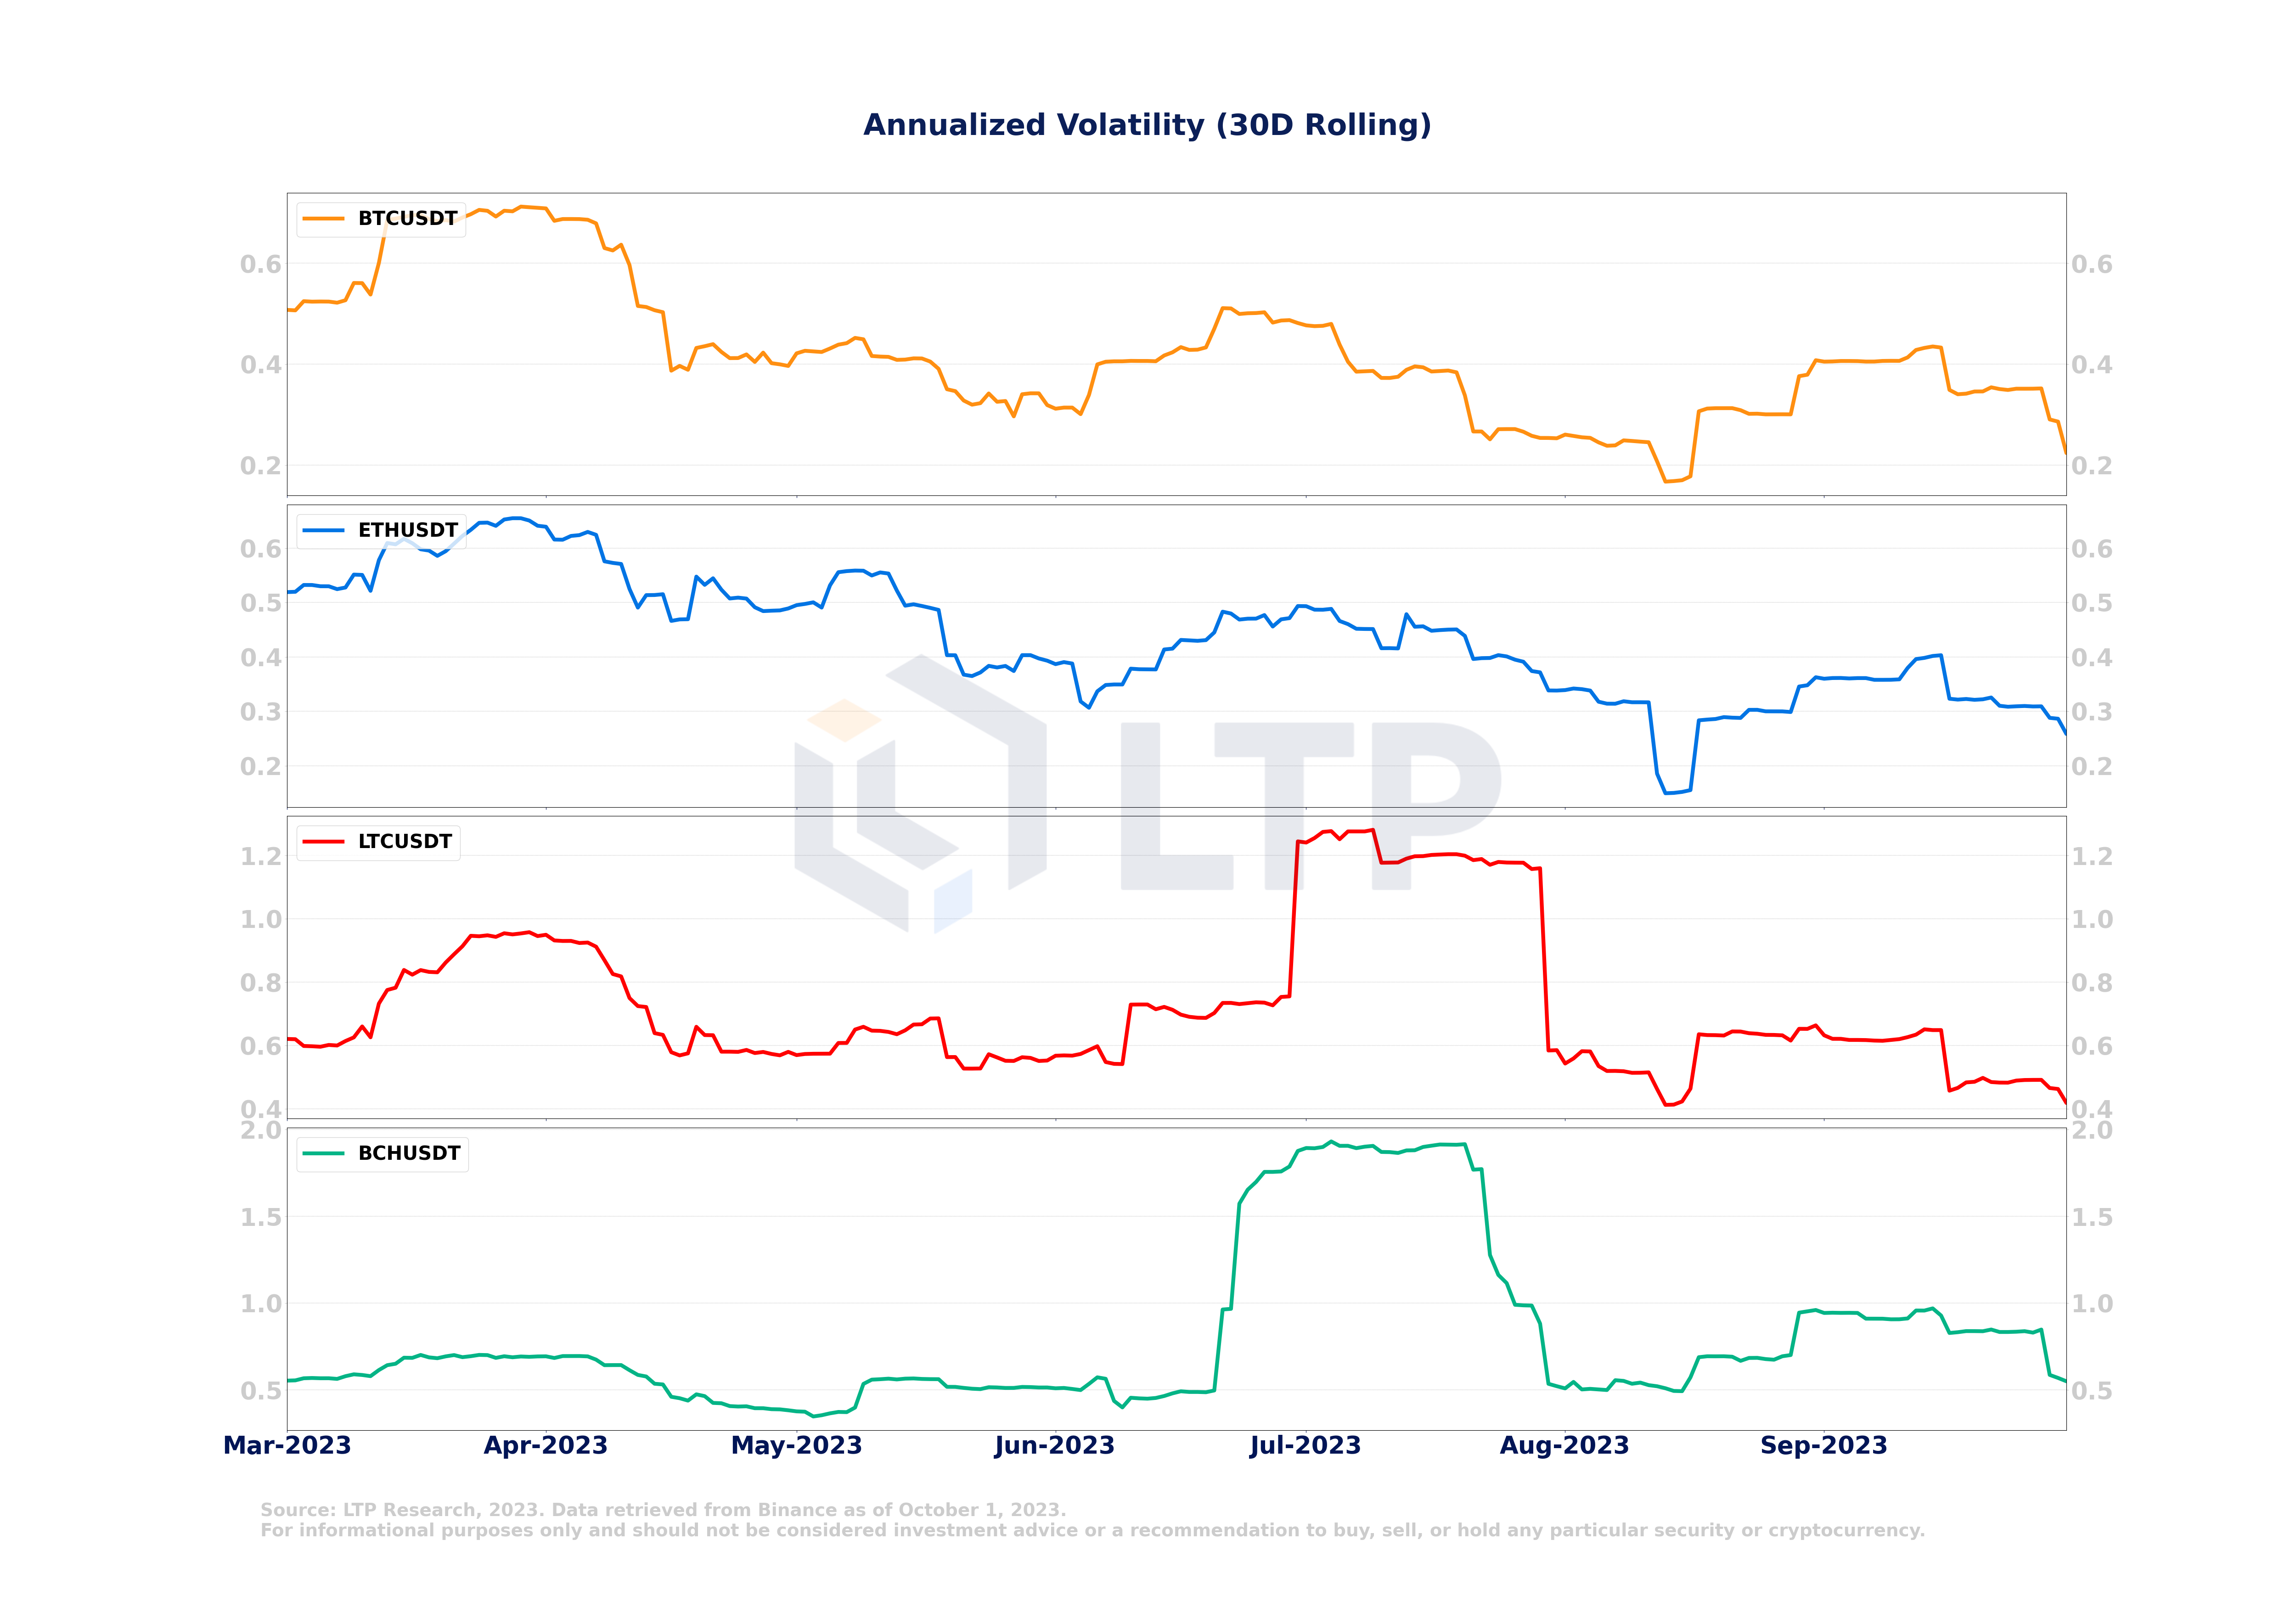
In September, there was a decrease in the Annualized Volatility for major cryptocurrencies, including Bitcoin, Ethereum, Litecoin, and Bitcoin Cash. Specifically, for Bitcoin, the Annualized Volatility reached 0.18 in early August, then experienced a significant increase to 0.42 in early September. However, it gradually declined and fell steadily as the month progressed, indicating a decrease in volatility towards the end of September.
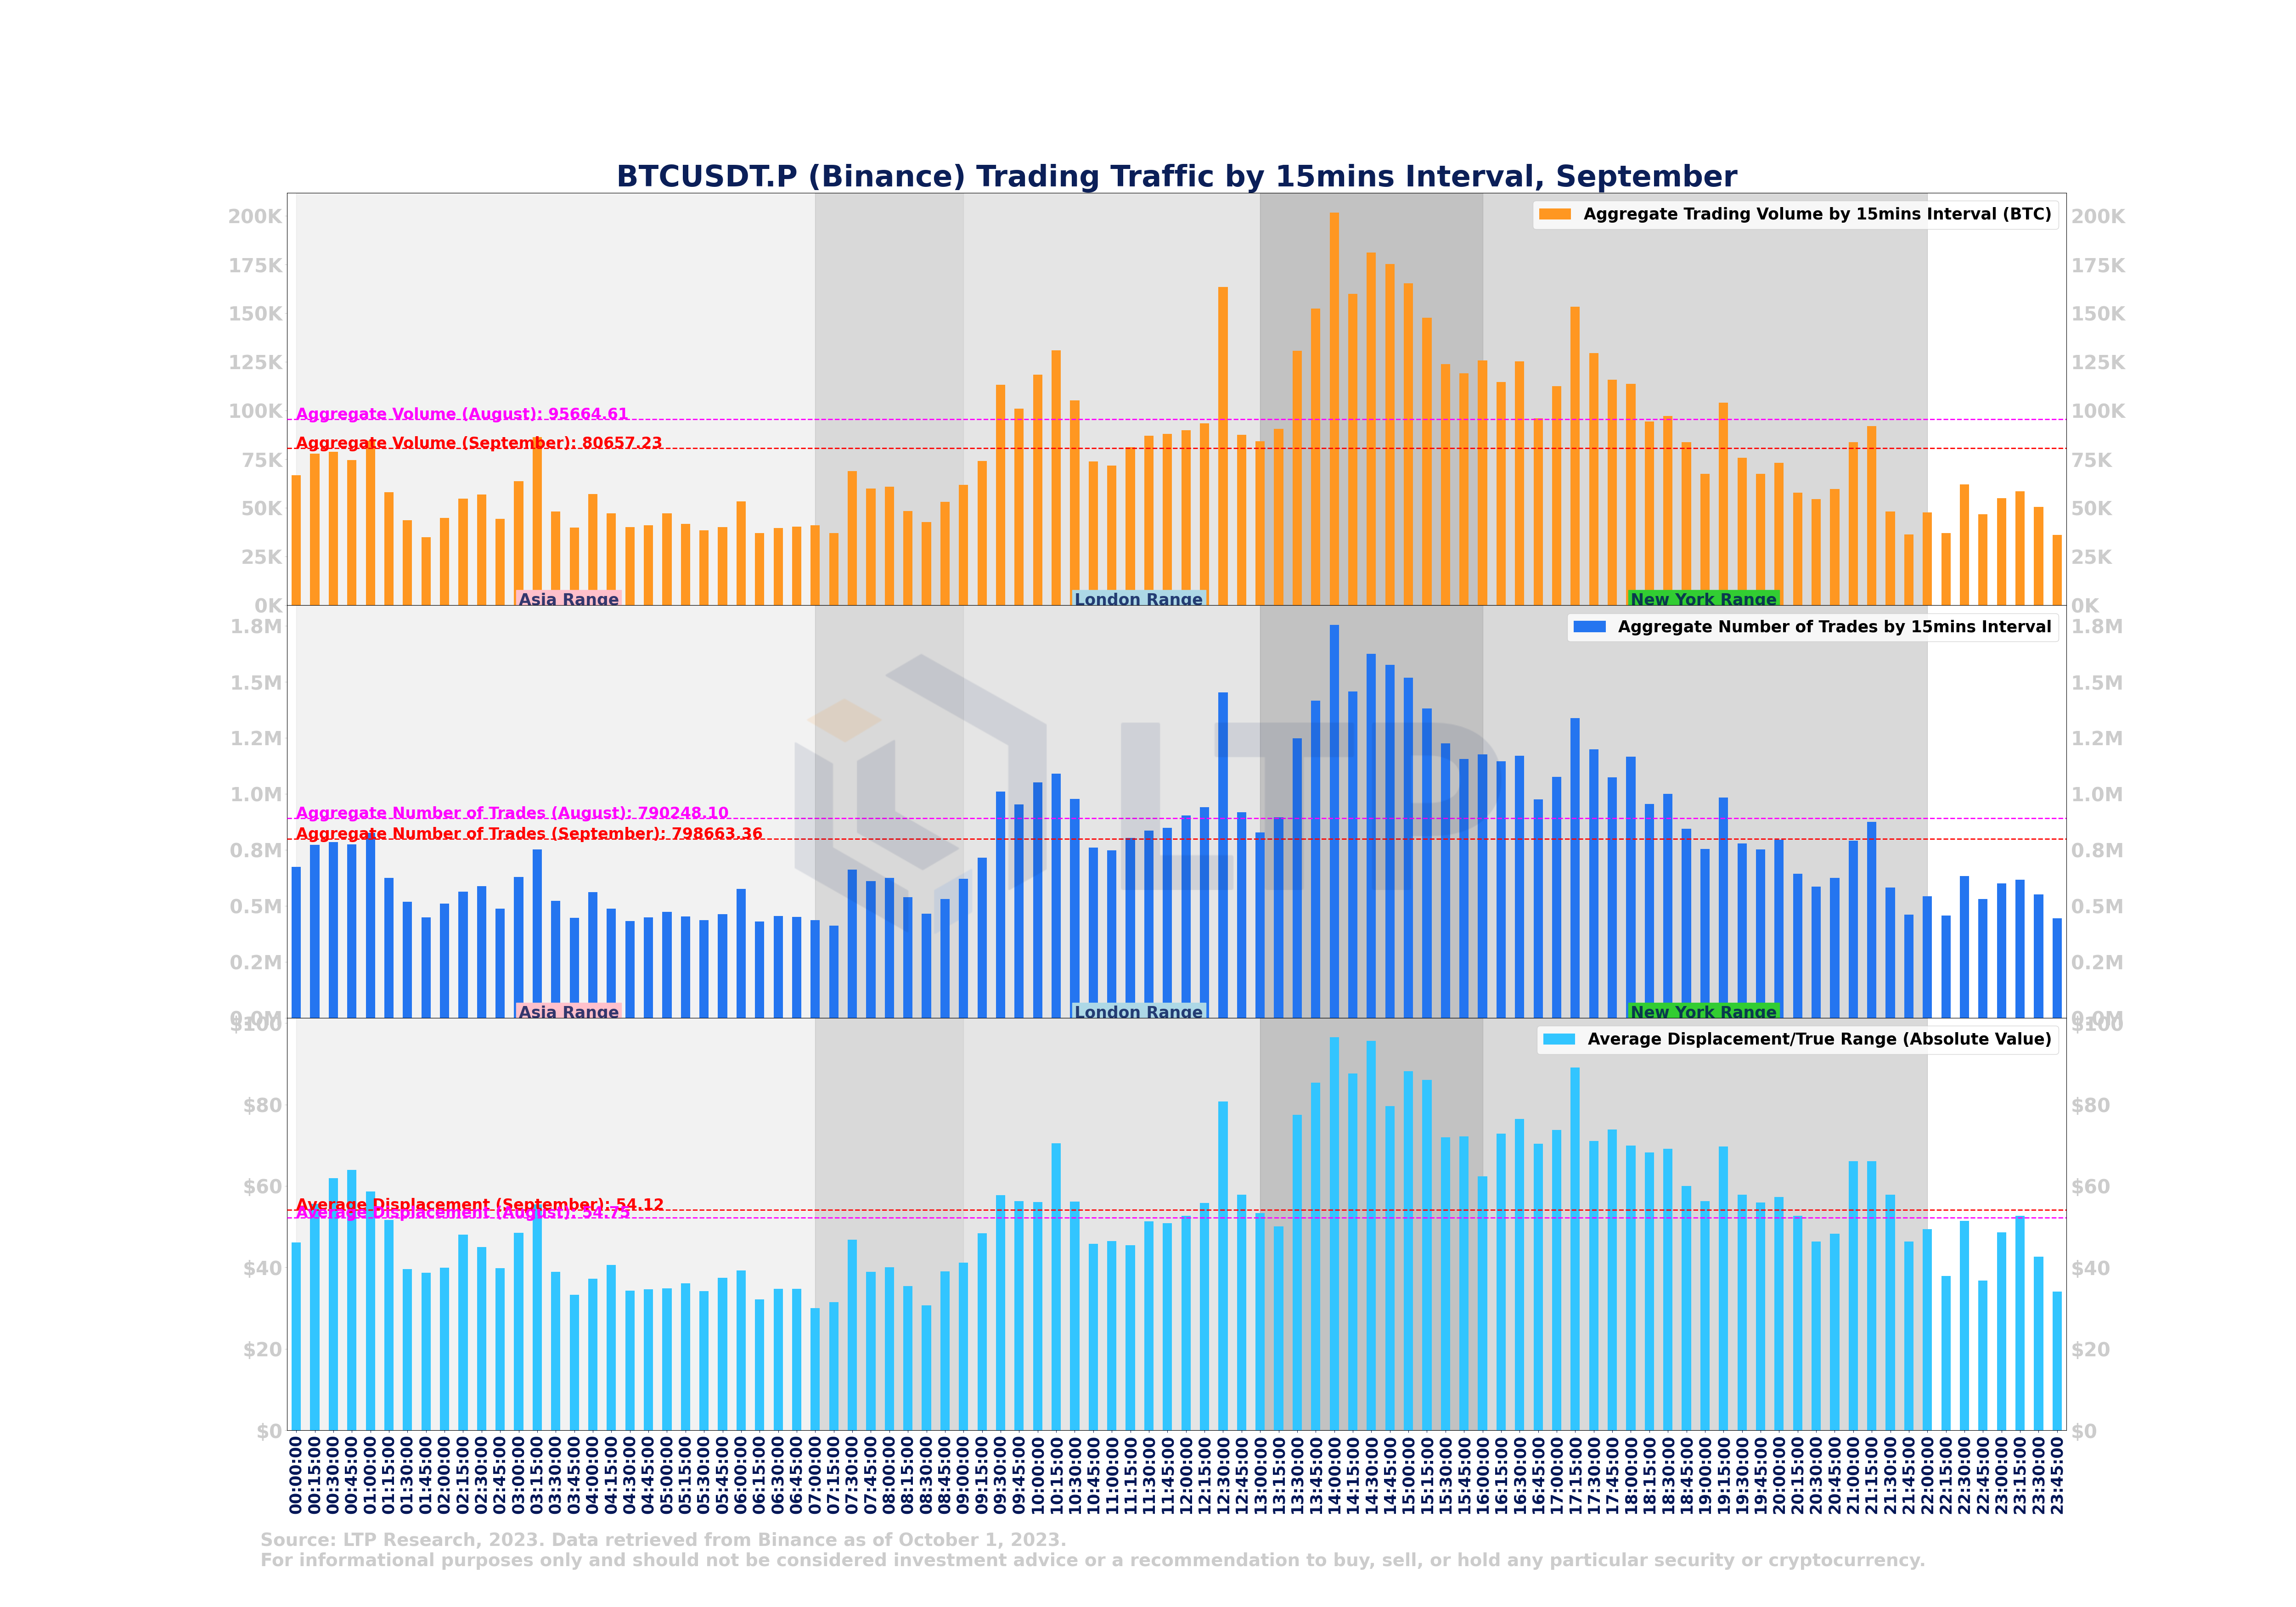
During the period when the New York Trading Session overlaps with the London Trading Session (13:00 - 16:00 UTC), there was an observed increase in trading activities with BTCUSDT.P on Binance.
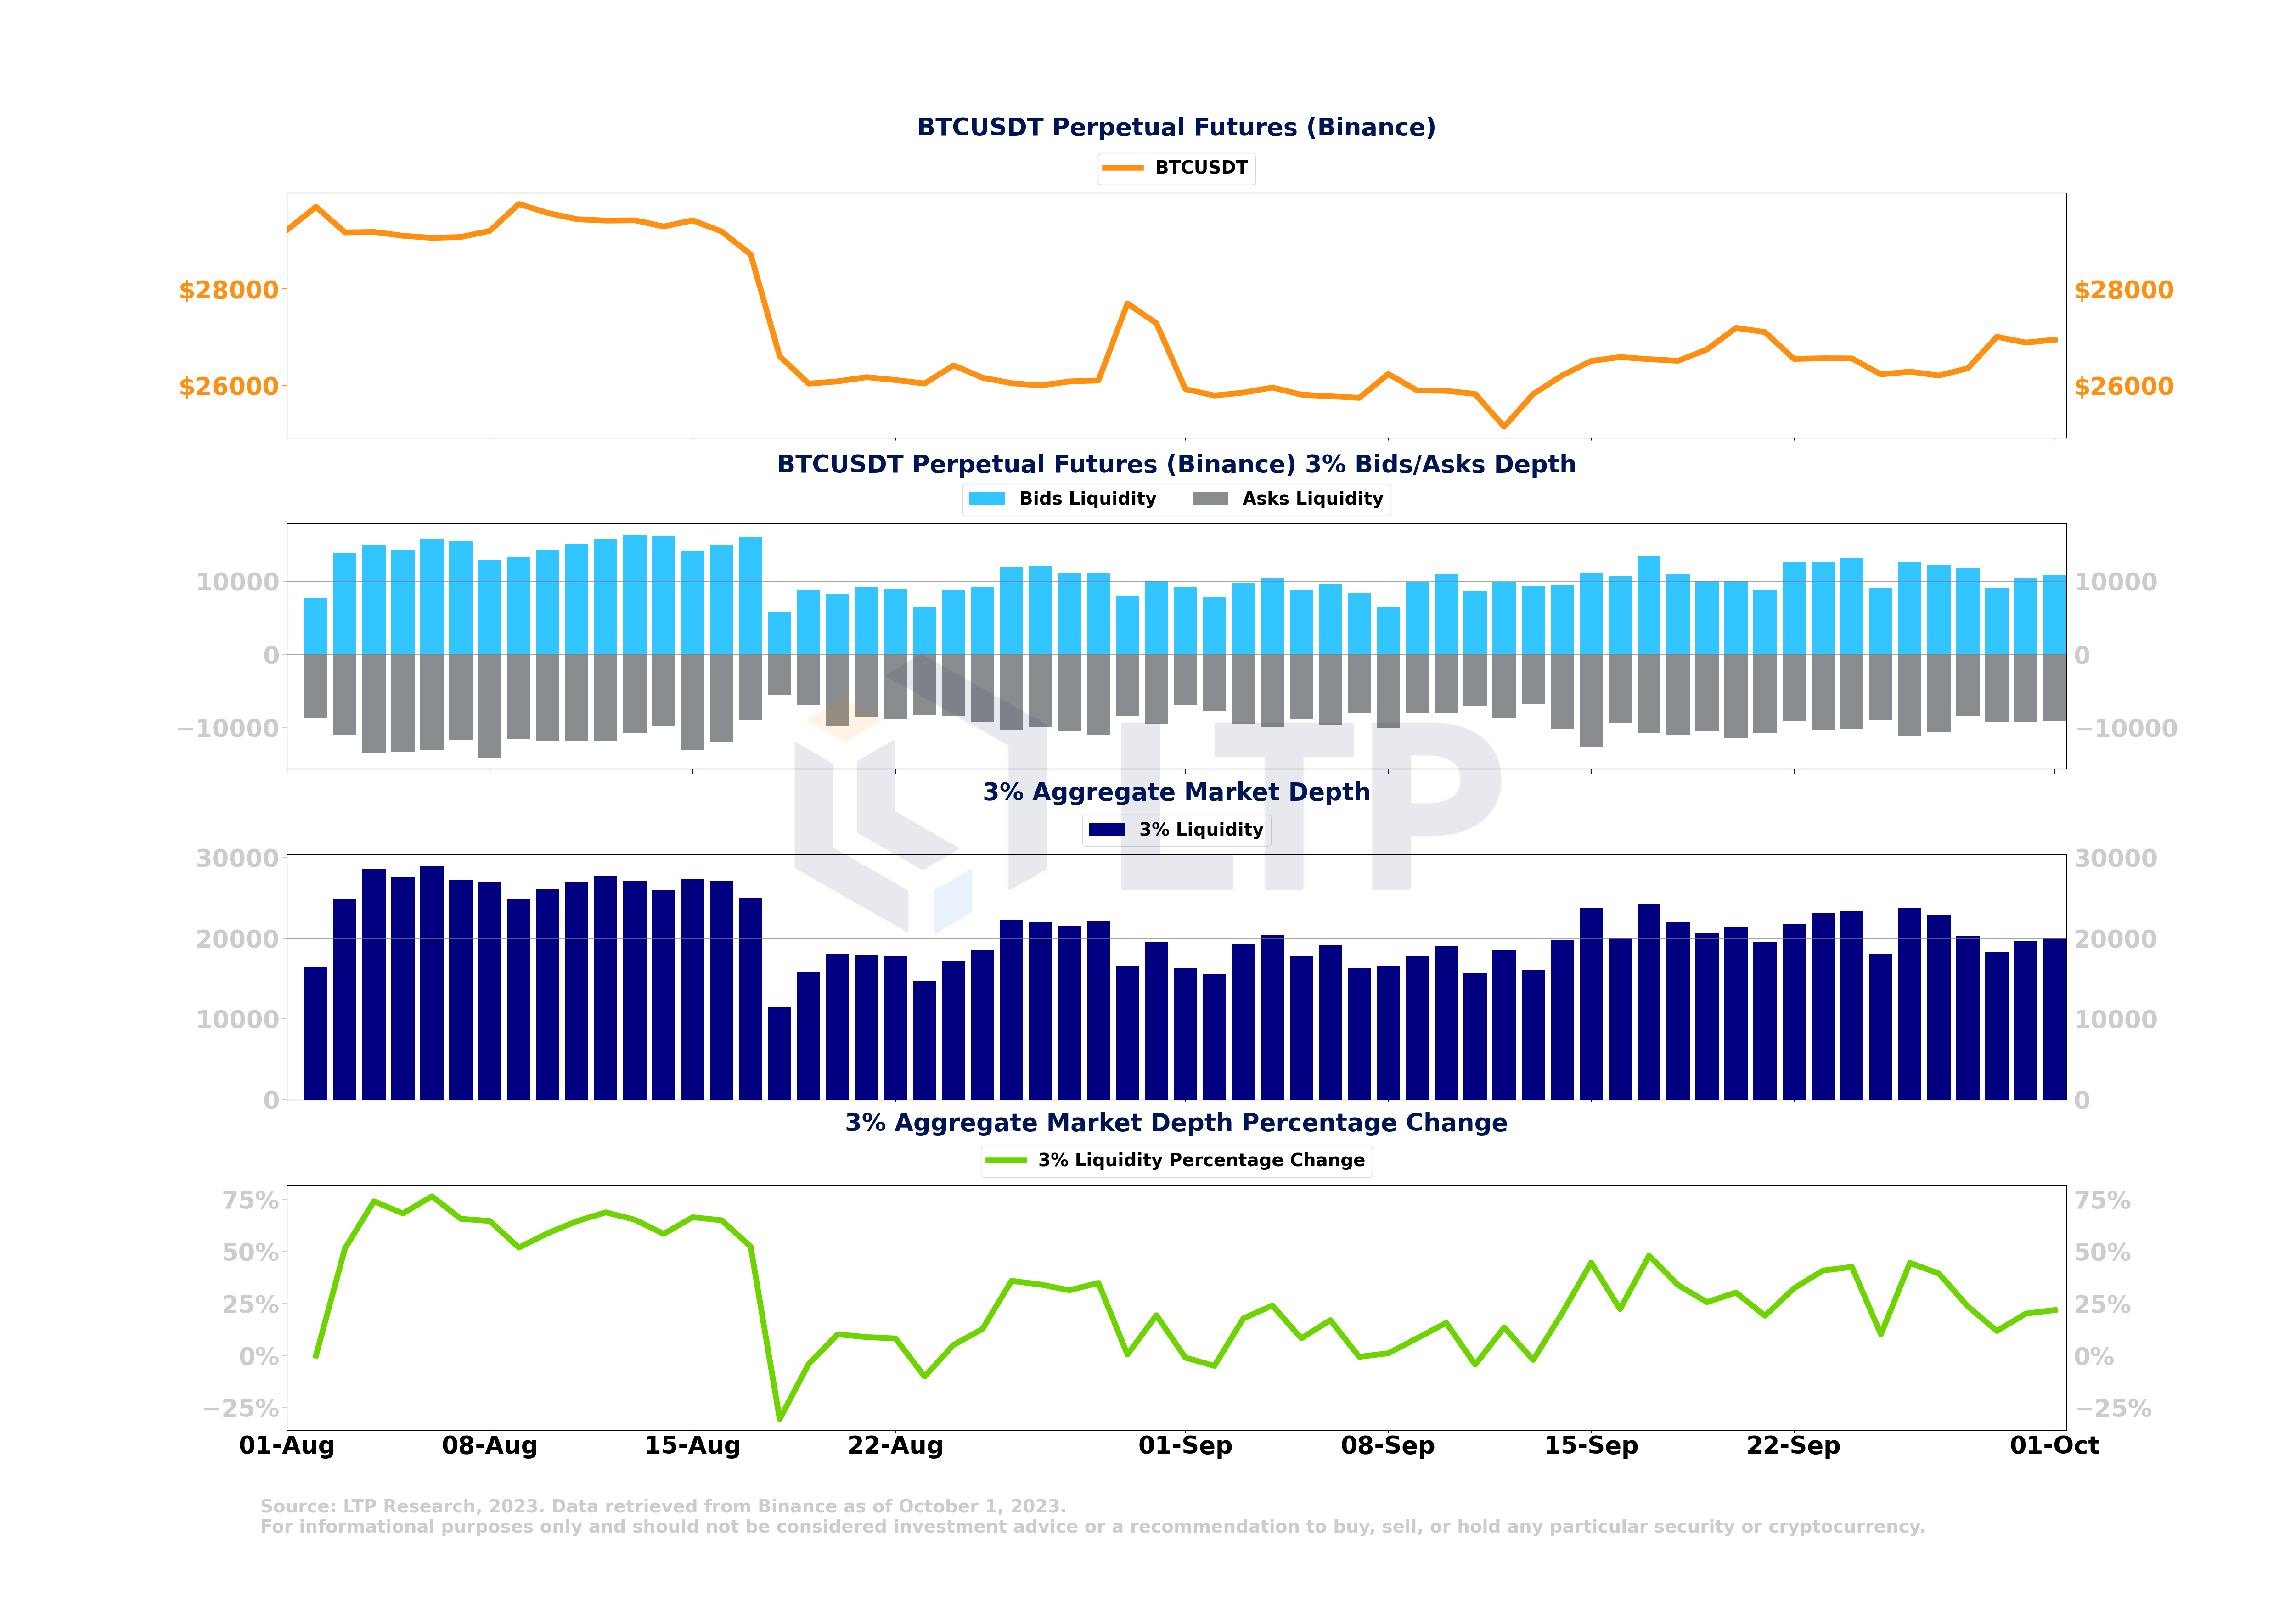
Market Depth on BTCUSDT.P (Binance) experienced a drop during the sell-off that occurred on August 16th, 2023. However, since then, liquidity has been gradually recovering.
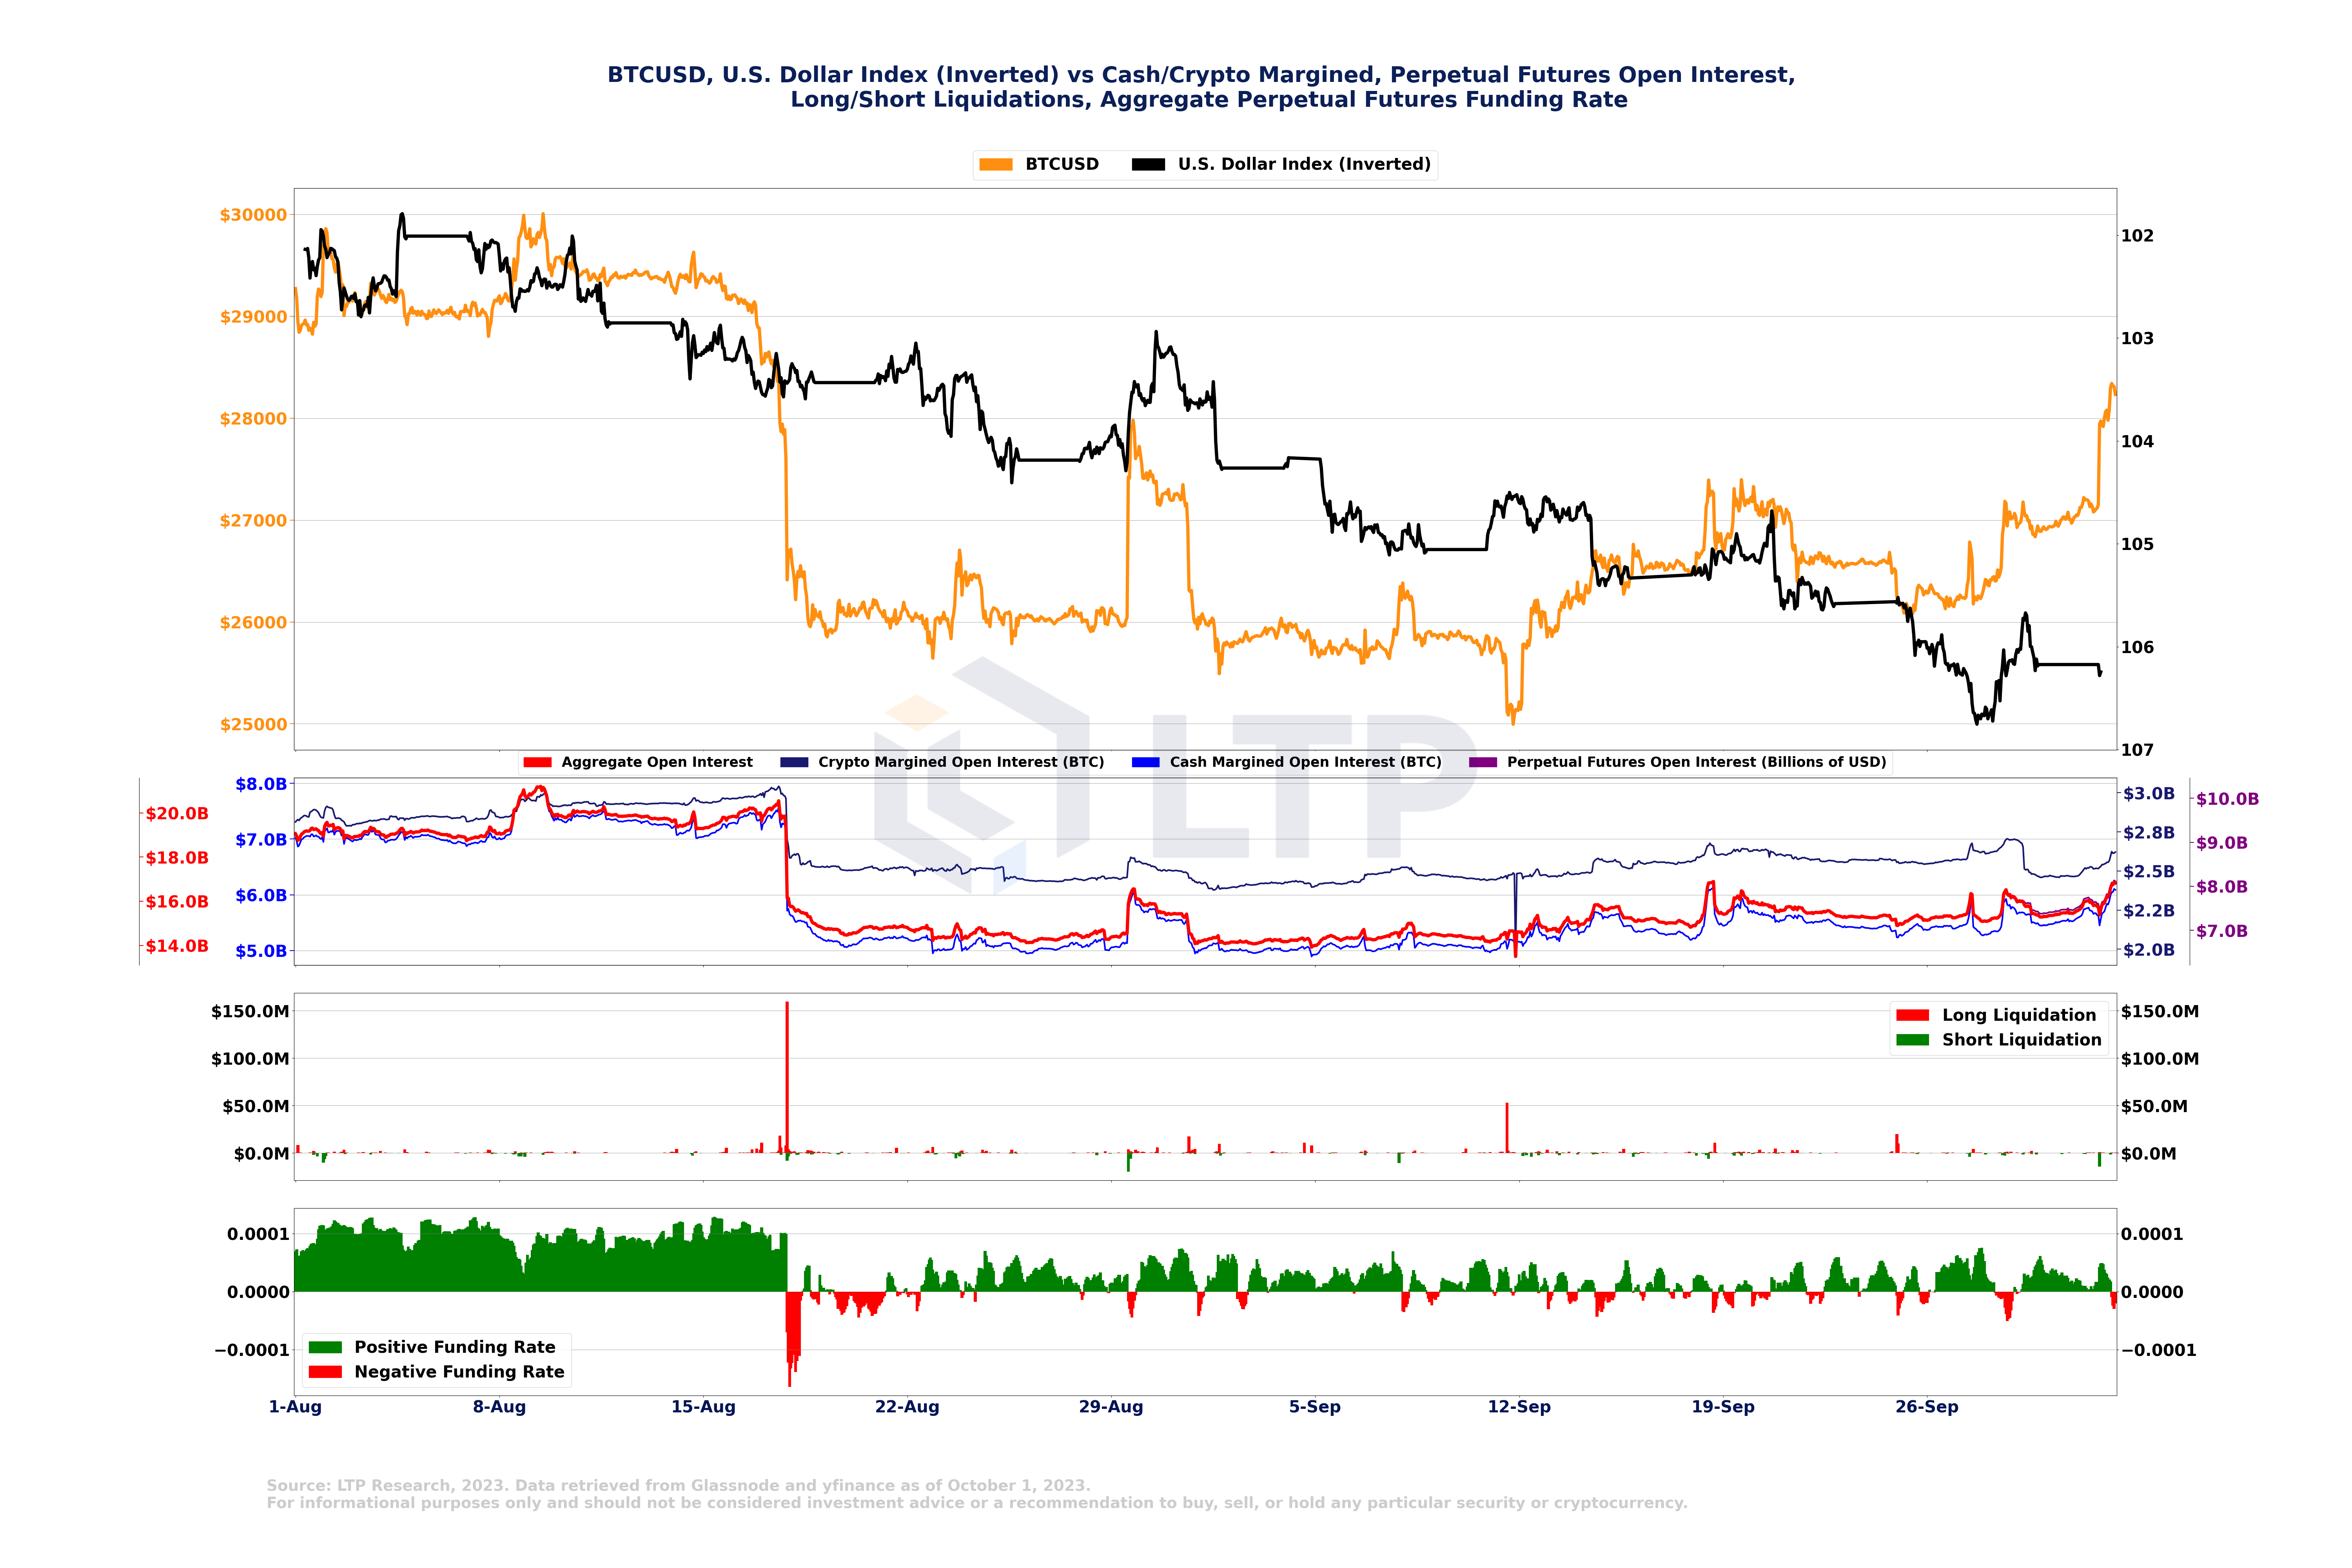
After the last liquidation event on August 16th, 2023, the aggregate open interest for Bitcoin remained subdued, recording $16B USD. Furthermore, on September 11th, there was a specific stop hunt that occurred, resulting in the erasure of $0.4B worth of Crypto Margined Open Interest. The stop-hunt is visualized in section 2.16.
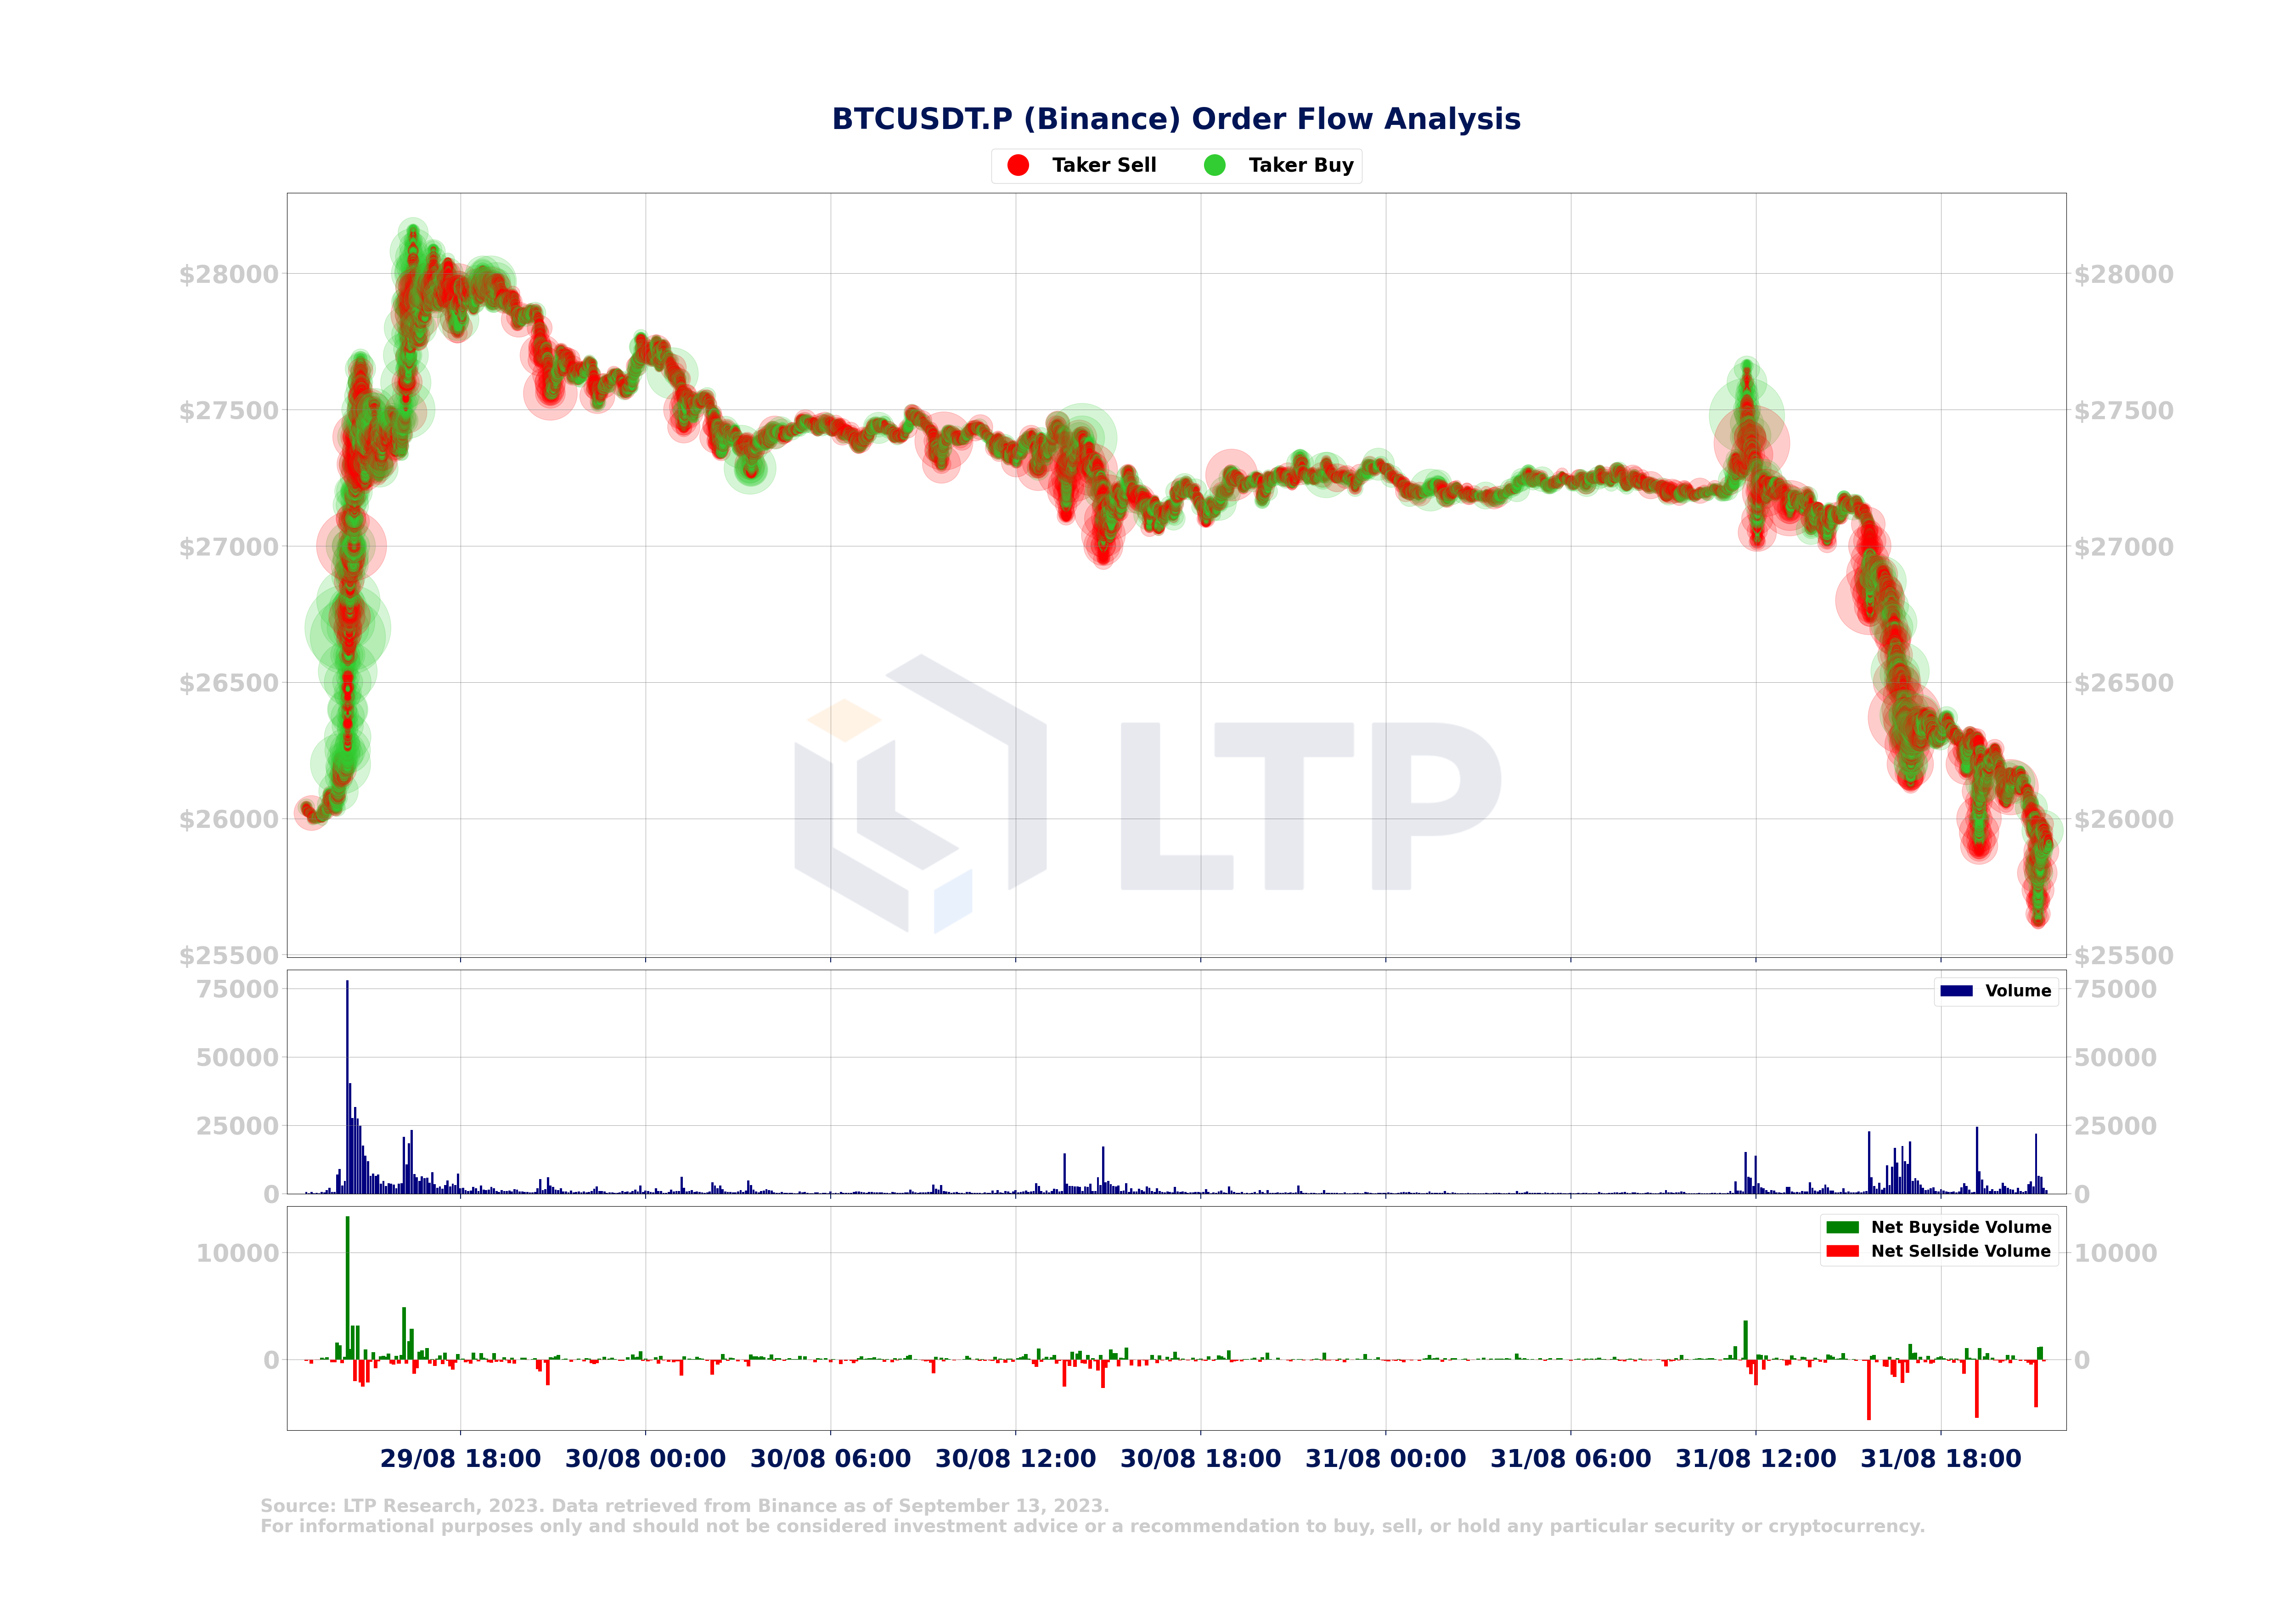
On August 29th, Bitcoin experienced a sudden price spike, resulting in a $2B increase in Aggregate Open Interest as traders pursued the upward movement. However, the pump was not sustained, as evidenced by a lack of trading volume immediately following the spike. Then, on August 31st, 2023, a selloff occurred, triggering a cascade of liquidation. Trading activities and volume remained subdued outside liquidations.
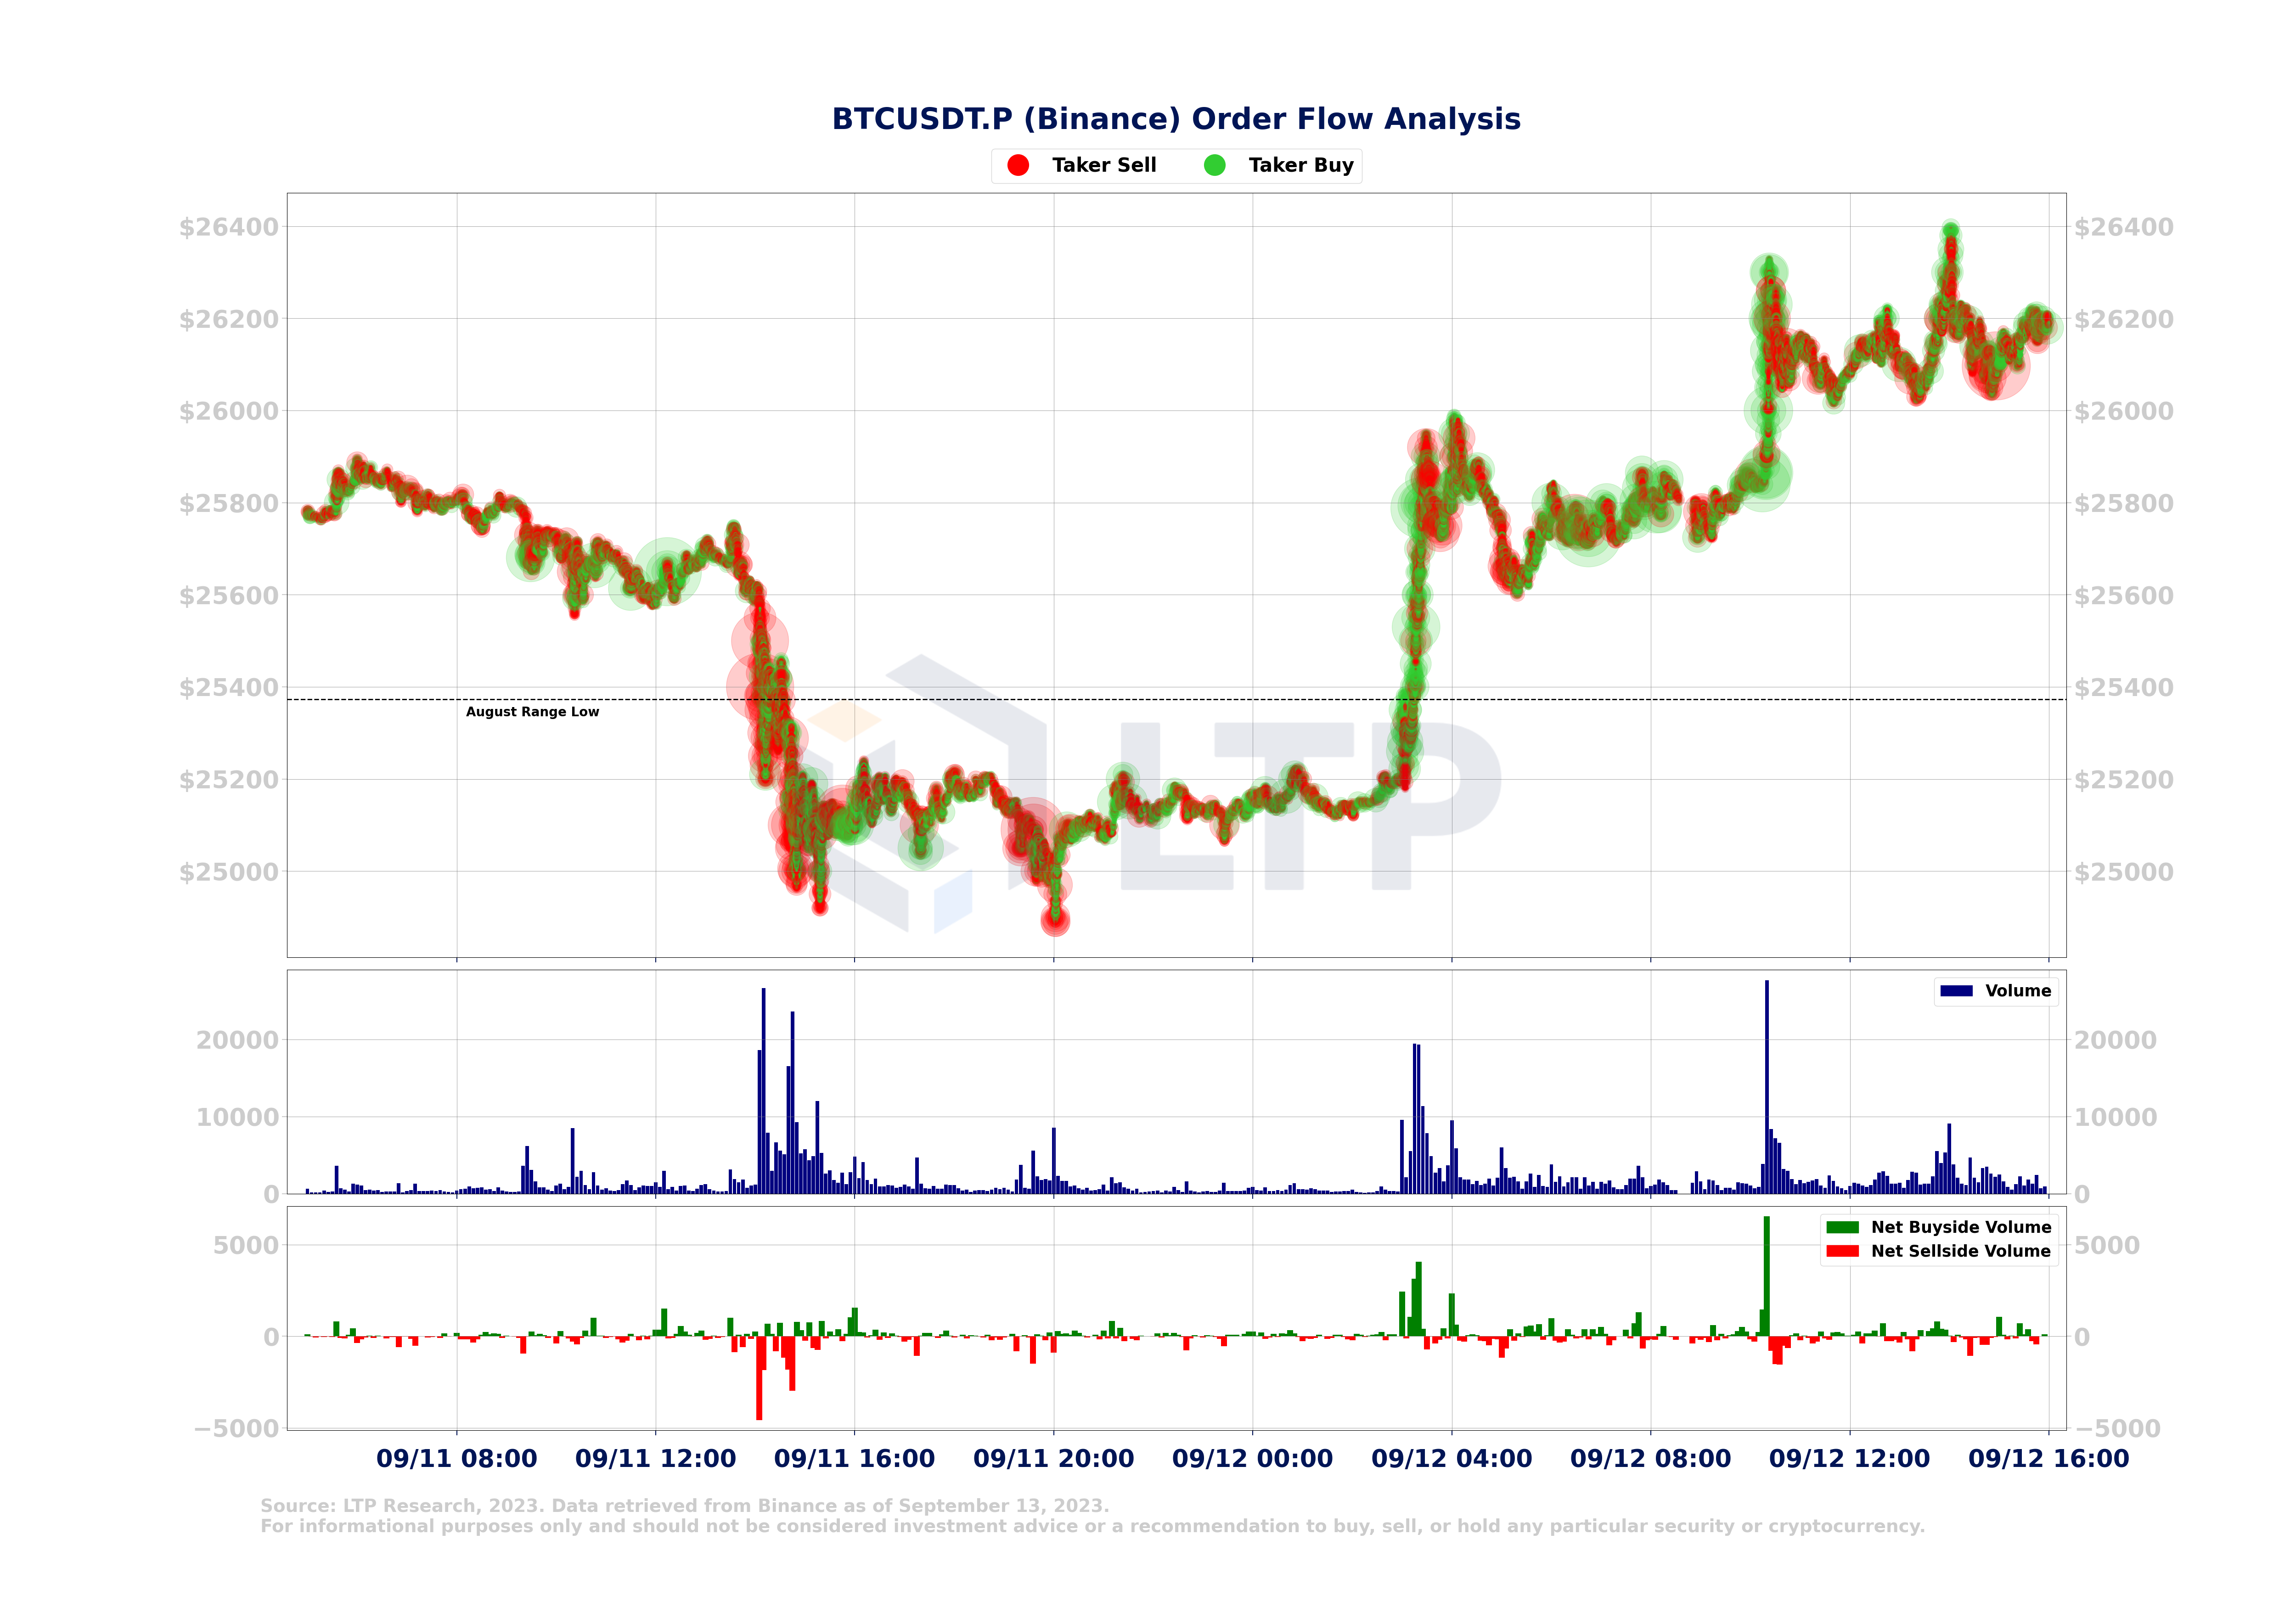
On September 11th, 2023, a specific stop hunt occurred, resulting in the elimination of $0.4B worth of Crypto Margined Open Interest. The chart indicates a cascade of taker sell orders that pushed the price below the range low of the entire August, where stop-loss orders were likely placed. The following day, after the taker sell orders were exhausted and the price dropped below the range low of August, aggressive taker buy orders entered the market and drove the price above $25, 800. This triggered a late short recovery.
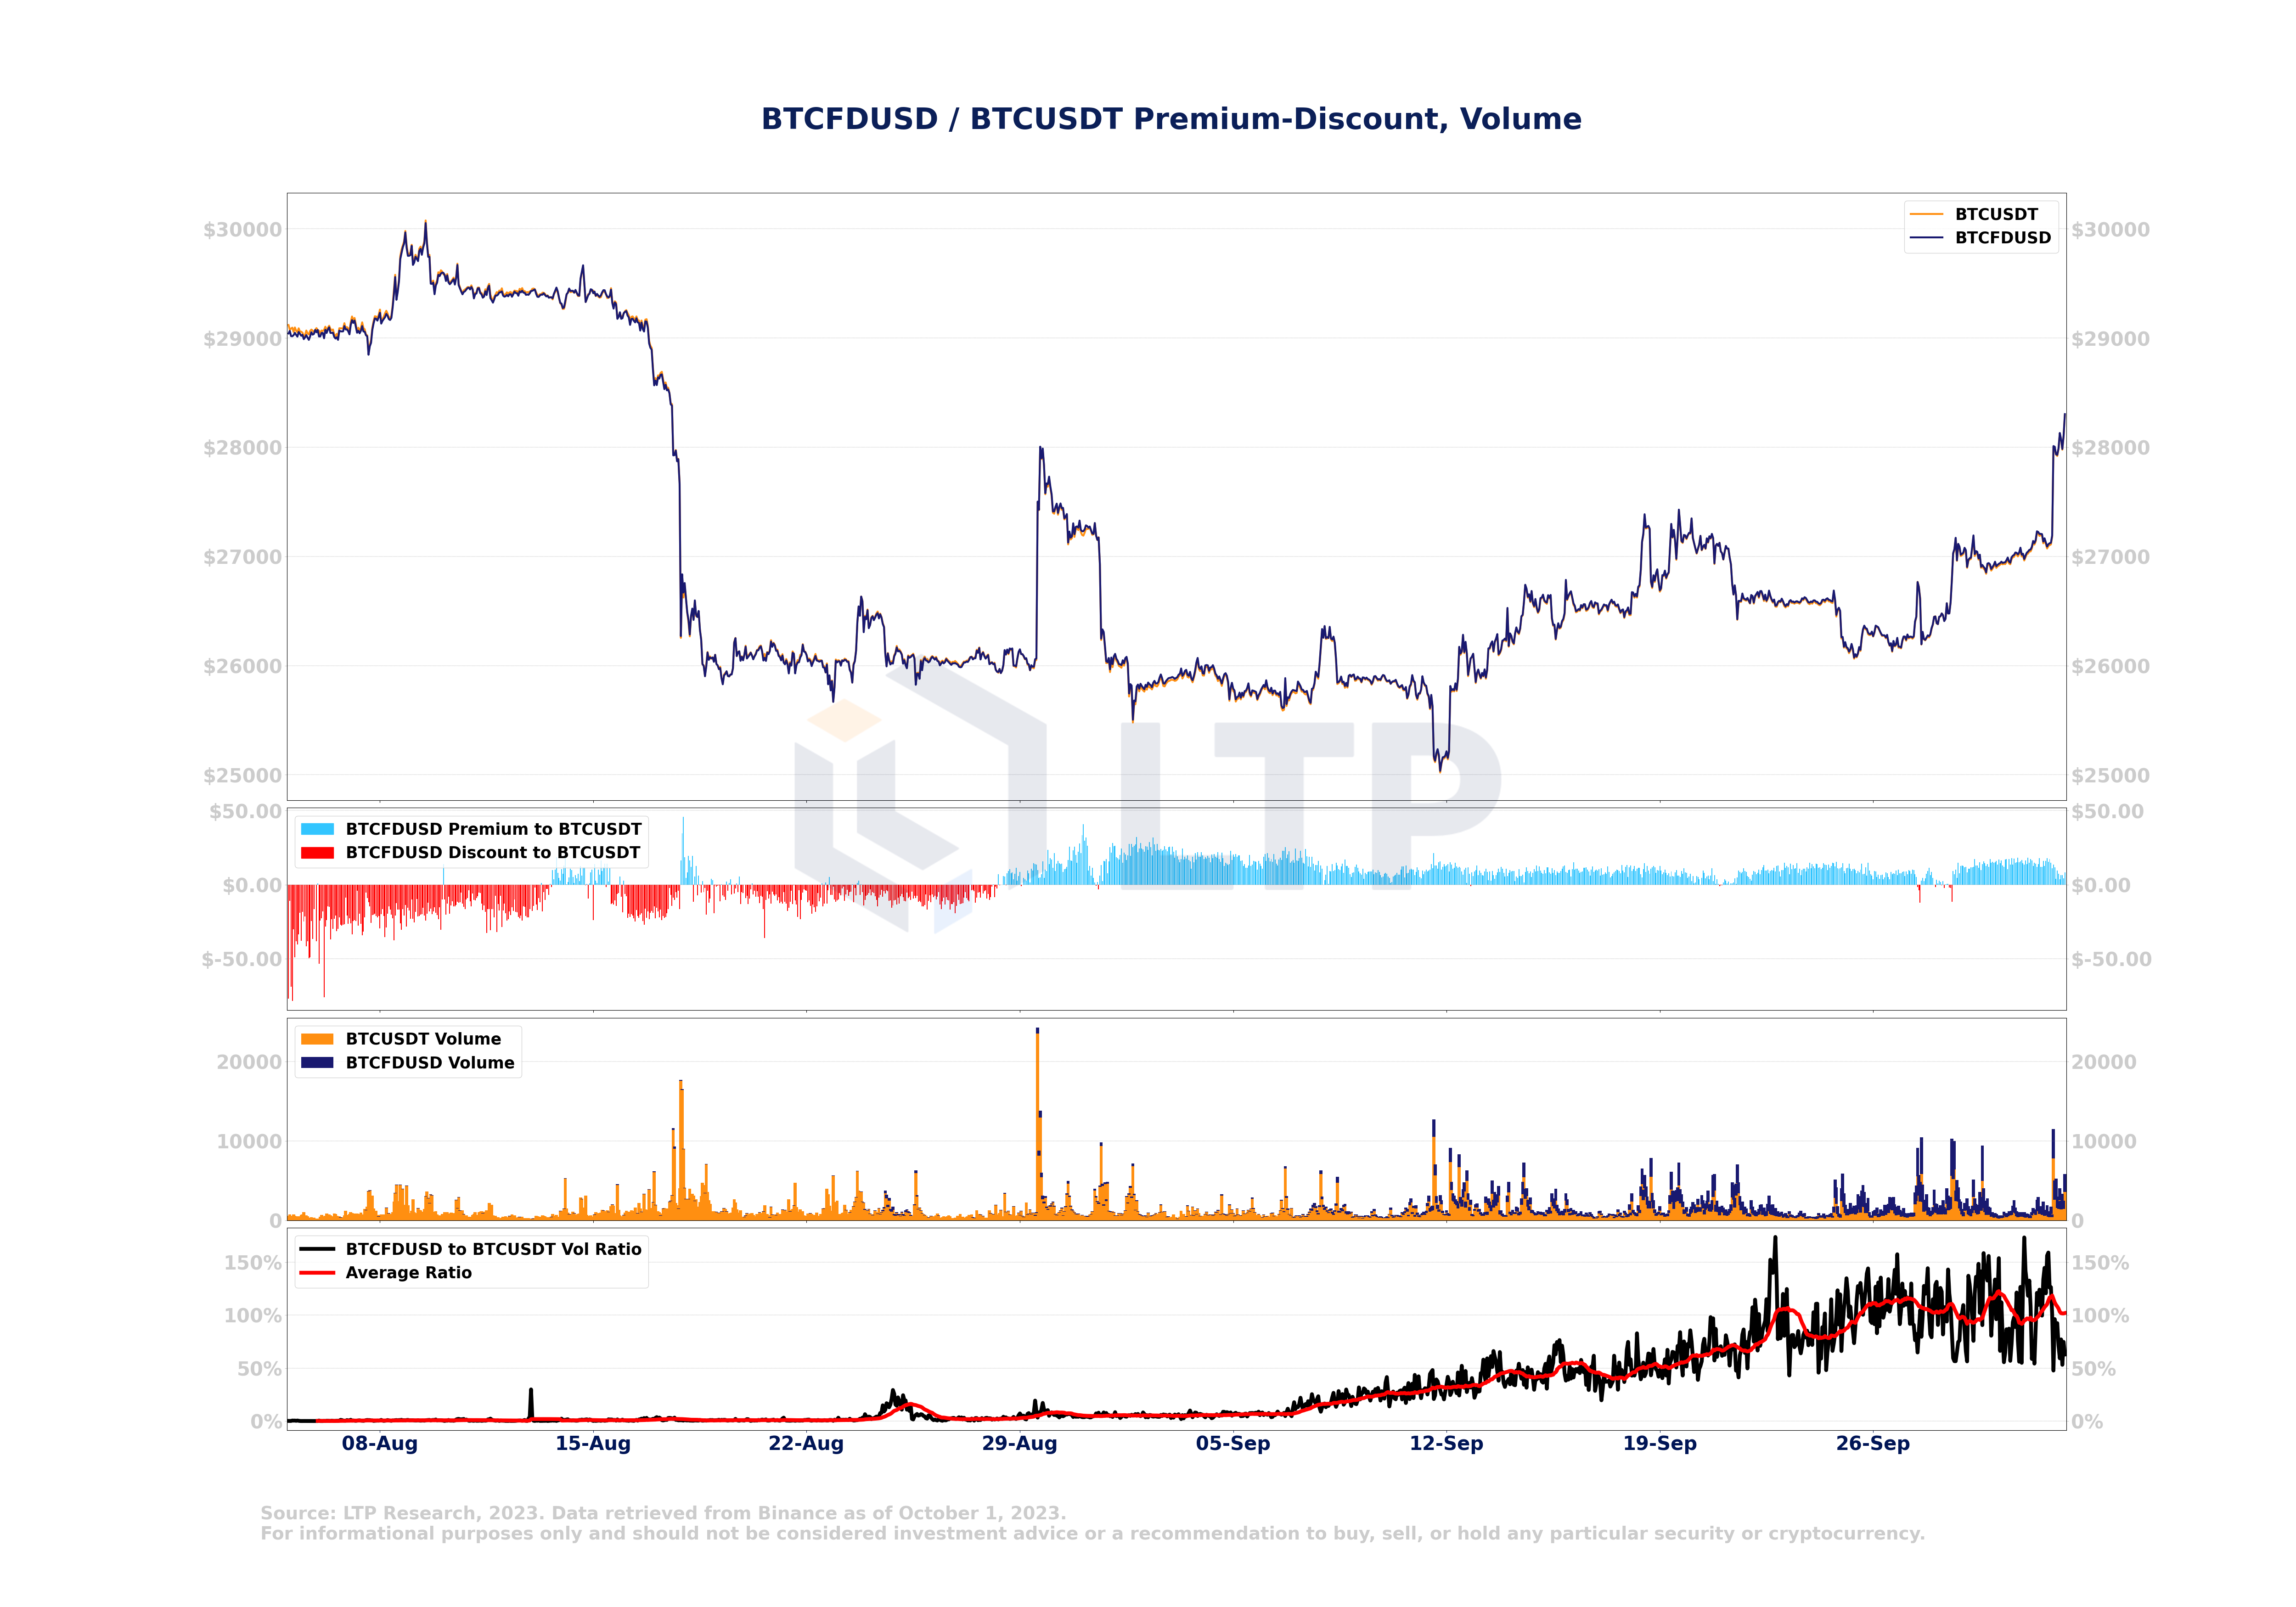
Binance launched FDUSD on August 4th, offering 0% Maker and Taker fees. The trading volume for BTCFDUSD started to increase from September 5th onwards. As the trading volume rose on September 5th, BTCFDUSD began trading at a premium compared to BTCUSDT. Currently, BTCFDUSD accounts for half of the Bitcoin spot market volume on Binance.
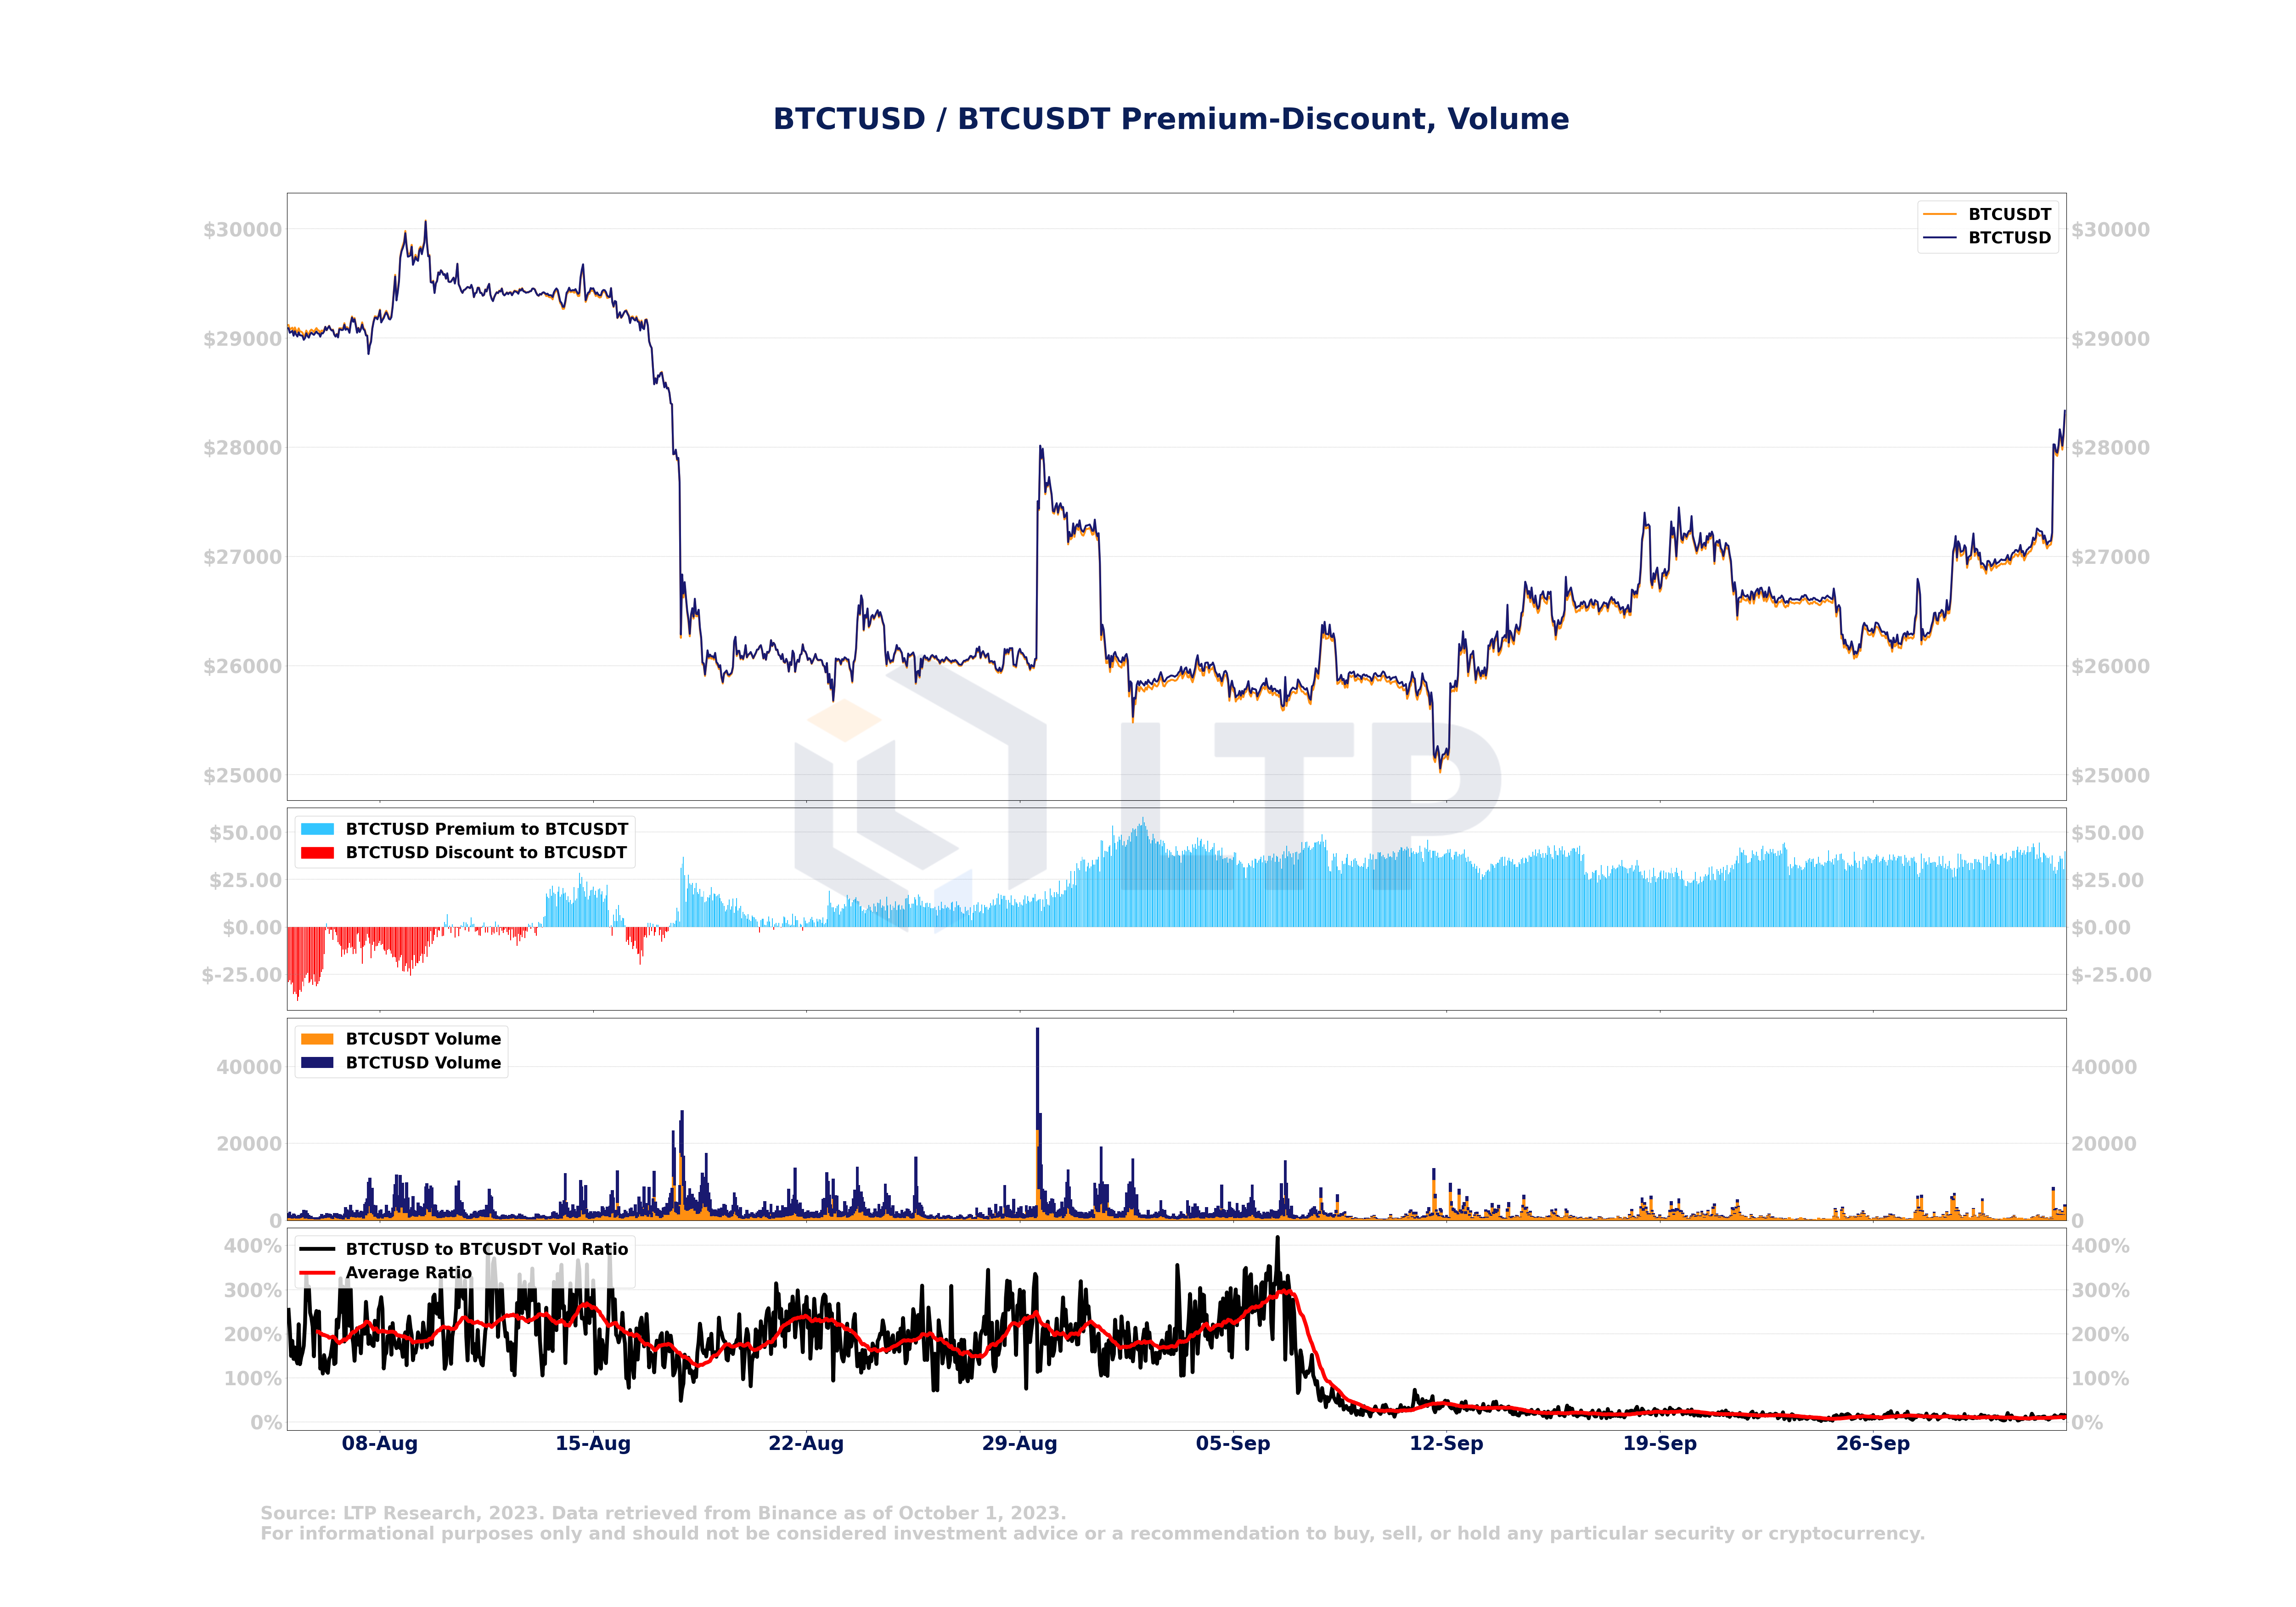
BTCTUSD's trading volume experienced a significant decline starting on September 5th, yet it's noteworthy that it continues to trade at a premium over BTCUSDT despite this decrease in volume.
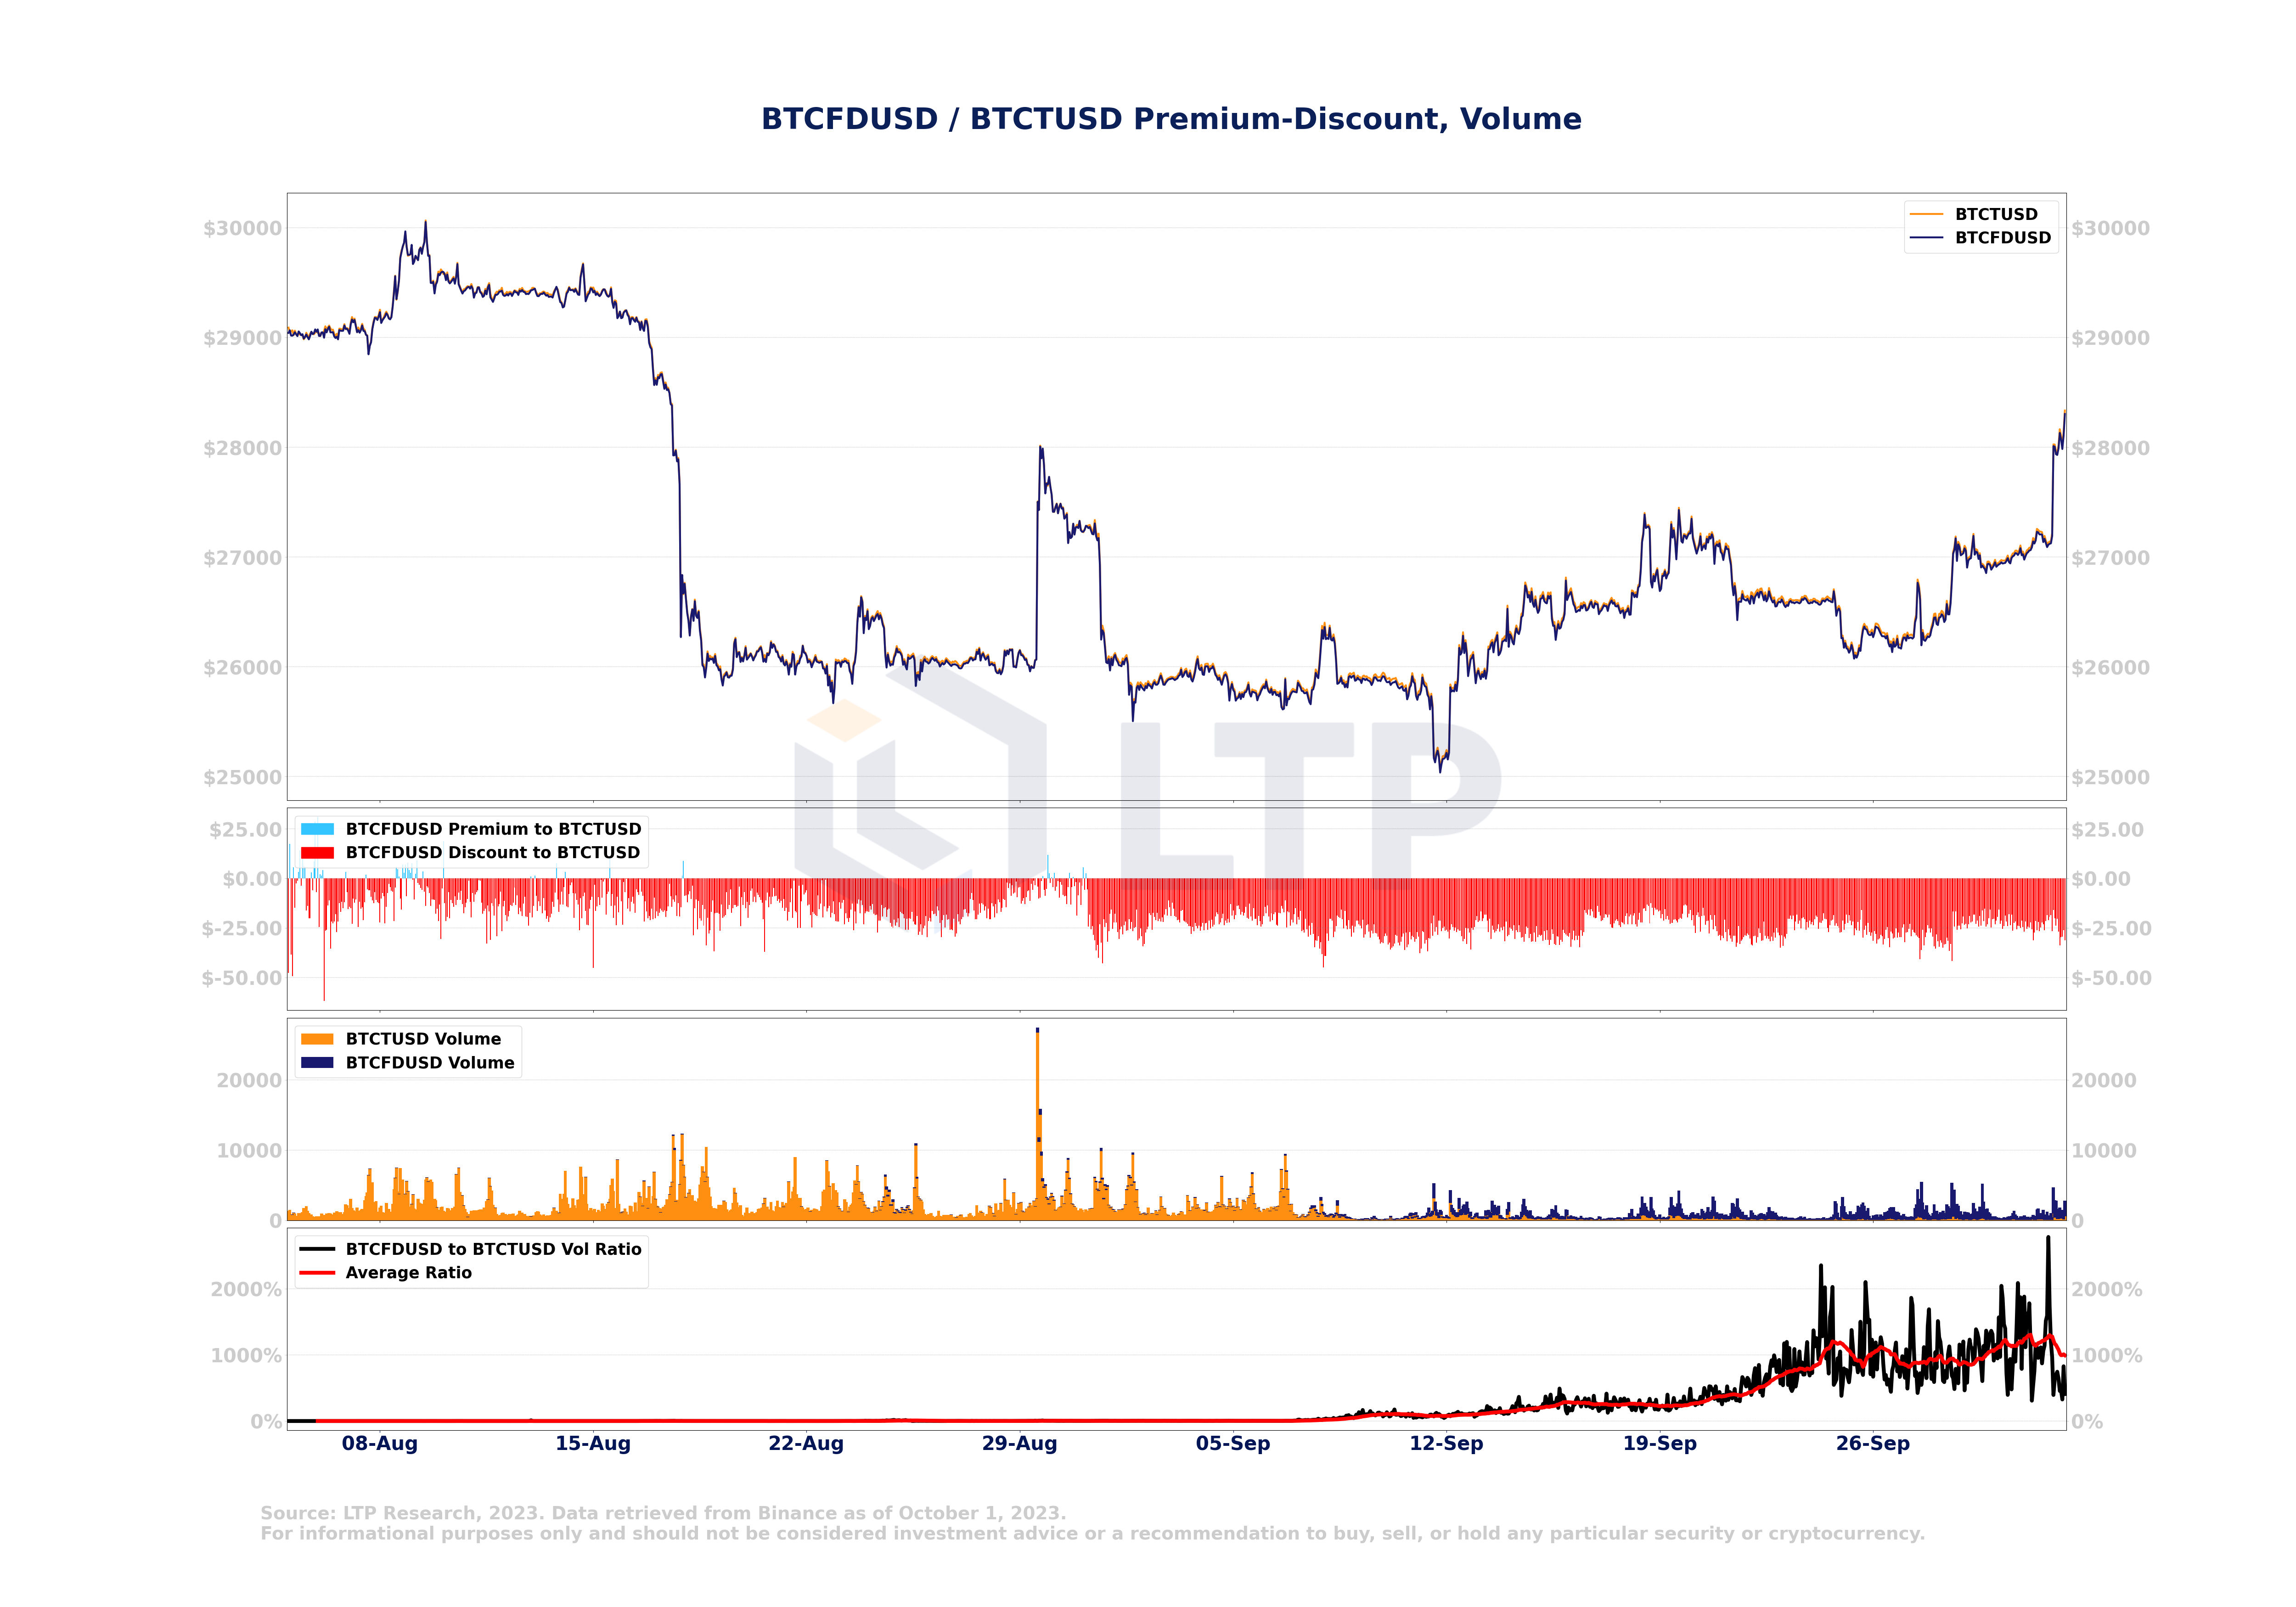
Trading volume on BTCFDUSD began to climb starting from September 5th, while volume on BTCTUSD simultaneously decreased. This indicates a clear migration of trading activity to the BTCFDUSD pair. Despite this shift, BTCTUSD continues to trade at a premium over BTCFDUSD.
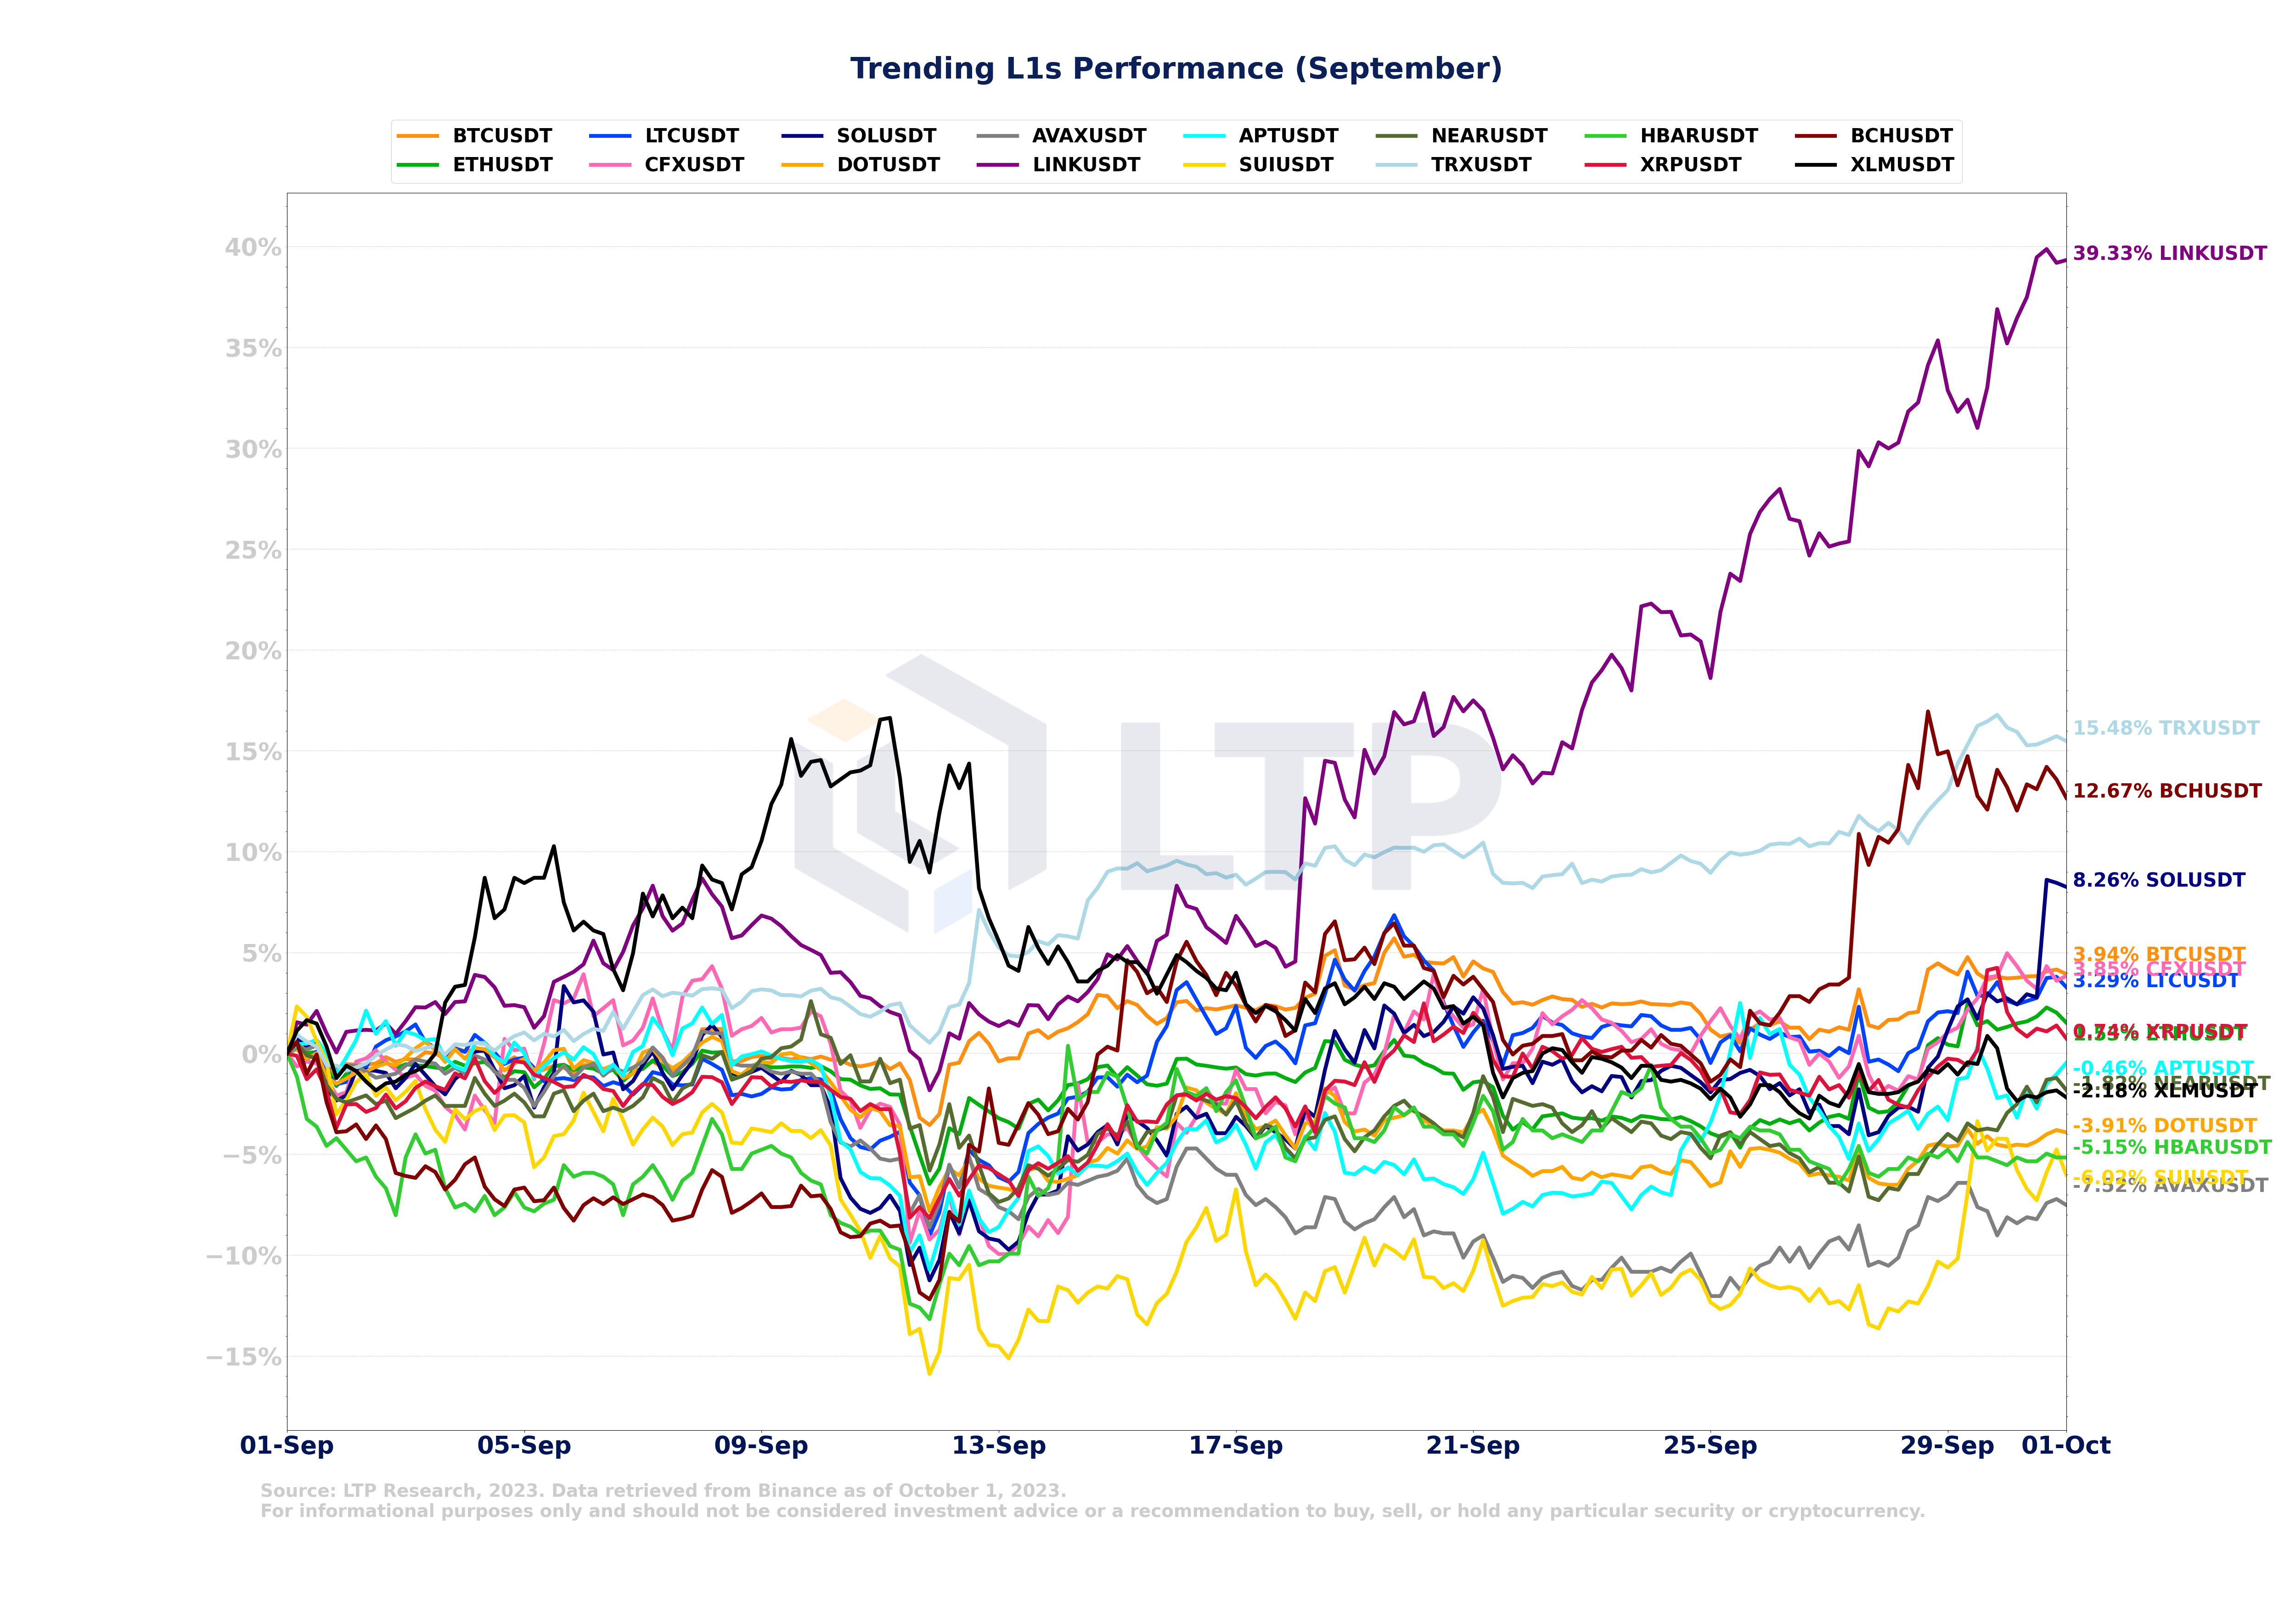
Among Layer 1 cryptocurrencies, LINK showed the highest performance, with an impressive 40% price appreciation throughout September. It was followed by TRX with a 15.5% increase, BCH with a 12.7% increase, and SOL with an 8.3% increase. Bitcoin also experienced a 4% price increase during the same period.
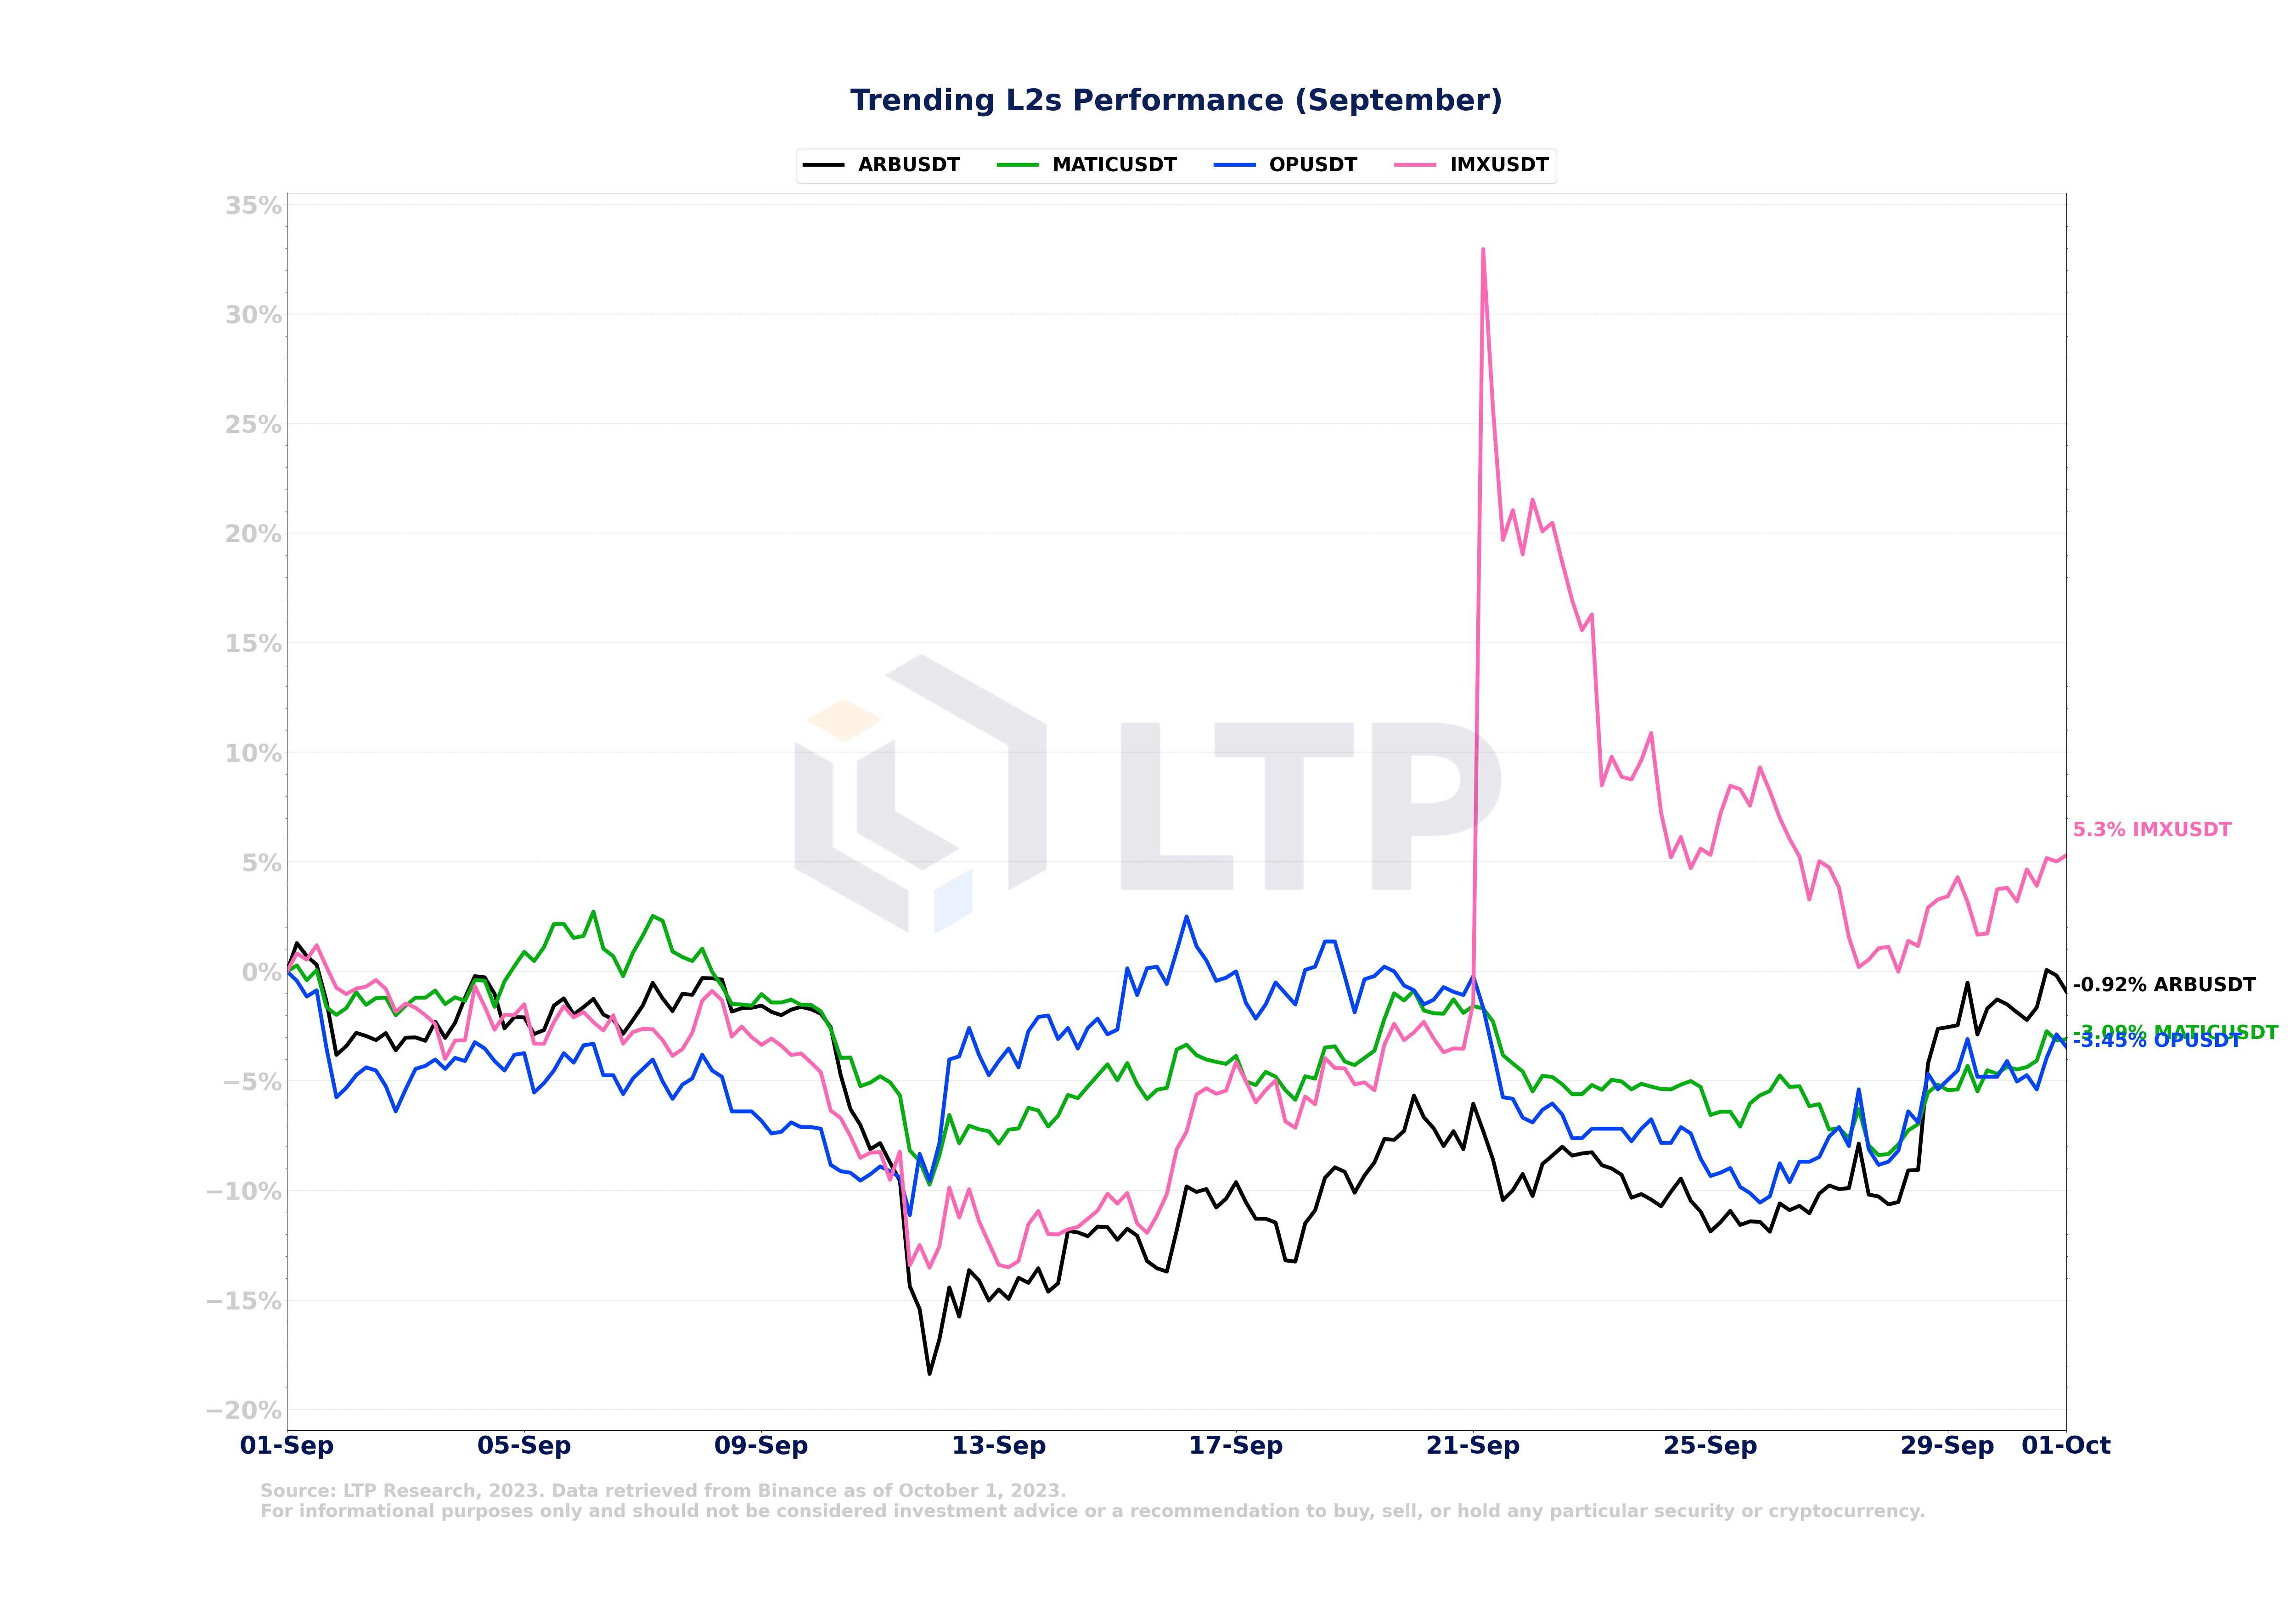
Among Layer 2 cryptocurrencies, IMX showed the highest return in September, with a 5.3% increase. It was followed by ARB with a 0.9% increase. However, Matic and OP experienced a decrease in price, with Matic declining by 3% and OP by 3.45% during the same period.
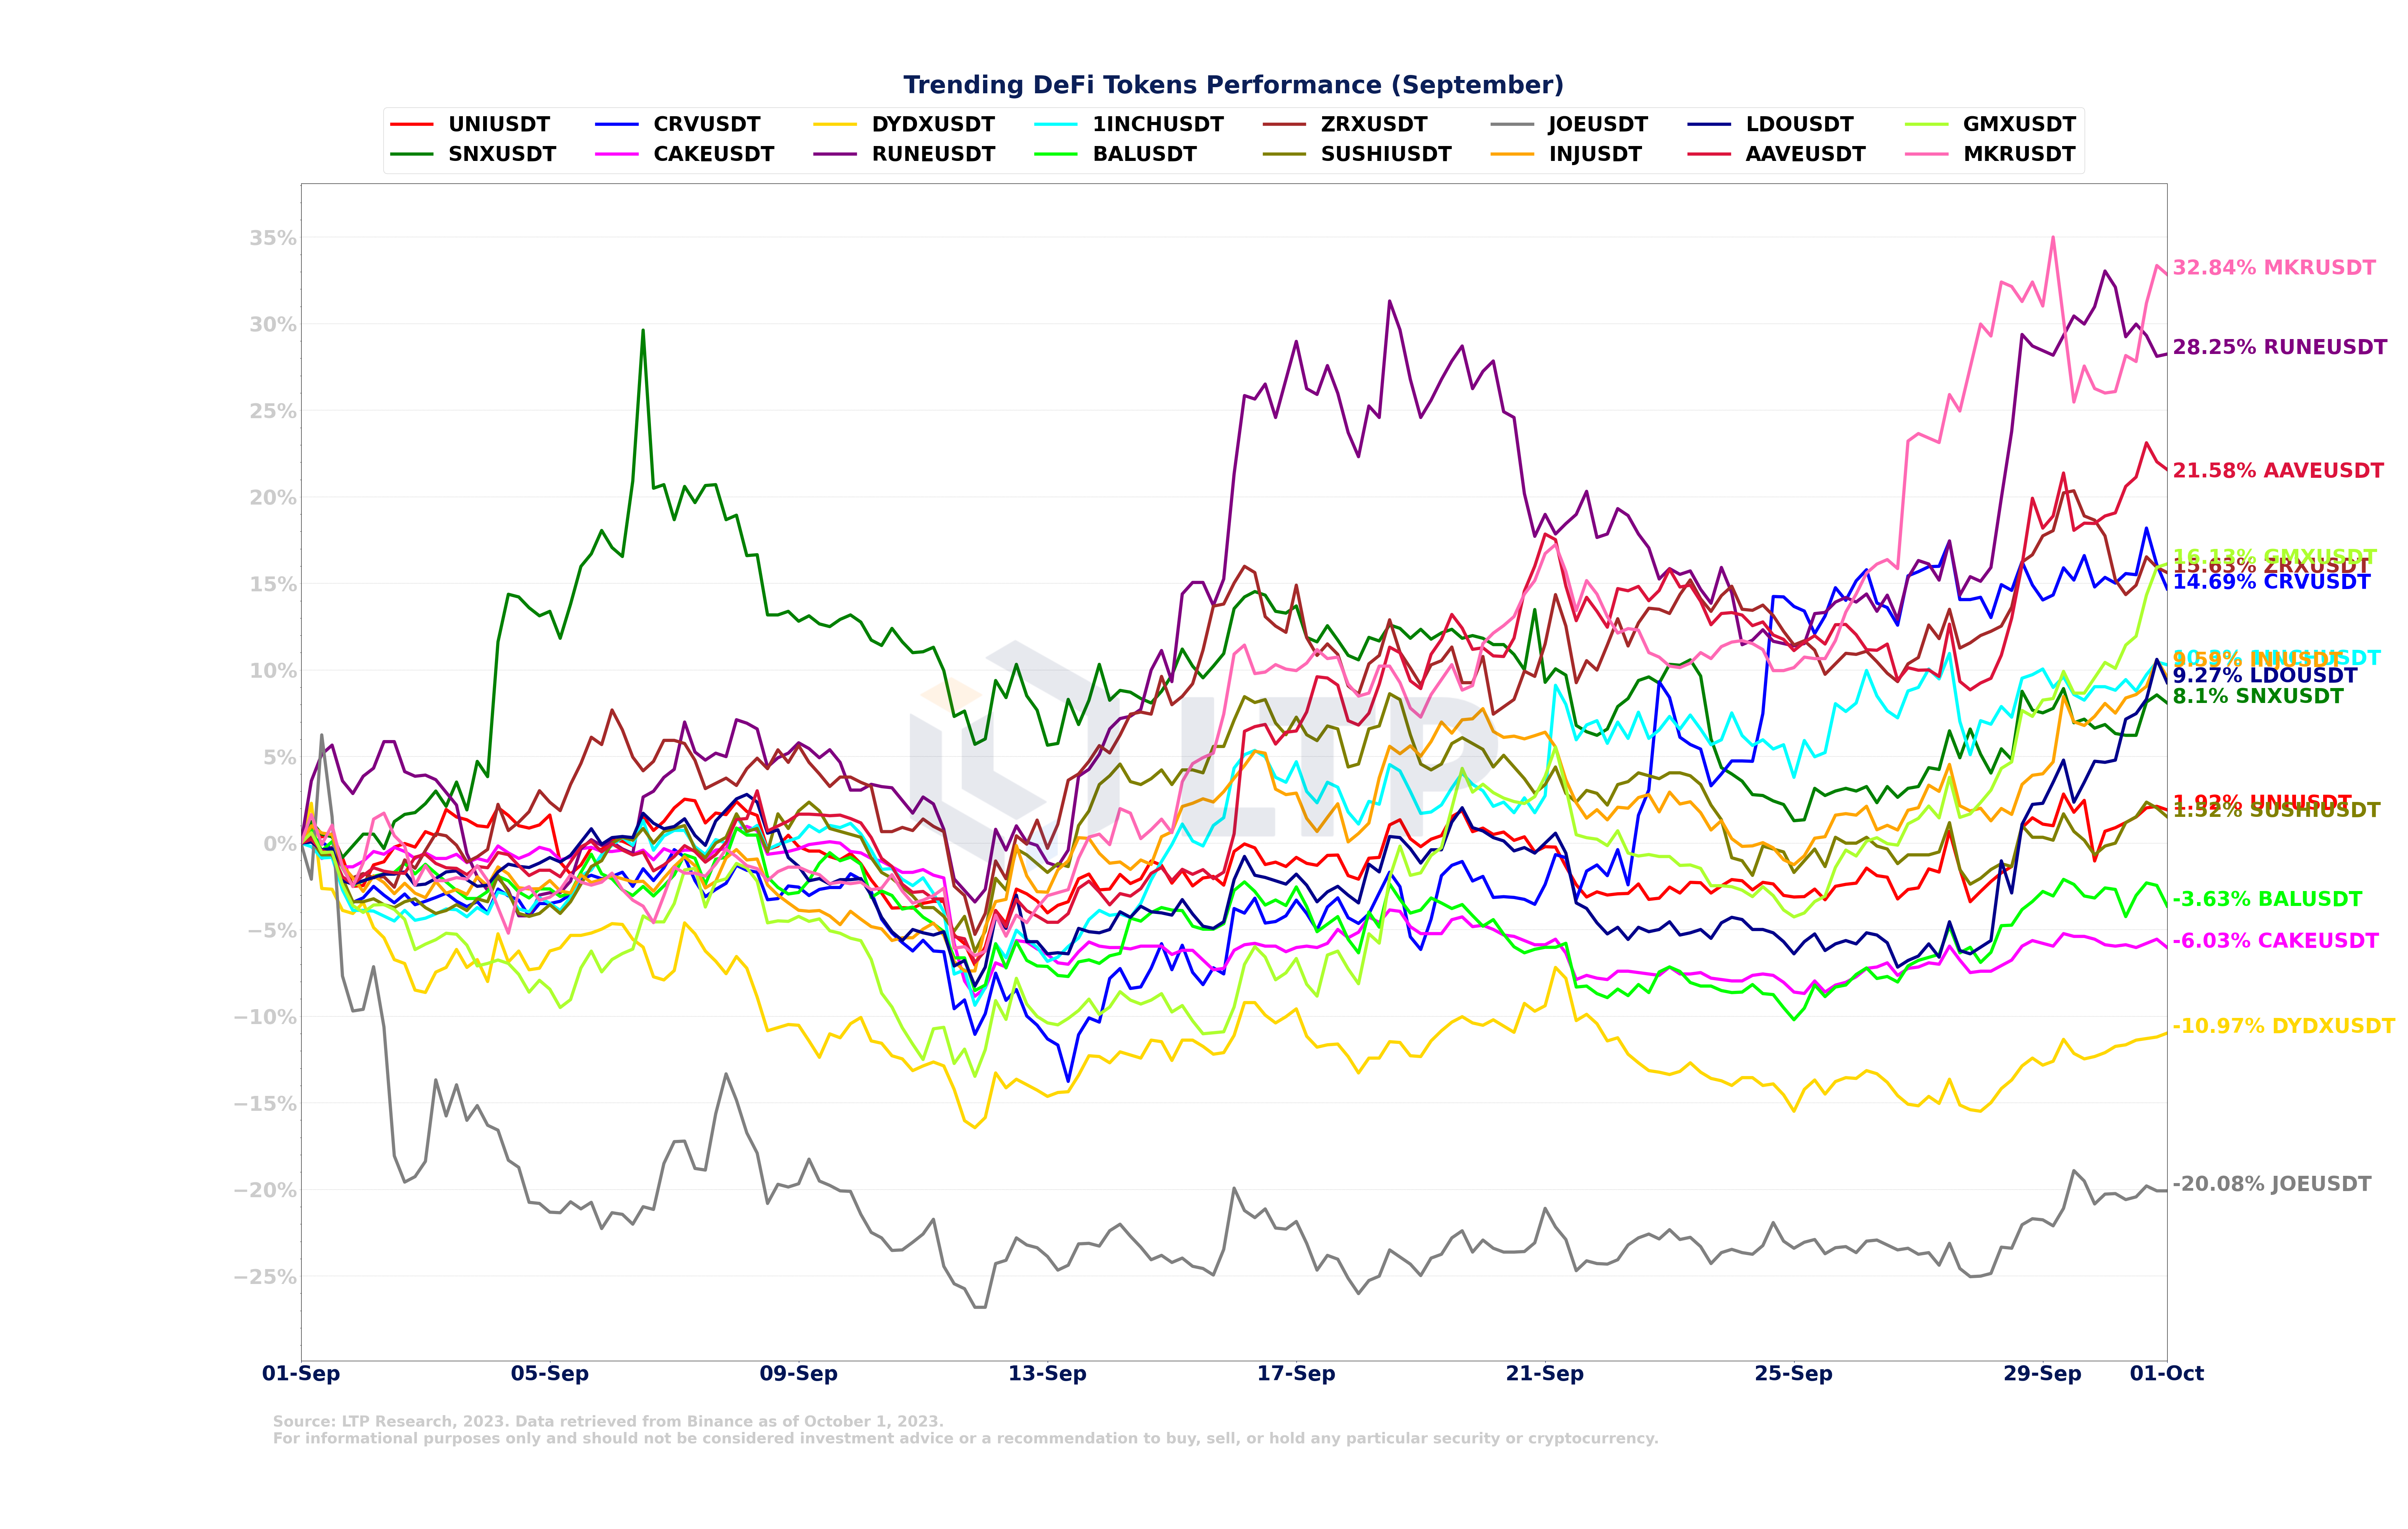
Among DeFi tokens, MKR showed the highest performance, delivering an impressive 32.8% price increase in September. It was followed by RUNE with a 28.25% increase and AAVE with a 21.58% increase. However, JOE underperformed, experiencing a 20% price depreciation during the same period.
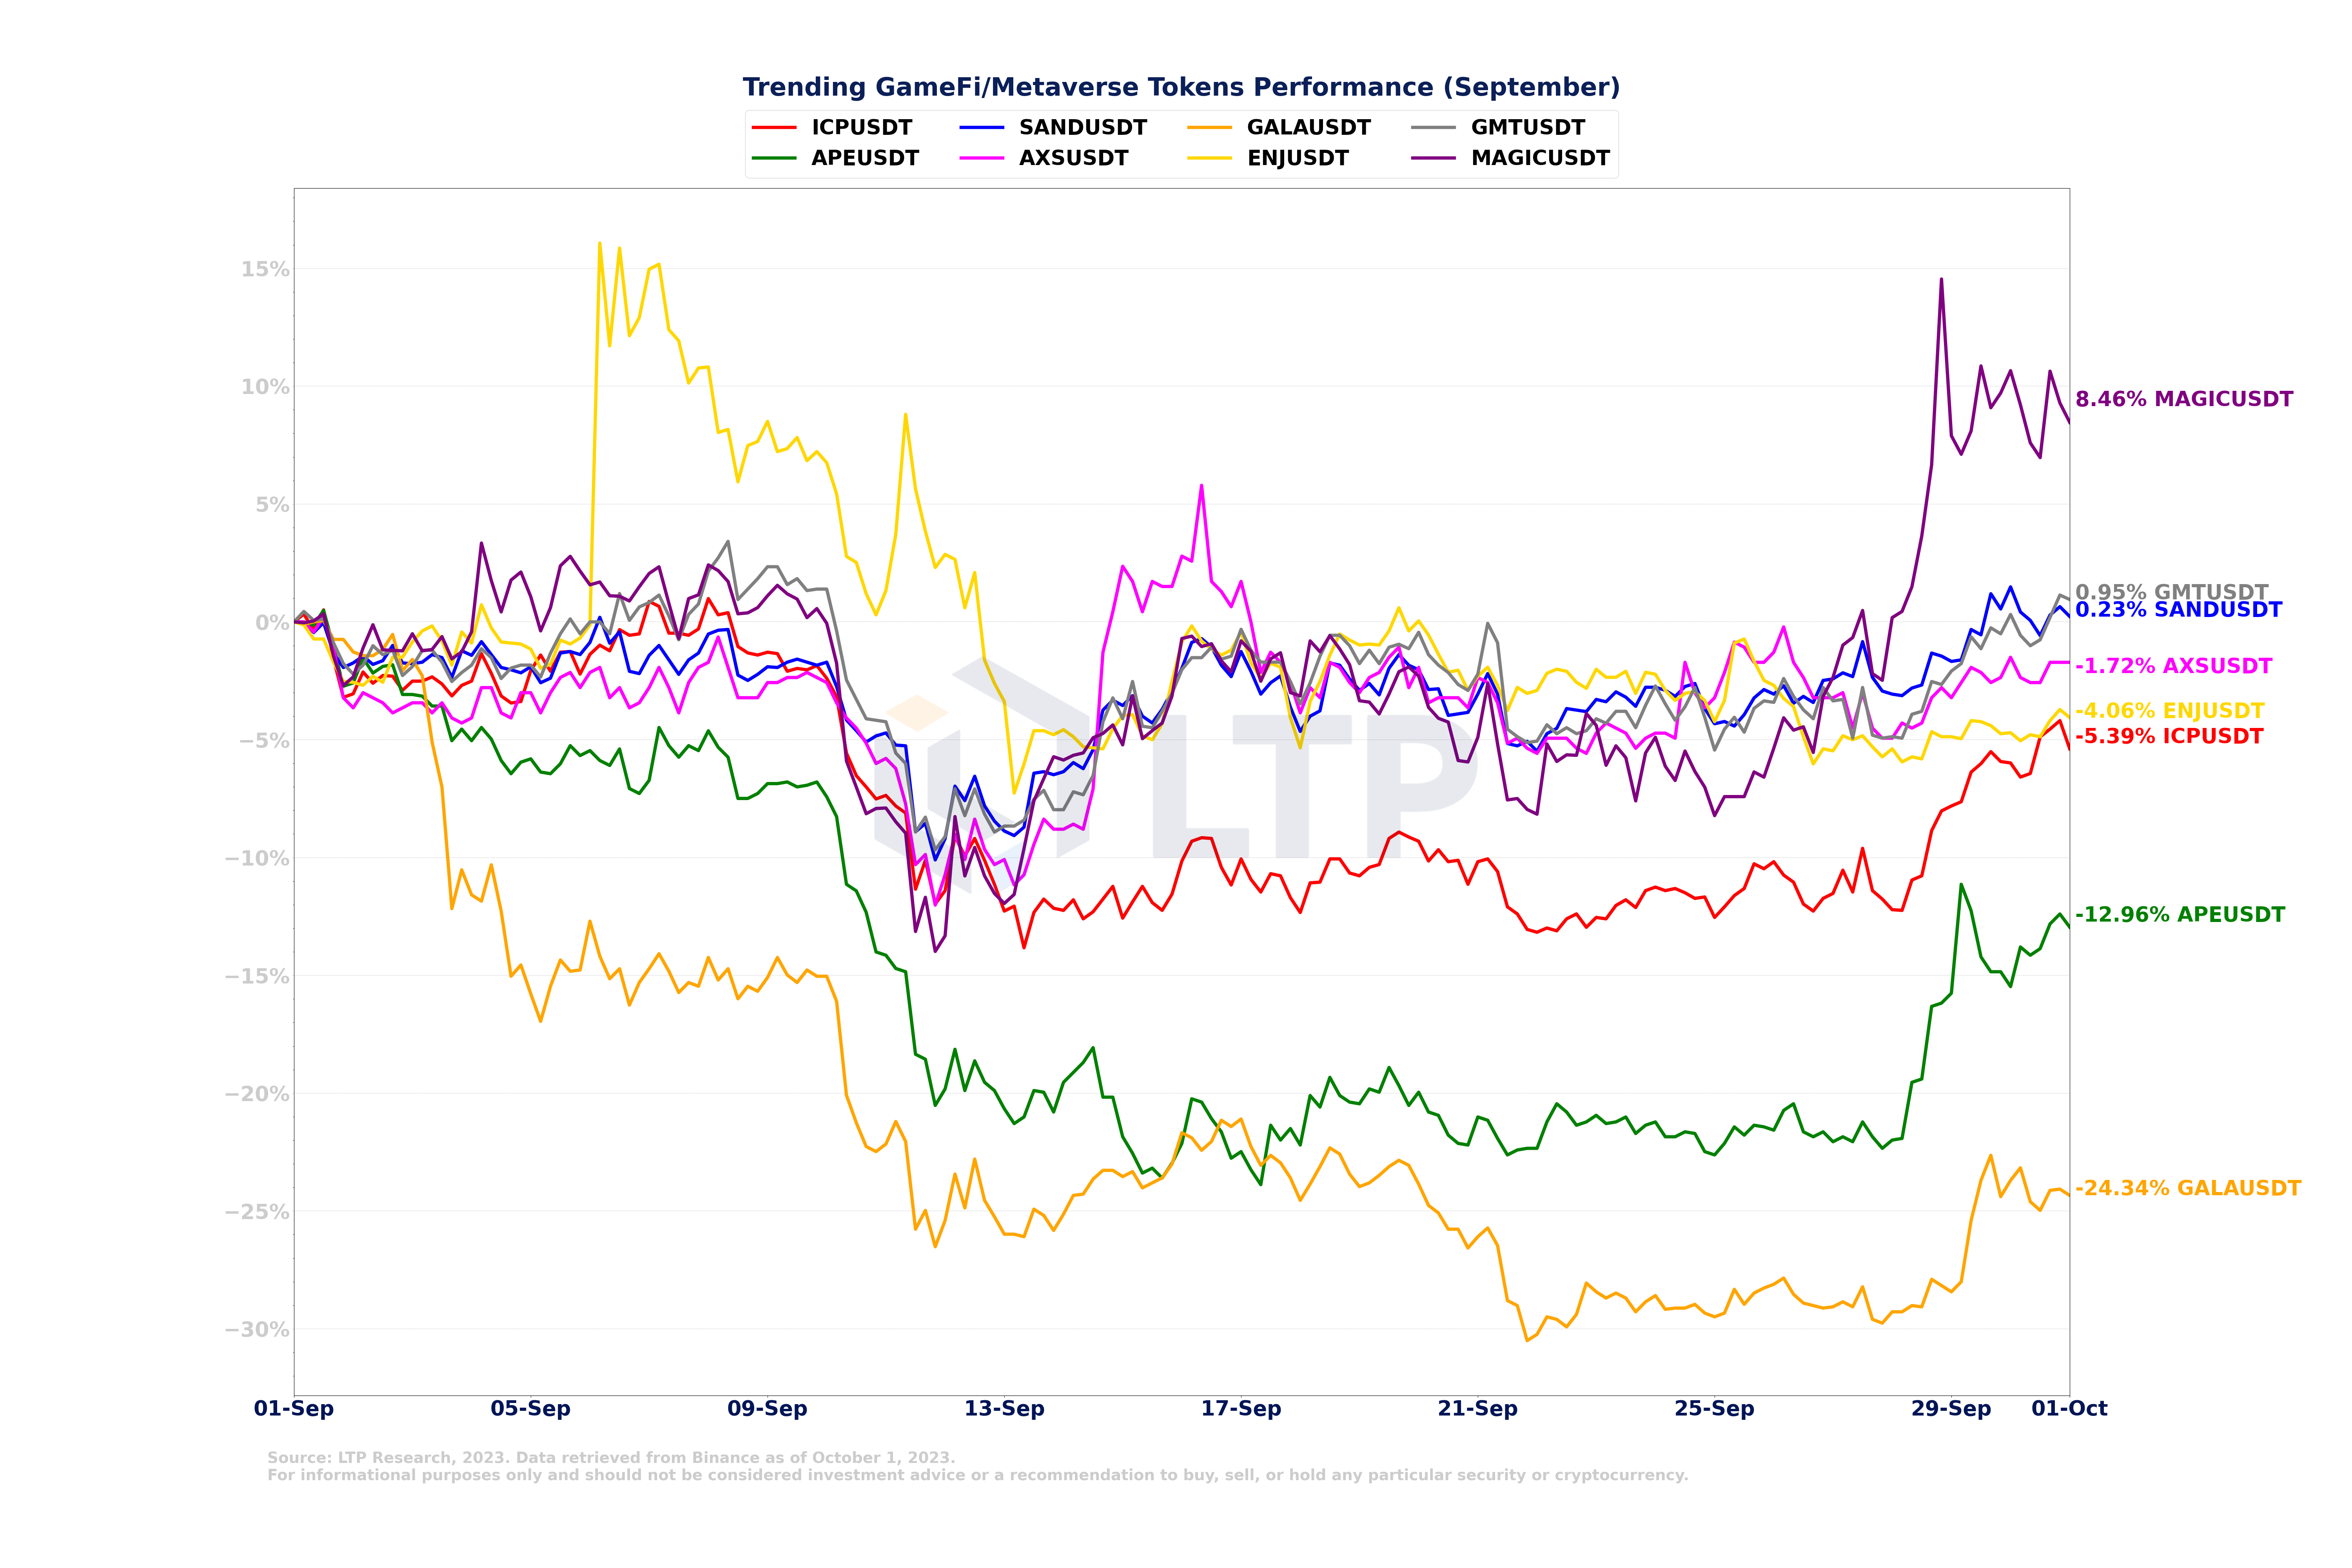
Among GameFi/Metaverse tokens, MAGIC displayed the strongest performance, with an 8.46% price increase in September. However, overall, the GameFi/Metaverse sectors experienced a sluggish performance compared to the DeFi sector during the same period.
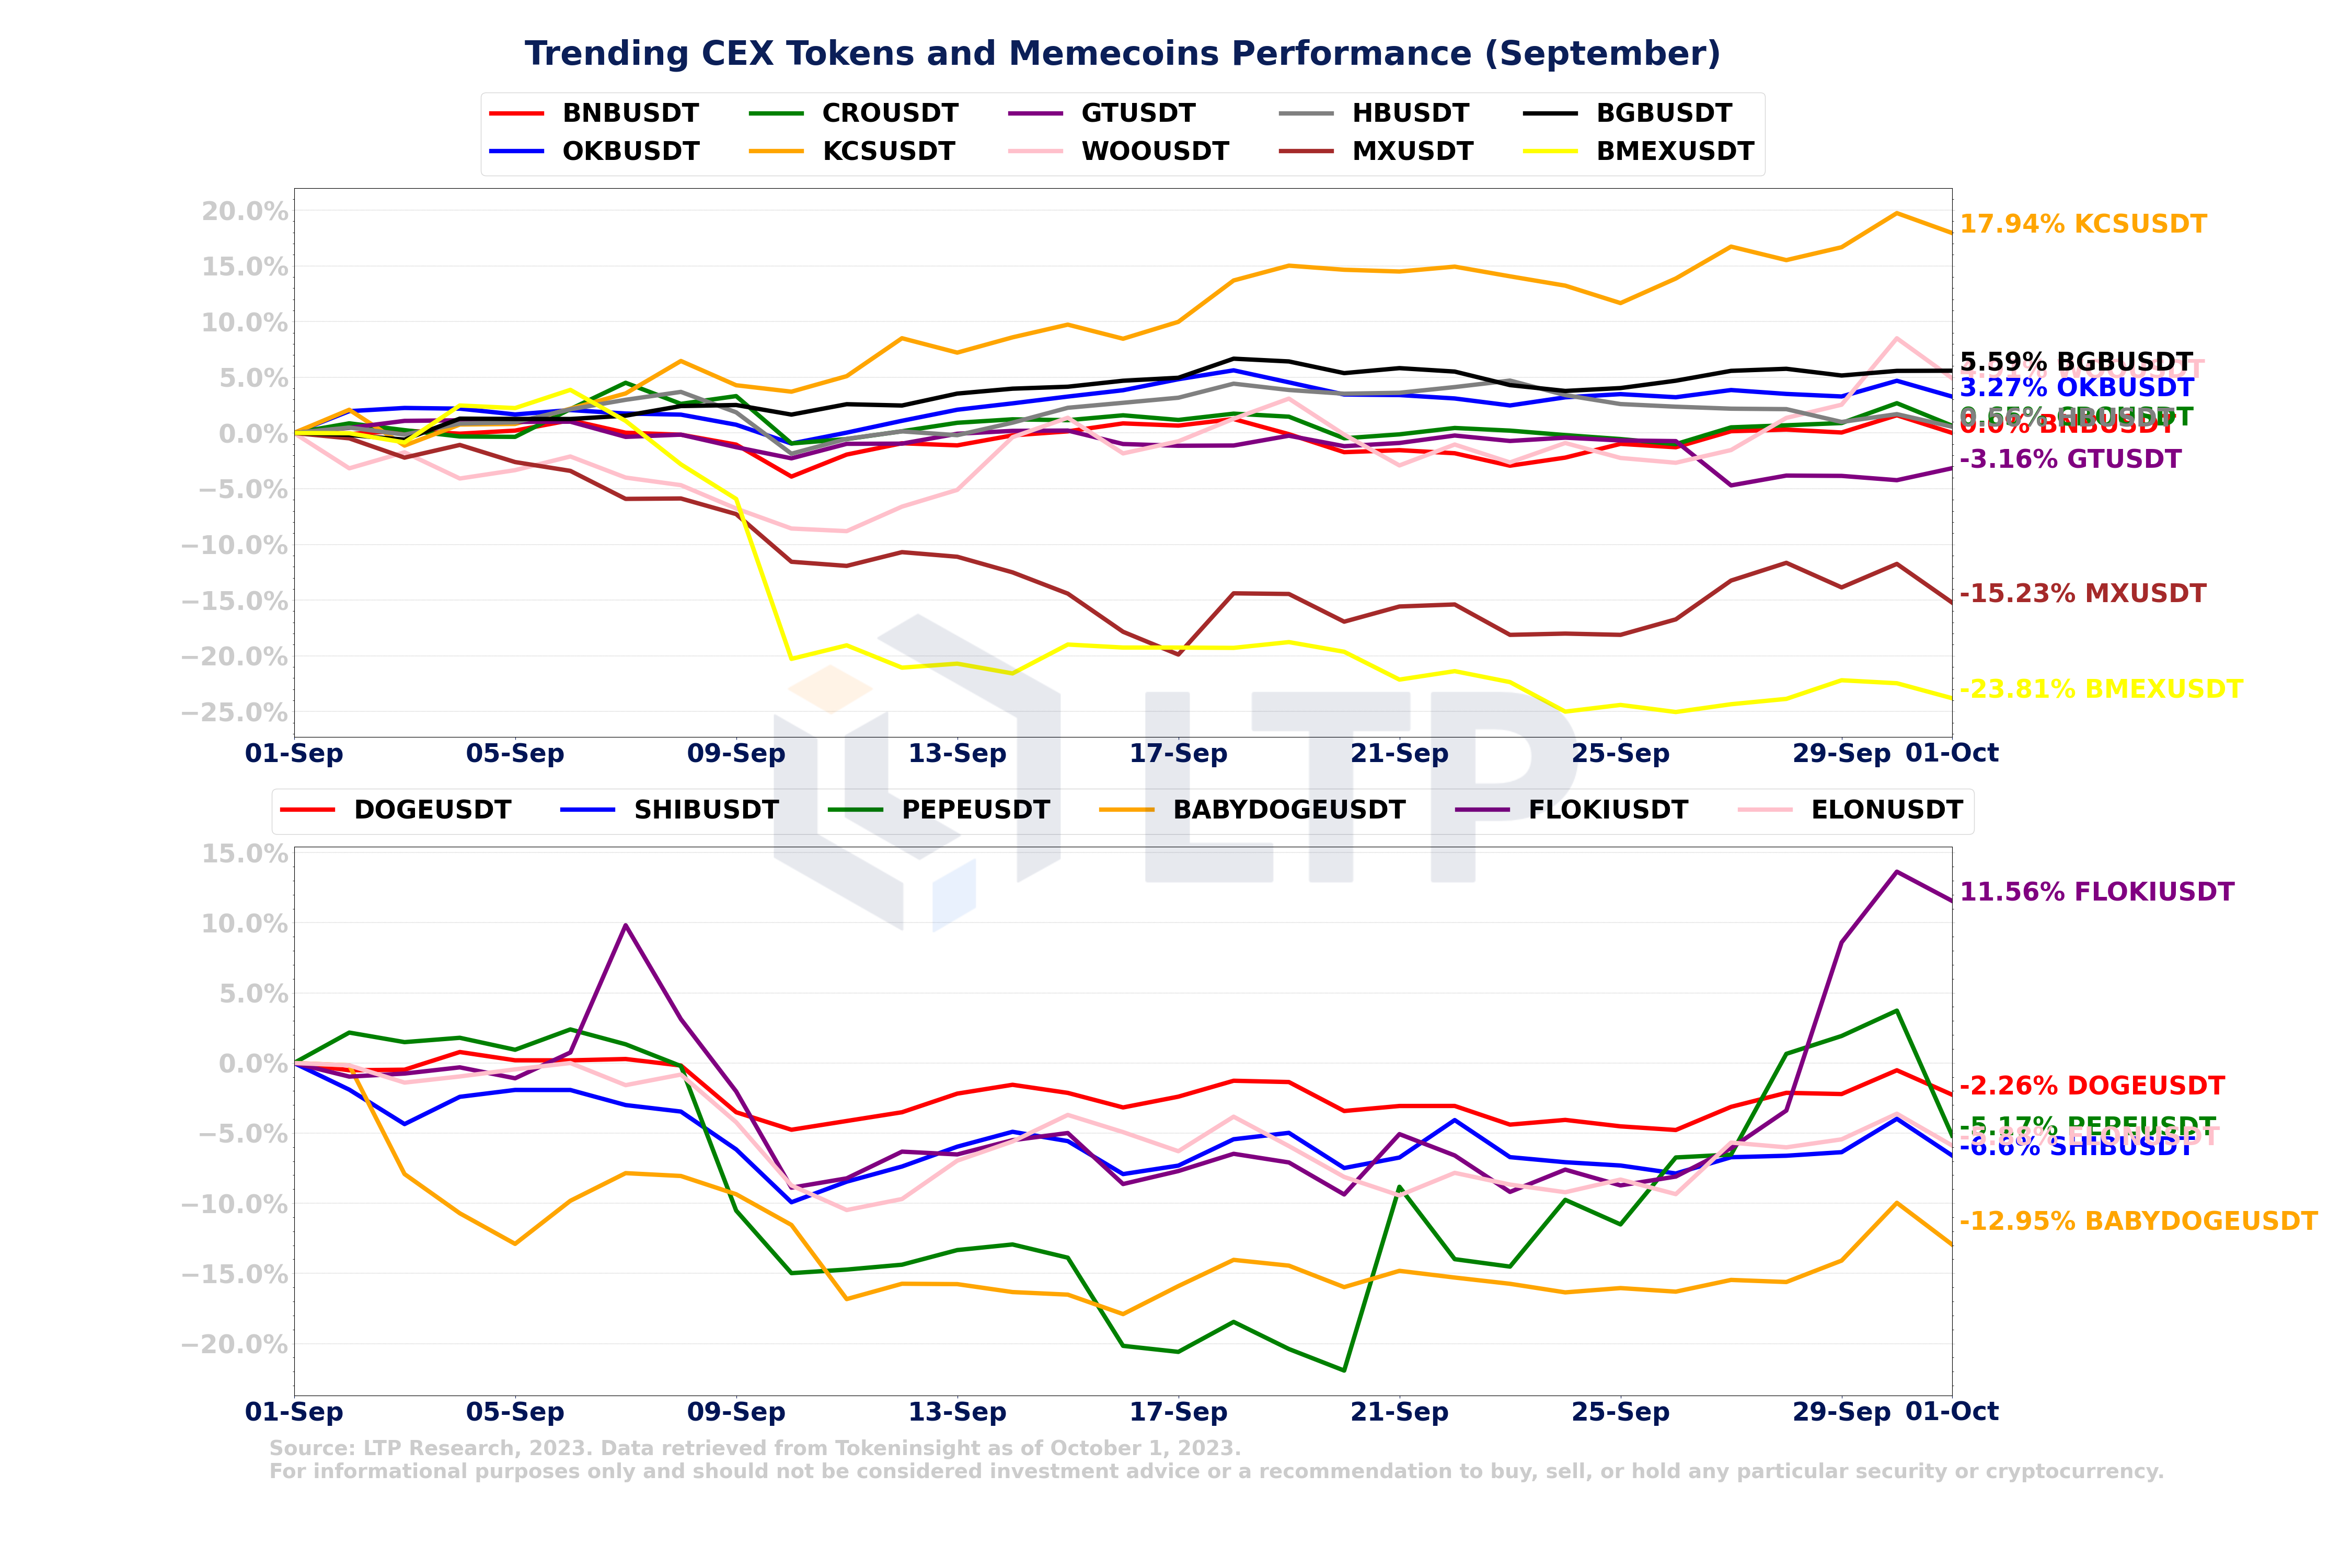
Among CEX tokens, KCS demonstrated strong performance, with an 18% price increase. On the other hand, among memecoins, FLOKI outperformed, delivering an 11.56% price increase.
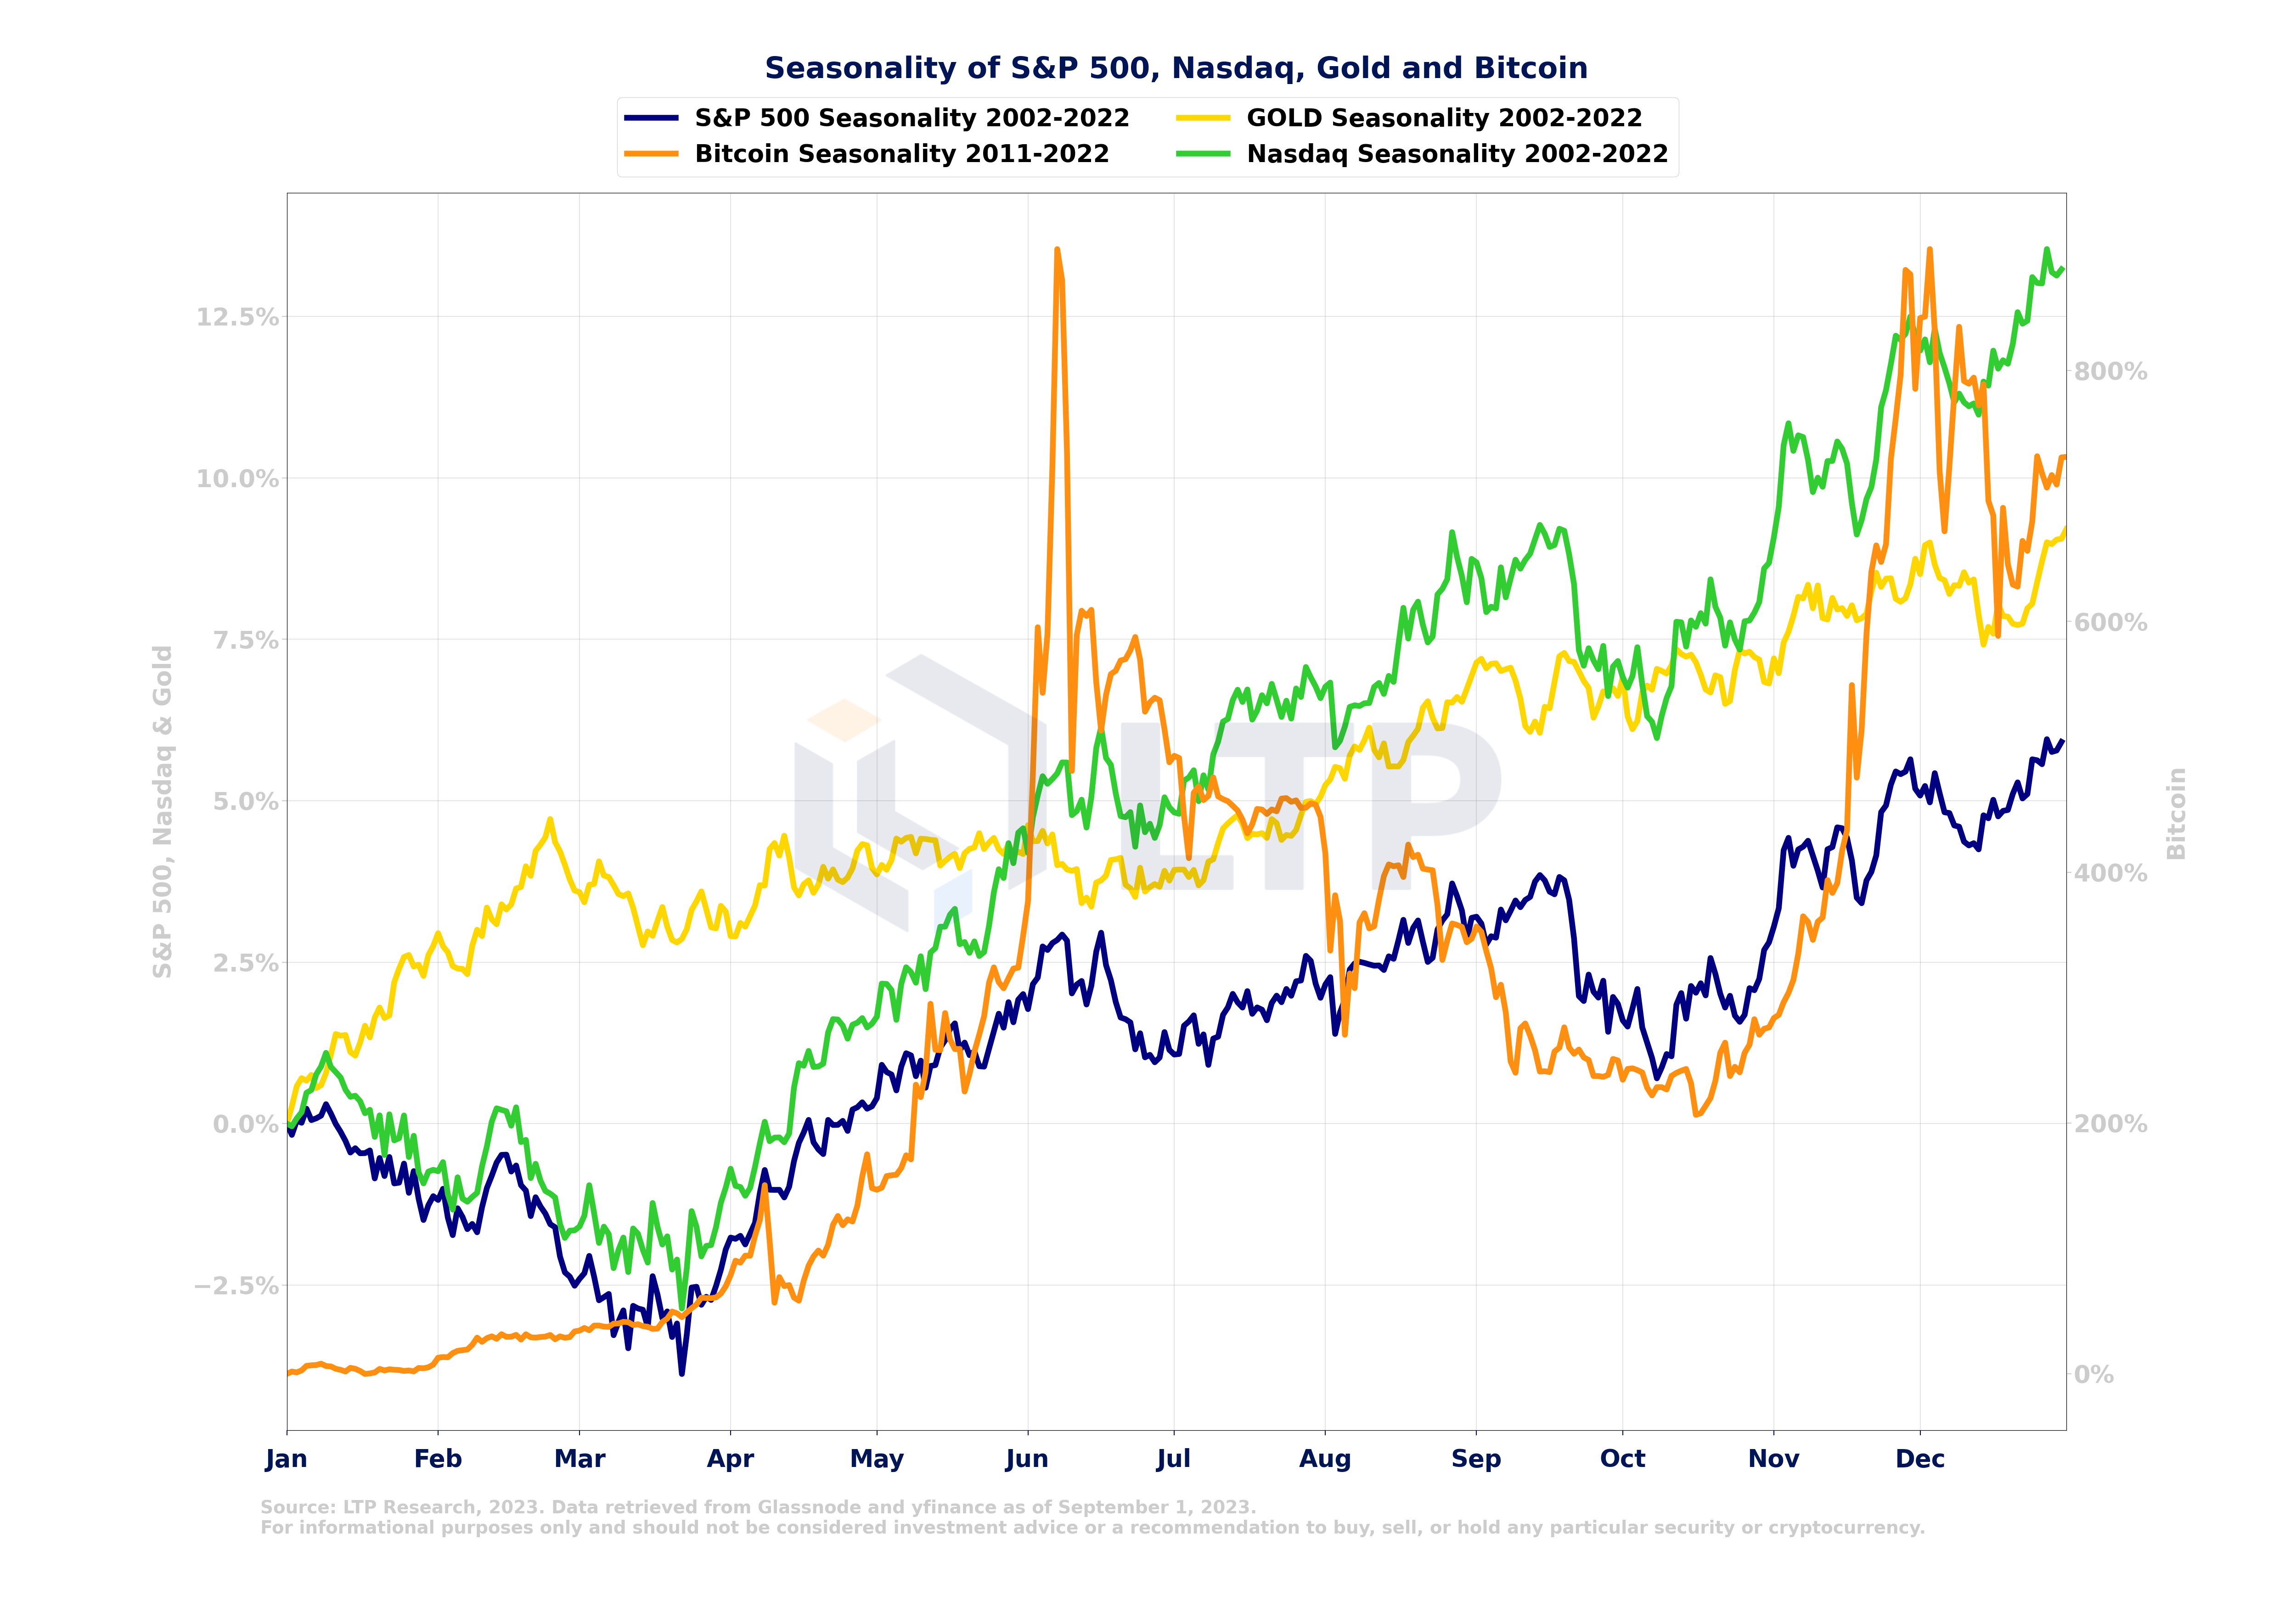
Past performance is no guarantee of future results. In terms of seasonality, October has historically been known as a turning point for market corrections.
Shock in India: An unexpected global call for crypto regulation
Coinbase launches crypto lending platform for US institutions
Coinbase, Aave, And Circle Form Coalition to Promote Tokenized Assets: Report
U.S. CPI Inflation Jumped to 3.7% in August, More Than Expected
Hong Kong Probe Into Crypto Exchanges JPEX Results in Arrest
9 US senators publicly back Elizabeth Warren’s crypto bill
South Korea focuses on OTC crypto regulations as unlawful deals reach $4B
India working on 5-point crypto legislation as ban is ruled out
EU parliament votes overwhelmingly in support of DAC8 crypto tax reporting rule
Binance.US not cooperating with investigation, US SEC says in filing
Grayscale files for new Ether futures ETF — Official
Bybit expects to exit UK market as new regulations loom
SEC Delays Spot Bitcoin ETF Decision for All Applicants Including BlackRock, Fidelity
OKX Planning Web3 Foray Into India, Chief Marketing Officer Says
Robinhood to Buy Back Sam Bankman-Fried's Stake for $605.7M
Bitcoin's Use as Margin Collateral in Crypto Futures Trading Is GrowingCrypto funds hit $342 million outflow streak as bitcoin bucks trend
Genesis to Shutter Crypto Trading Desk for U.S. Market
Solana users fall to lowest level in more than 2 years
Following SEC delays, ARK Invest and 21Shares file for spot Ether ETF
Vitalik Buterin’s X account hacked to carry out phishing attack that stole $700,000 in crypto, NFTs
Messaging App Telegram Gives Endorsement to TON Project; Token Surges
Judge Allows Bankrupt FTX to Sell Its Crypto Holdings, Including BTC and SOL
A Year After Ethereum Merge, Net Supply Down Nearly 300K Ether
Bybit expects to exit UK market as new regulations loom
JPEX exchange suspends certain operations, hikes fees amid liquidity crisis
Mark Cuban loses $860,000 of crypto to phishing attack
Hong Kong regulator: Crypto firms cannot claim to be 'banks'
Grayscale Investments files for new ether futures ETF
Hong Kong looks to release stablecoin regulations by mid-2024, lawmaker says
Tether reportedly shuts USDT redemption for some Singapore customers
Tension rises between Coinbase and SEC over Celsius bankruptcy plan
SEC Extends Ark, Global X ETF Deadlines as Government Shutdown Looms
Binance Sells Russian Unit to Day-Old CommEX, Exits Country
US Treasury sanctions Ethereum wallet tied to cartel over ‘illicit fentanyl trafficking’
Coinbase rolling out perpetual futures trading for retail users outside US
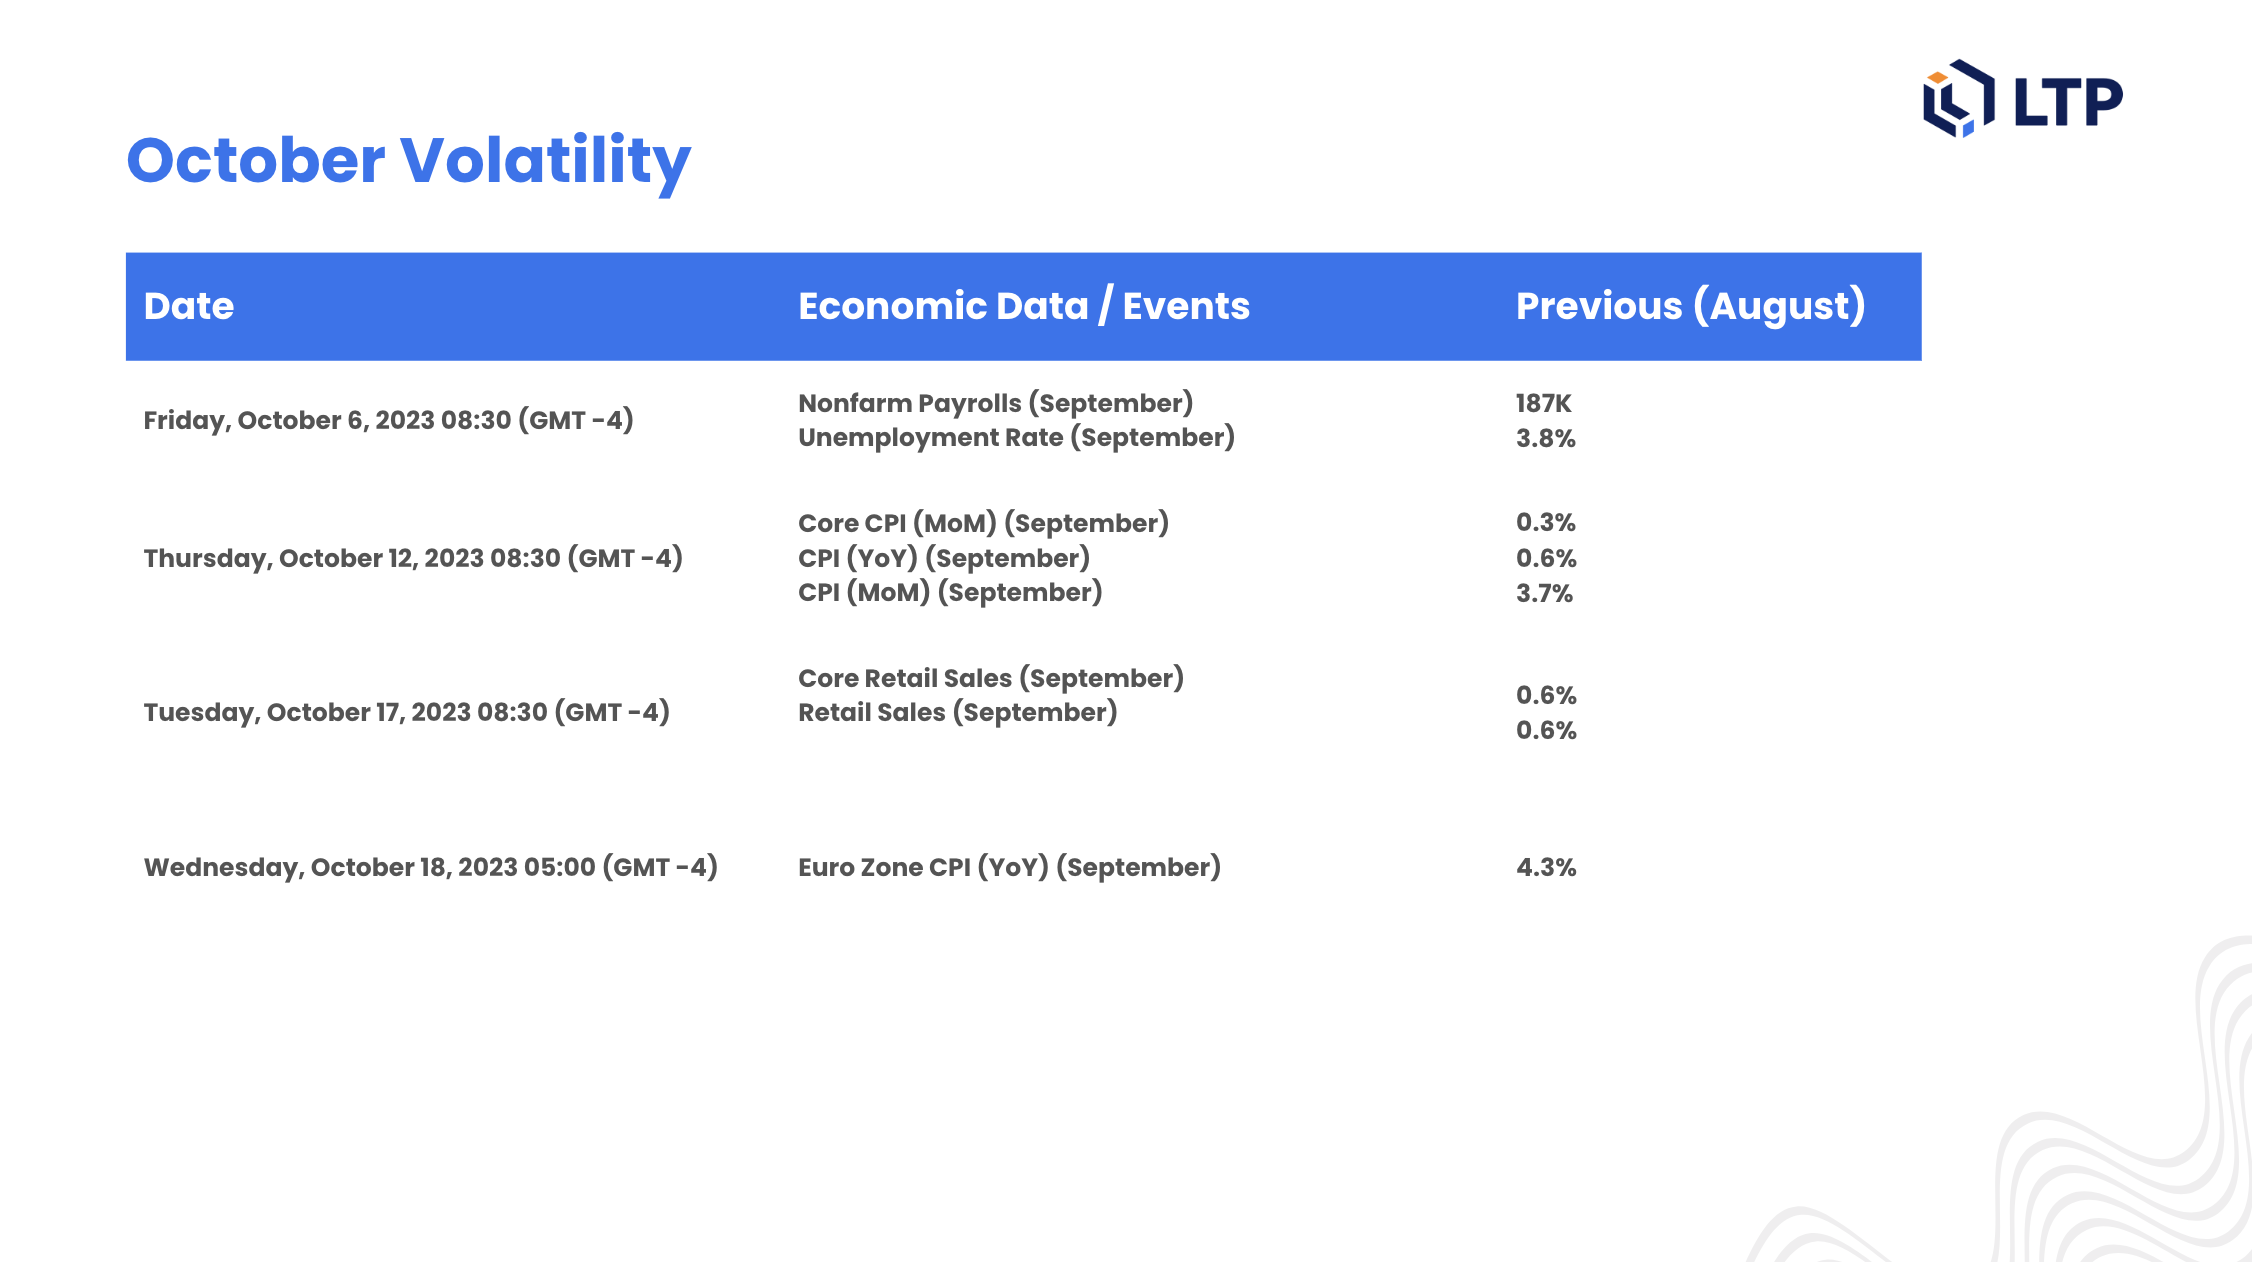
October Volatility
Appendix
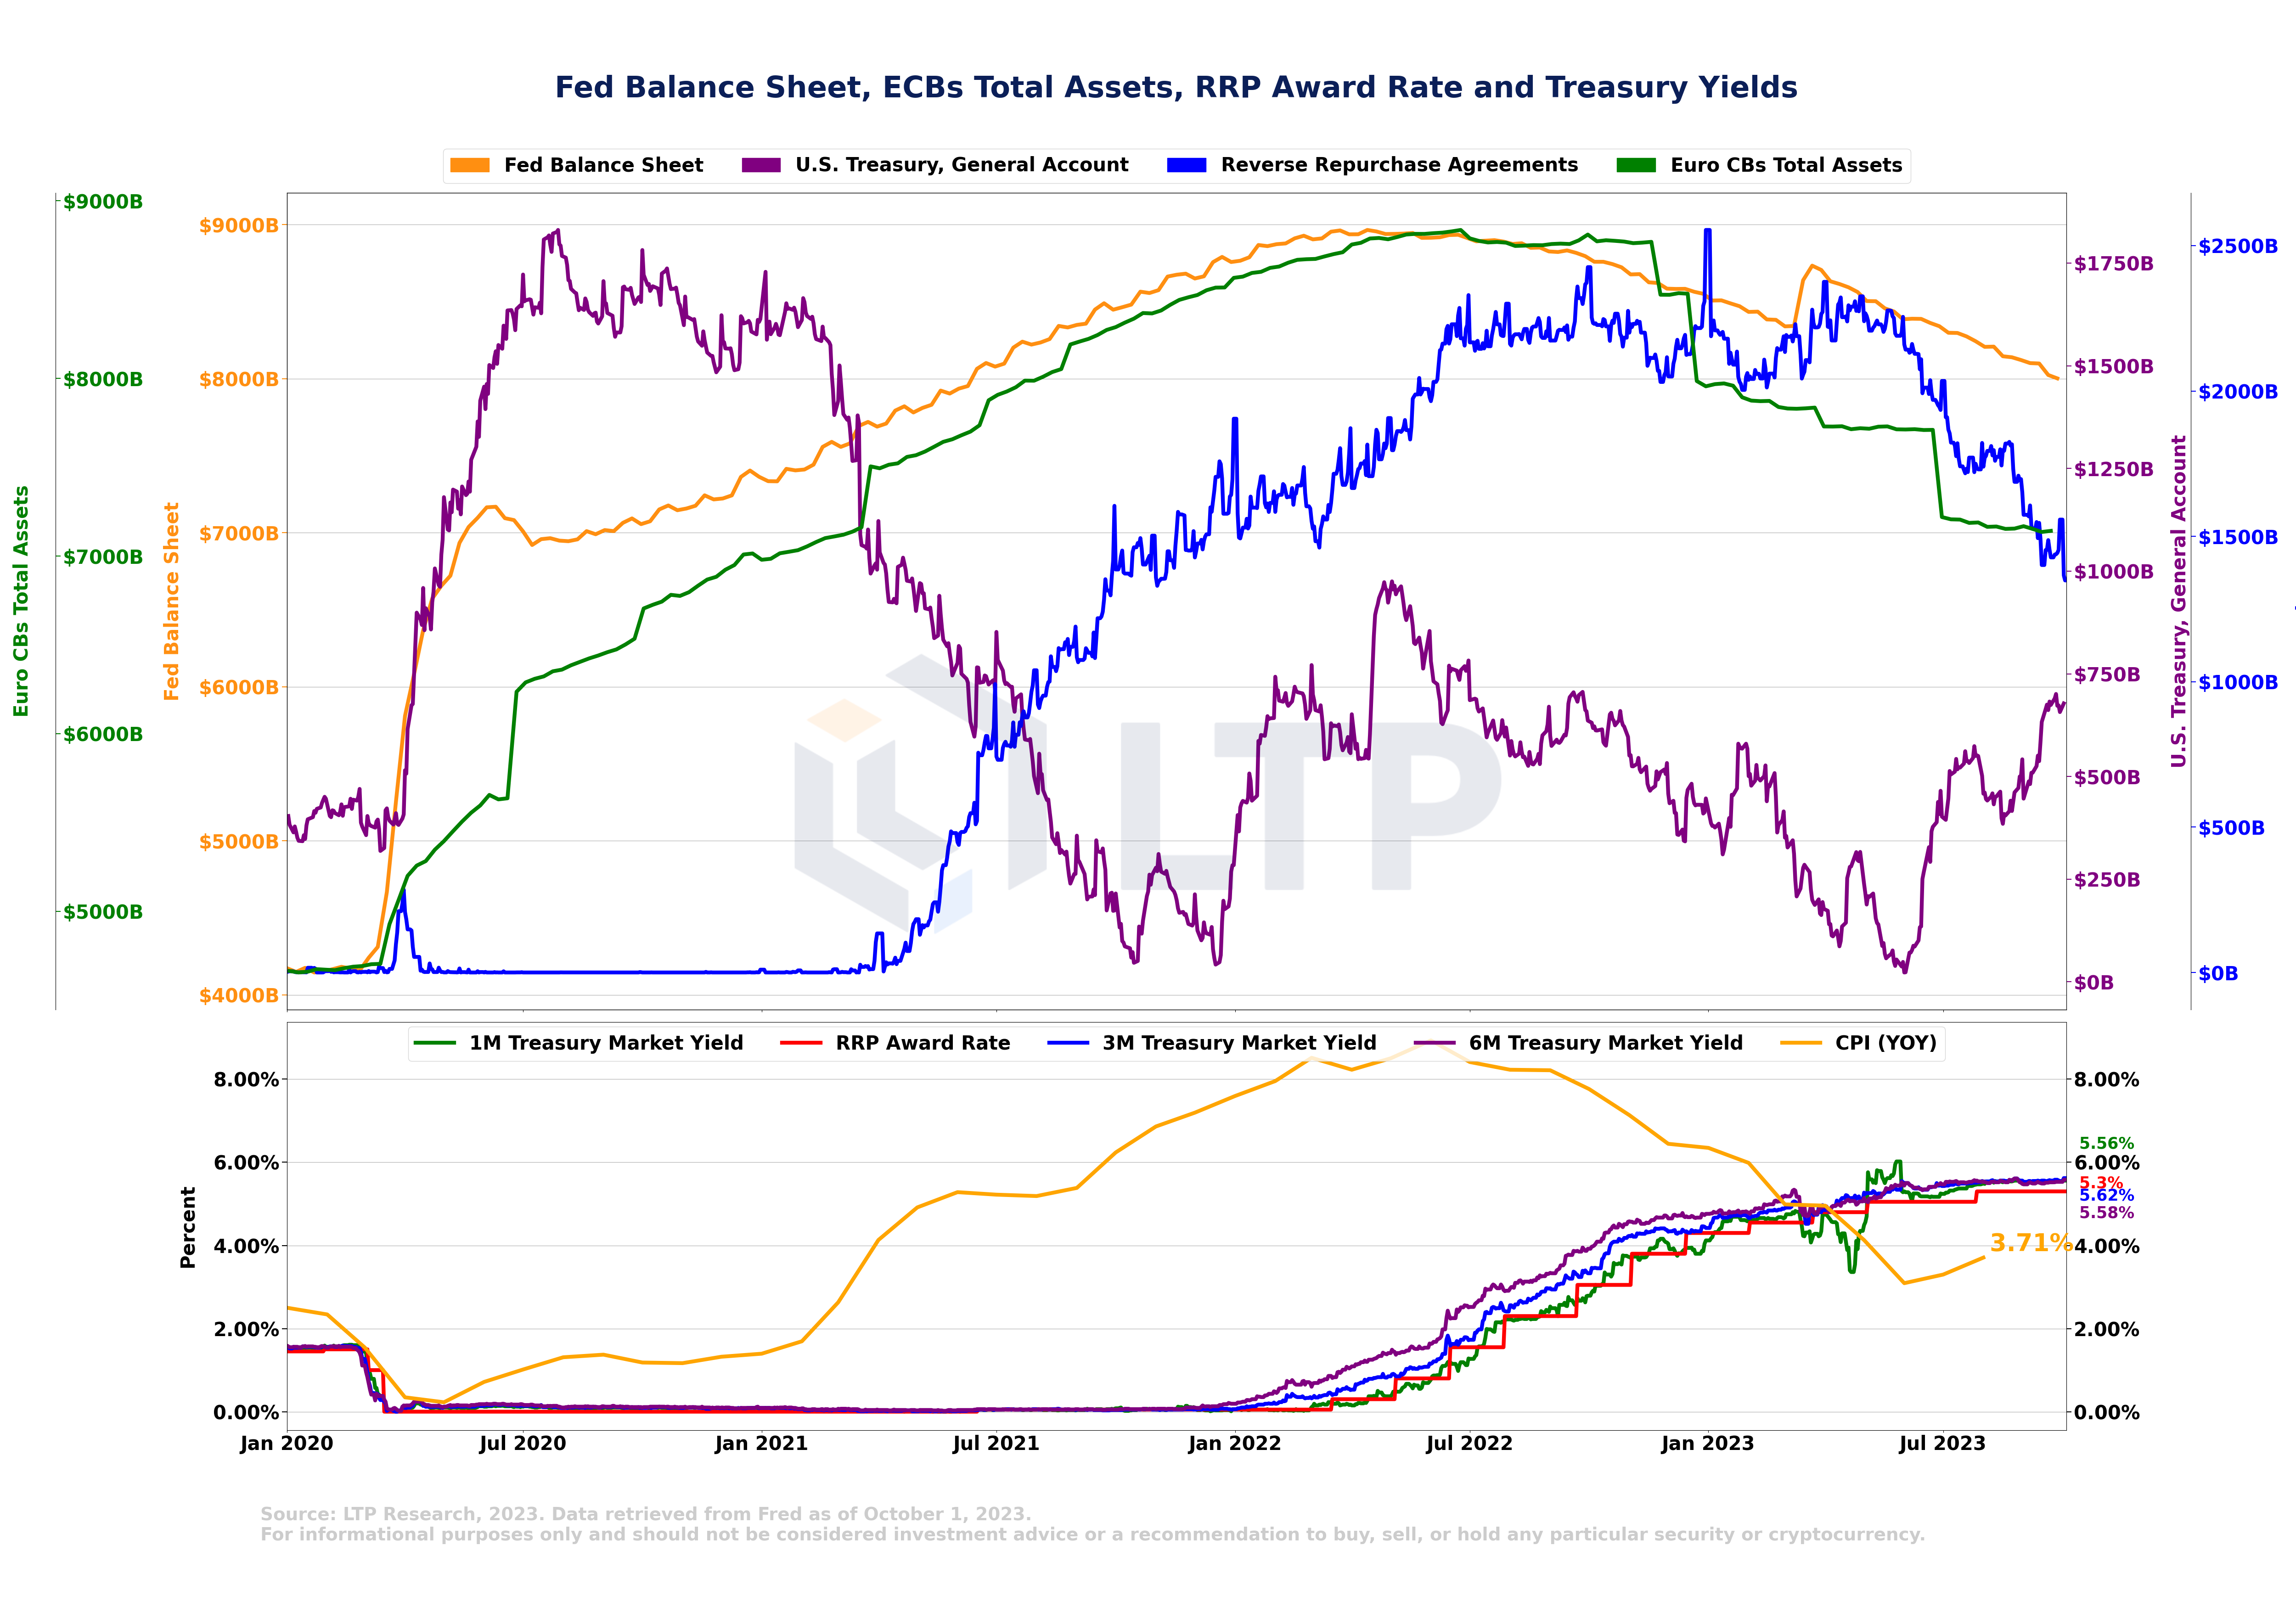
Funds have been observed to continue to move out of Reverse Repurchase Agreements (RRP) with the Federal Reserve and shift towards Treasury bills. This rotation is driven by the higher yields offered by Treasury bills compared to RRPs.
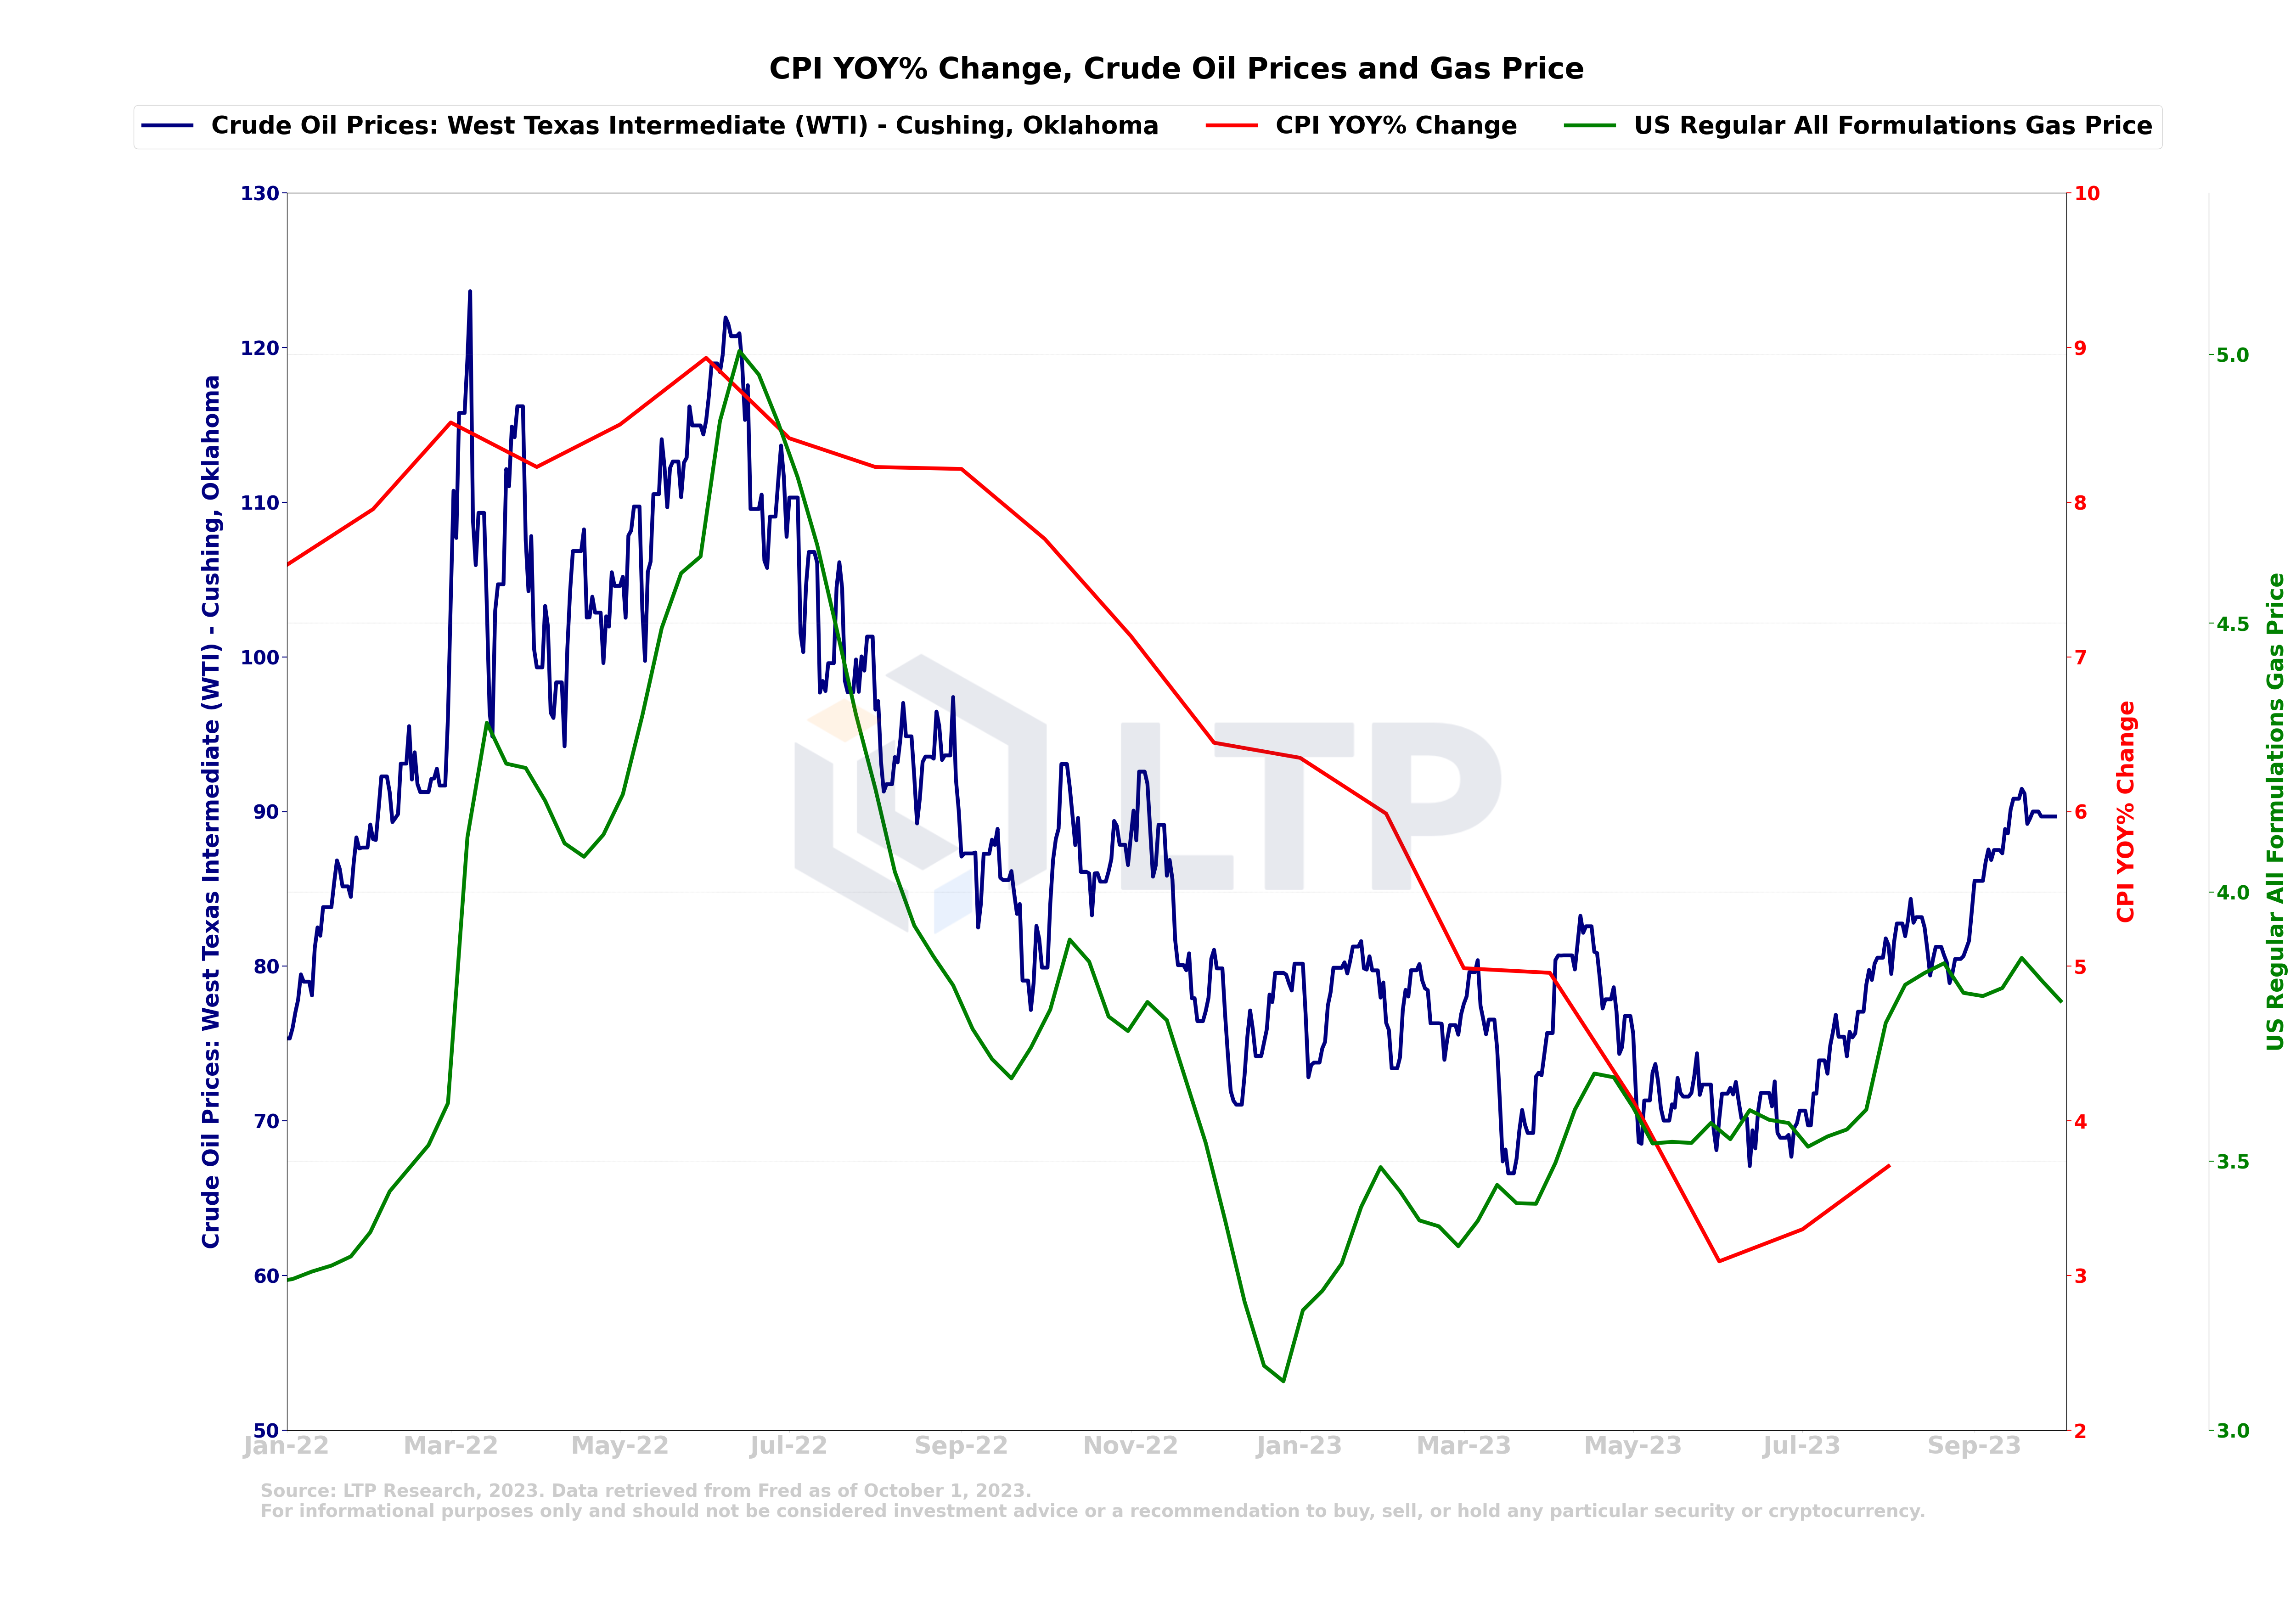
Oil and gas prices have reached their yearly high, which is concerning considering that energy prices are significant contributors to inflation. The spike in energy prices adds to the overall concerns in the fight against inflation.
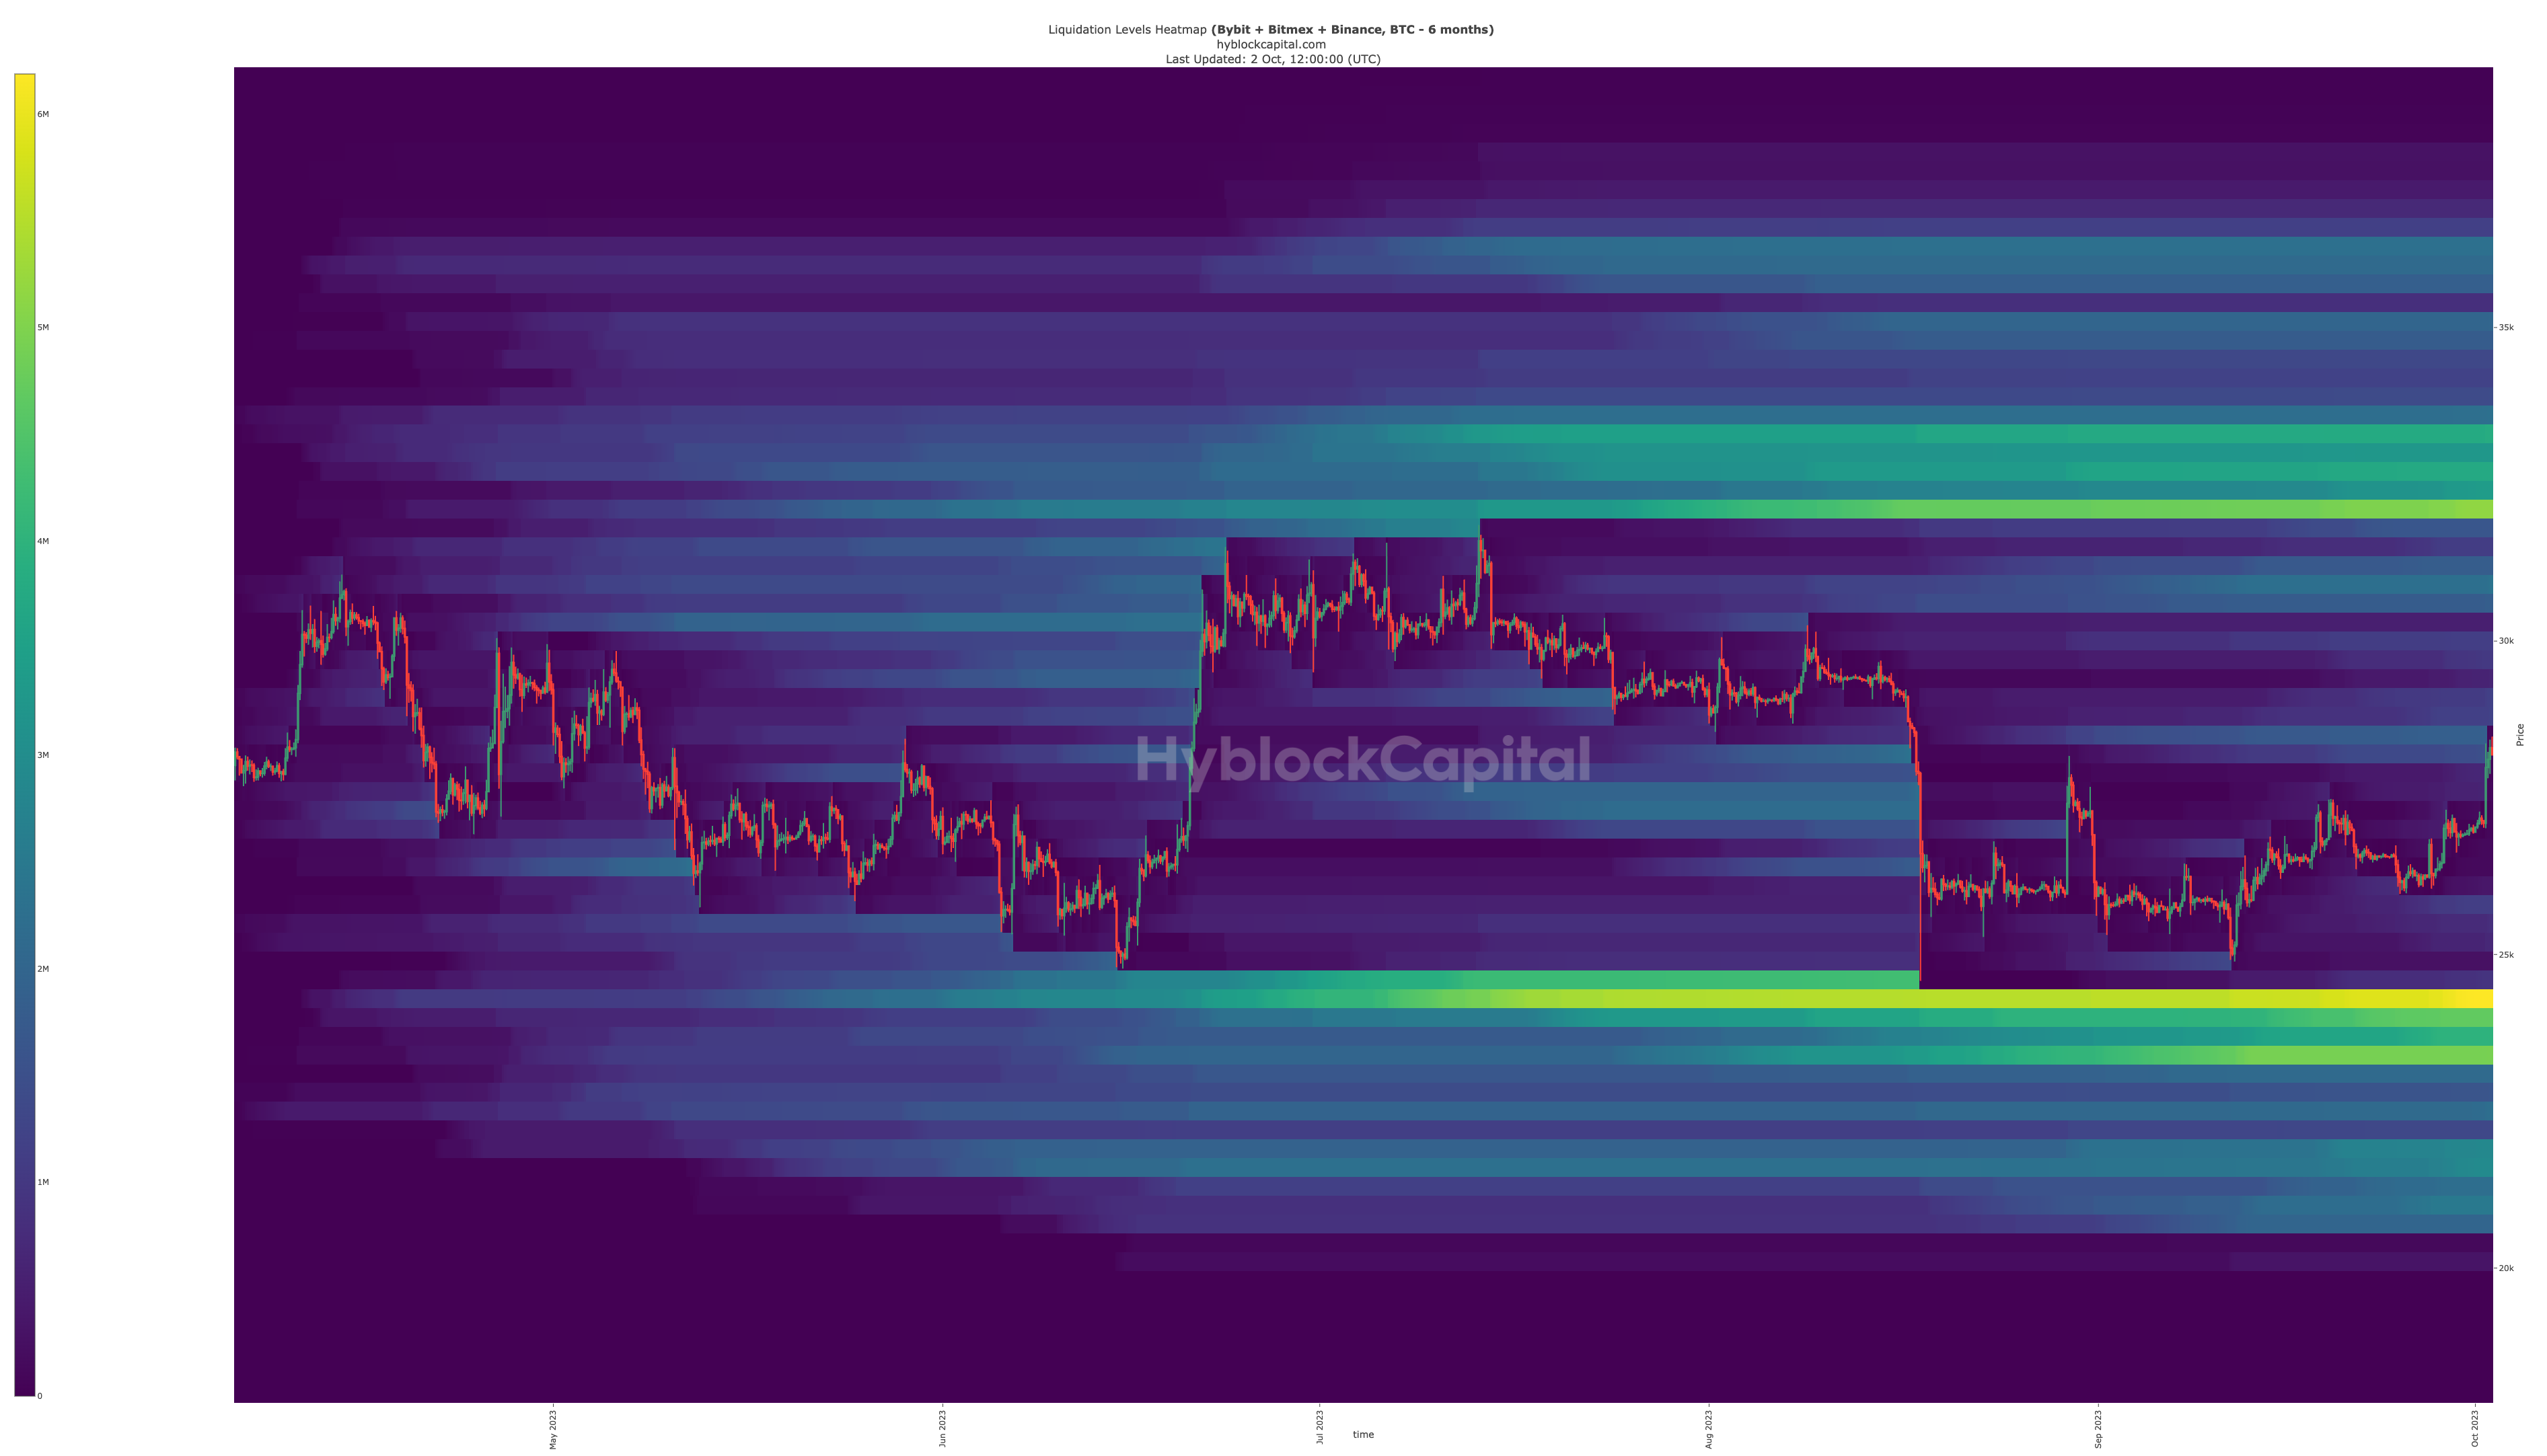
Liquidation zone above market price:$32,000 - $34,000.Liquidation zone below market price:$22,000 - $24,000.
The information, opinions, estimates, and projections contained in this cryptocurrency market commentary (collectively "Information") are provided by LIQUIDITY TECHNOLOGIES INC. (the "Company"). This Information is for informational purposes only and is not intended to serve as investment advice or any form of endorsement or recommendation. The company has taken reasonable measures to ensure the accuracy and validity of the Information provided but makes no warranty as to its accuracy or completeness. The opinions expressed reflect the judgment of the authors at the date of publication and are subject to change without notice.The Information should not be construed as an offer or solicitation to buy or sell or trade in any cryptocurrency, security, or financial instrument. It does not account for individual investment objectives or the financial situation of any readers. Cryptocurrencies are volatile and complex products and are subject to significant risks including the risk of sudden and substantial price movements.Investments in cryptocurrencies are not protected by any statutory compensation arrangements in the event of the firm's failure. The value of cryptocurrencies may be affected by changes in currency exchange rates, regulatory interventions, or other political and economic developments.Investors should be aware that the value of their investments can fall as well as rise, and they may not receive back the original amount they invested. If you are in any doubt about the contents of this document, you should seek independent professional advice. Any historical information contained in this Information is based on our own analysis and is provided for illustrative purposes only. Past performance is not indicative of future results, which may vary.In no event shall the company, nor its directors, employees, agents, partners, suppliers or affiliates, be accountable or liable for any indirect, incidental, special, consequential or punitive damages, including without limitation, loss of profits, data, use, goodwill, or other intangible losses, resulting from the use of this Information. The company reserves the right to change, modify, add, or remove portions of this information for any reason at any time without notice.


All Comments